


Cheap business owner's policy insurance
The cheapest BOP insurance starts around $35 per month for low-risk Insureon customers, and the average small business pays $83 per month. Here’s how to save money and get an affordable business owner’s policy.
Why BOP is already one of the most affordable business insurance options
A business owner's policy (BOP) comes with a built-in discount, because small business insurance carriers bundle general liability insurance and commercial property insurance at a reduced rate.
One of the easiest ways to get a cheap BOP is with Insureon's online marketplace. Submit one online application to compare quotes from top-rated insurance providers. While our customers pay an average of $83 per month for a BOP, 25% pay less than $50 per month, and another 33% pay between $50 and $100.
A BOP typically provides protection for:
- Injuries to customers, clients, and other third parties
- Damage to property owned by your business or a third party
- Product liability for items manufactured, distributed, or sold by your business
- Libel, slander, and copyright infringement
Some insurance providers automatically include business interruption insurance in their BOPs. Depending on your profession, you may be able to bundle other types of commercial insurance policies as well, such as professional liability insurance or cyber insurance.
BOP vs. buying general liability and property insurance separately
Is a BOP cheaper than general liability insurance? Typically, no—but that comparison misses the point.
Buying general liability and commercial property separately costs an average of $45 and $108 per month respectively, which is more than $150 combined per month. This means at $83 per month for a BOP, small business owners get both coverages for about half the cost of buying them separately, on average.
| Coverage | Typical monthly cost |
|---|---|
General liability insurance | $42–$45 per month |
Commercial property insurance | $108 per month |
General liability and commercial property purchased separately | $150–$153 per month |
BOP (General liability and commercial property bundled) | $83 per month (25% pay under $50) |
Table of contents
Who qualifies for the cheapest BOP rates
Small businesses with the lowest premiums typically have business profile characteristics that deem them lower risk. Having a lower risk profile means you're likely to have:
- Fewer employees. Having a smaller workforce reduces the risk of accidents, injuries, and liability claims.
- Smaller physical footprint. Operating out of a smaller commercial space or a home-based office usually means less expensive property to insure.
- Lower revenue. Generating lower annual revenue typically means you have a smaller client base and less exposure to potential claims.
- Safer location. Working in an area that has a lower risk of hurricanes, flooding, or less property crime can lower your rates.
- Cleaner claims history. Having a clear claims record is viewed by insurers as lower risk than a company that's filed many claims in the past.
Not every business will qualify for a BOP. In general, insurers require businesses to be small to mid-size, carry low to moderate risk, and fall under a revenue threshold. Larger and higher-risk businesses should consider a commercial package policy (CPP).
A CPP allows you to bundle multiple business insurance policies with different limits for each covered loss, to meet your business needs. It includes commercial general liability insurance and commercial property insurance, as well as the flexibility to add other policies, such as:
- Commercial auto insurance
- Commercial crime insurance
- Inland marine insurance
- Professional liability insurance
- Equipment breakdown coverage
- Commercial umbrella insurance
As with a BOP, it's typically cheaper to bundle multiple policies in a CPP than buy them separately.



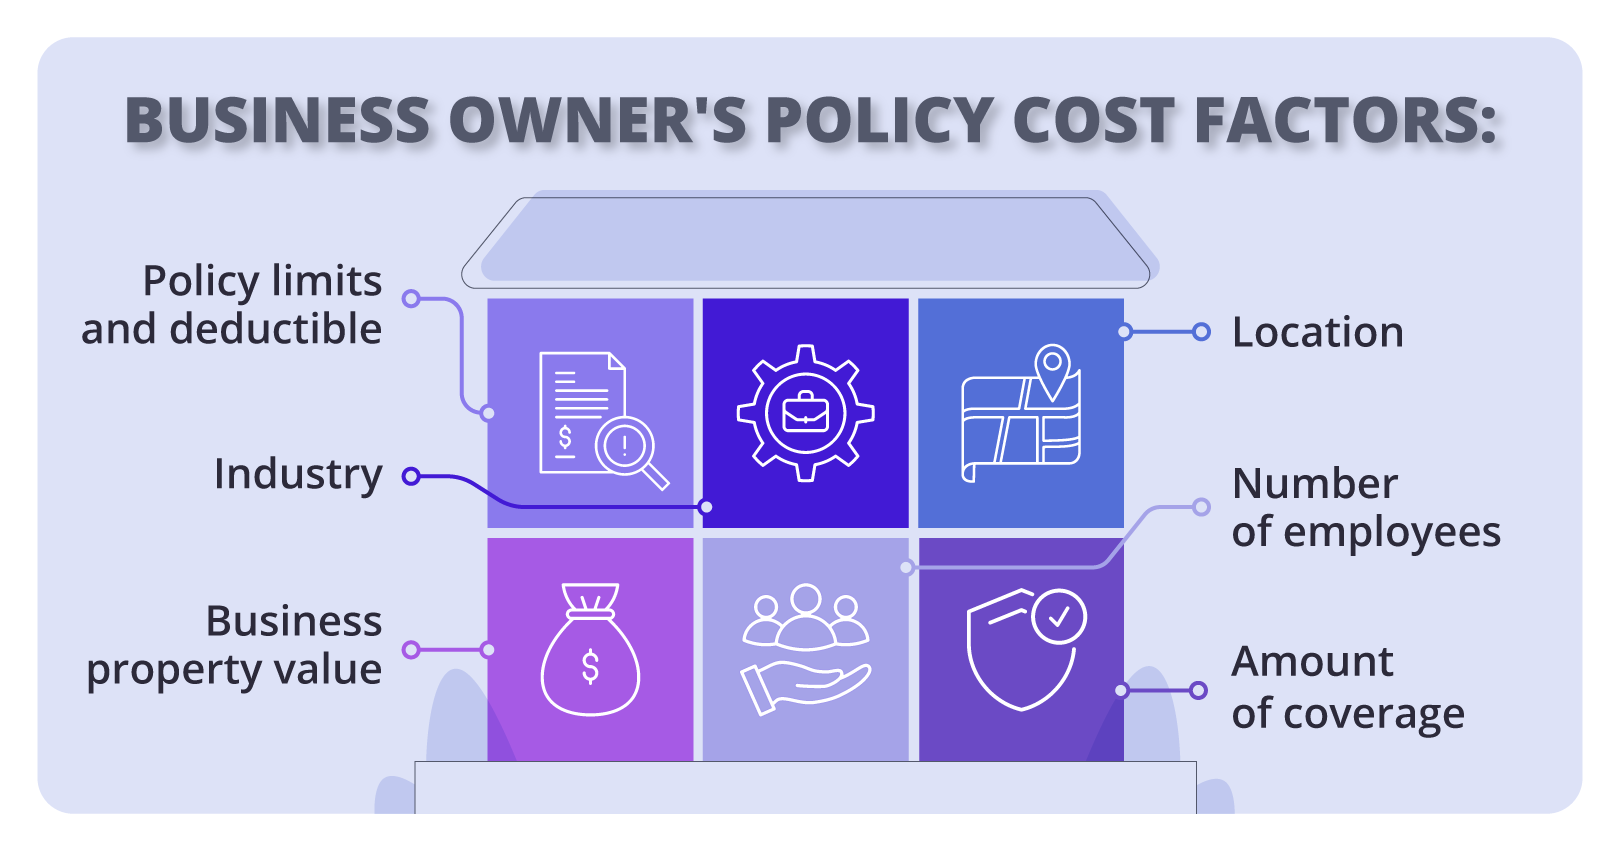
The cost of a business owner's policy varies based on several factors related to your business's risk level, property value, and coverage needs. Insurers use this information during underwriting to estimate the likelihood and potential cost of a claim.
Here are the main factors that typically increase BOP premiums:
- Value of your property and equipment: The more expensive your equipment, inventory, and furnishings are, the higher your premium will be. Your rates also depend on whether you insure your business property for its actual cash value (depreciated value) or for the replacement value, especially if you want to purchase a new item after a loss.
- Type of business: Your industry plays a major role in determining risk. Restaurants, retail stores, contractors, and other businesses with higher chances of accidents, property damage, or customer injuries usually pay more for a BOP than consulting offices and other professional service providers.
- Business location: Properties in states with higher average insurance rates and in areas prone to catastrophic weather and severe storms will bring higher premiums.
- Policy limits and deductibles: Higher coverage limits generally mean higher premiums because the insurer could pay more in the event of a claim, however this is typically worth it for businesses with substantial assets or liability exposure.
- Claims history: If your business has filed multiple insurance claims in the past, insurers may view it as a higher risk and charge more for coverage.
How much does a business owner's policy cost?
A business owner's policy starts as low as $35 per month for low-risk businesses. The average cost of a business owner's policy is $83 per month.
About 25% of Insureon's customers pay less than $50 per month for this policy. However, annual premiums can range from around $400 to over $6,000 per year.
The majority of Insureon's customers (79%) choose a BOP with limits of:
- $1 million per-occurrence limit
- $2 million aggregate limit
Your premium depends on the limits and deductibles you choose, among other factors.
Verified BOP coverage reviews
How to lower your BOP cost
A lower premium is always worth pursuing, but if the coverage behind it isn't accurate or sufficient for your needs, it could end up costing you more in the long run.
For example, setting property limits below actual replacement value means covering the gap out of pocket after a loss, and dropping business interruption coverage could cost weeks of revenue if you're forced to temporarily shut down.
Here are some smart strategies for reducing your BOP costs:
Compare quotes across carriers. Rates for identical coverage can vary significantly across insurance companies. Insureon's digital marketplace lets you compare business insurance quotes from top-rated carriers, such as The Hartford, Hiscox, and Chubb, with a single online application.
Right-size your property coverage. Insuring your property for more than its actual value inflates your premium without adding real protection. If your budget is tight, an actual cash value policy costs less than a replacement value policy, since it covers the depreciated value versus the original purchase price.
Raise your deductible. The average BOP deductible for Insureon customers is $500. Choosing a higher deductible lowers your monthly premium, but make sure you select a number you can comfortably pay when a claim arises, since coverage won't kick in until you do.
Manage your risks. A clean claims history is one of the most effective ways to keep your BOP costs down. Establishing basic risk management steps like employee training, security systems, and well-documented safety procedures can reduce the likelihood of a claim and show insurers your business is well-run.
Pay your premium annually. While you can choose to pay your premium monthly, many insurers will offer a discount if you pay the full premium up front.
Cheapest states to buy a BOP
The state where your business is located can help determine how much you'll pay for insurance. For example, a small shop in rural Virginia would cost much less to insure than a similar shop in urban New York.
Here are some of the states where business owner's policies are lower than average:
| State | Business owner’s policy cost |
|---|---|
$59 per month | |
$69 per month | |
$70 per month | |
$71 per month | |
$71 per month | |
$74 per month | |
$78 per month | |
$78 per month | |
$79 per month | |
$79 per month |
Cheapest industries for BOP insurance
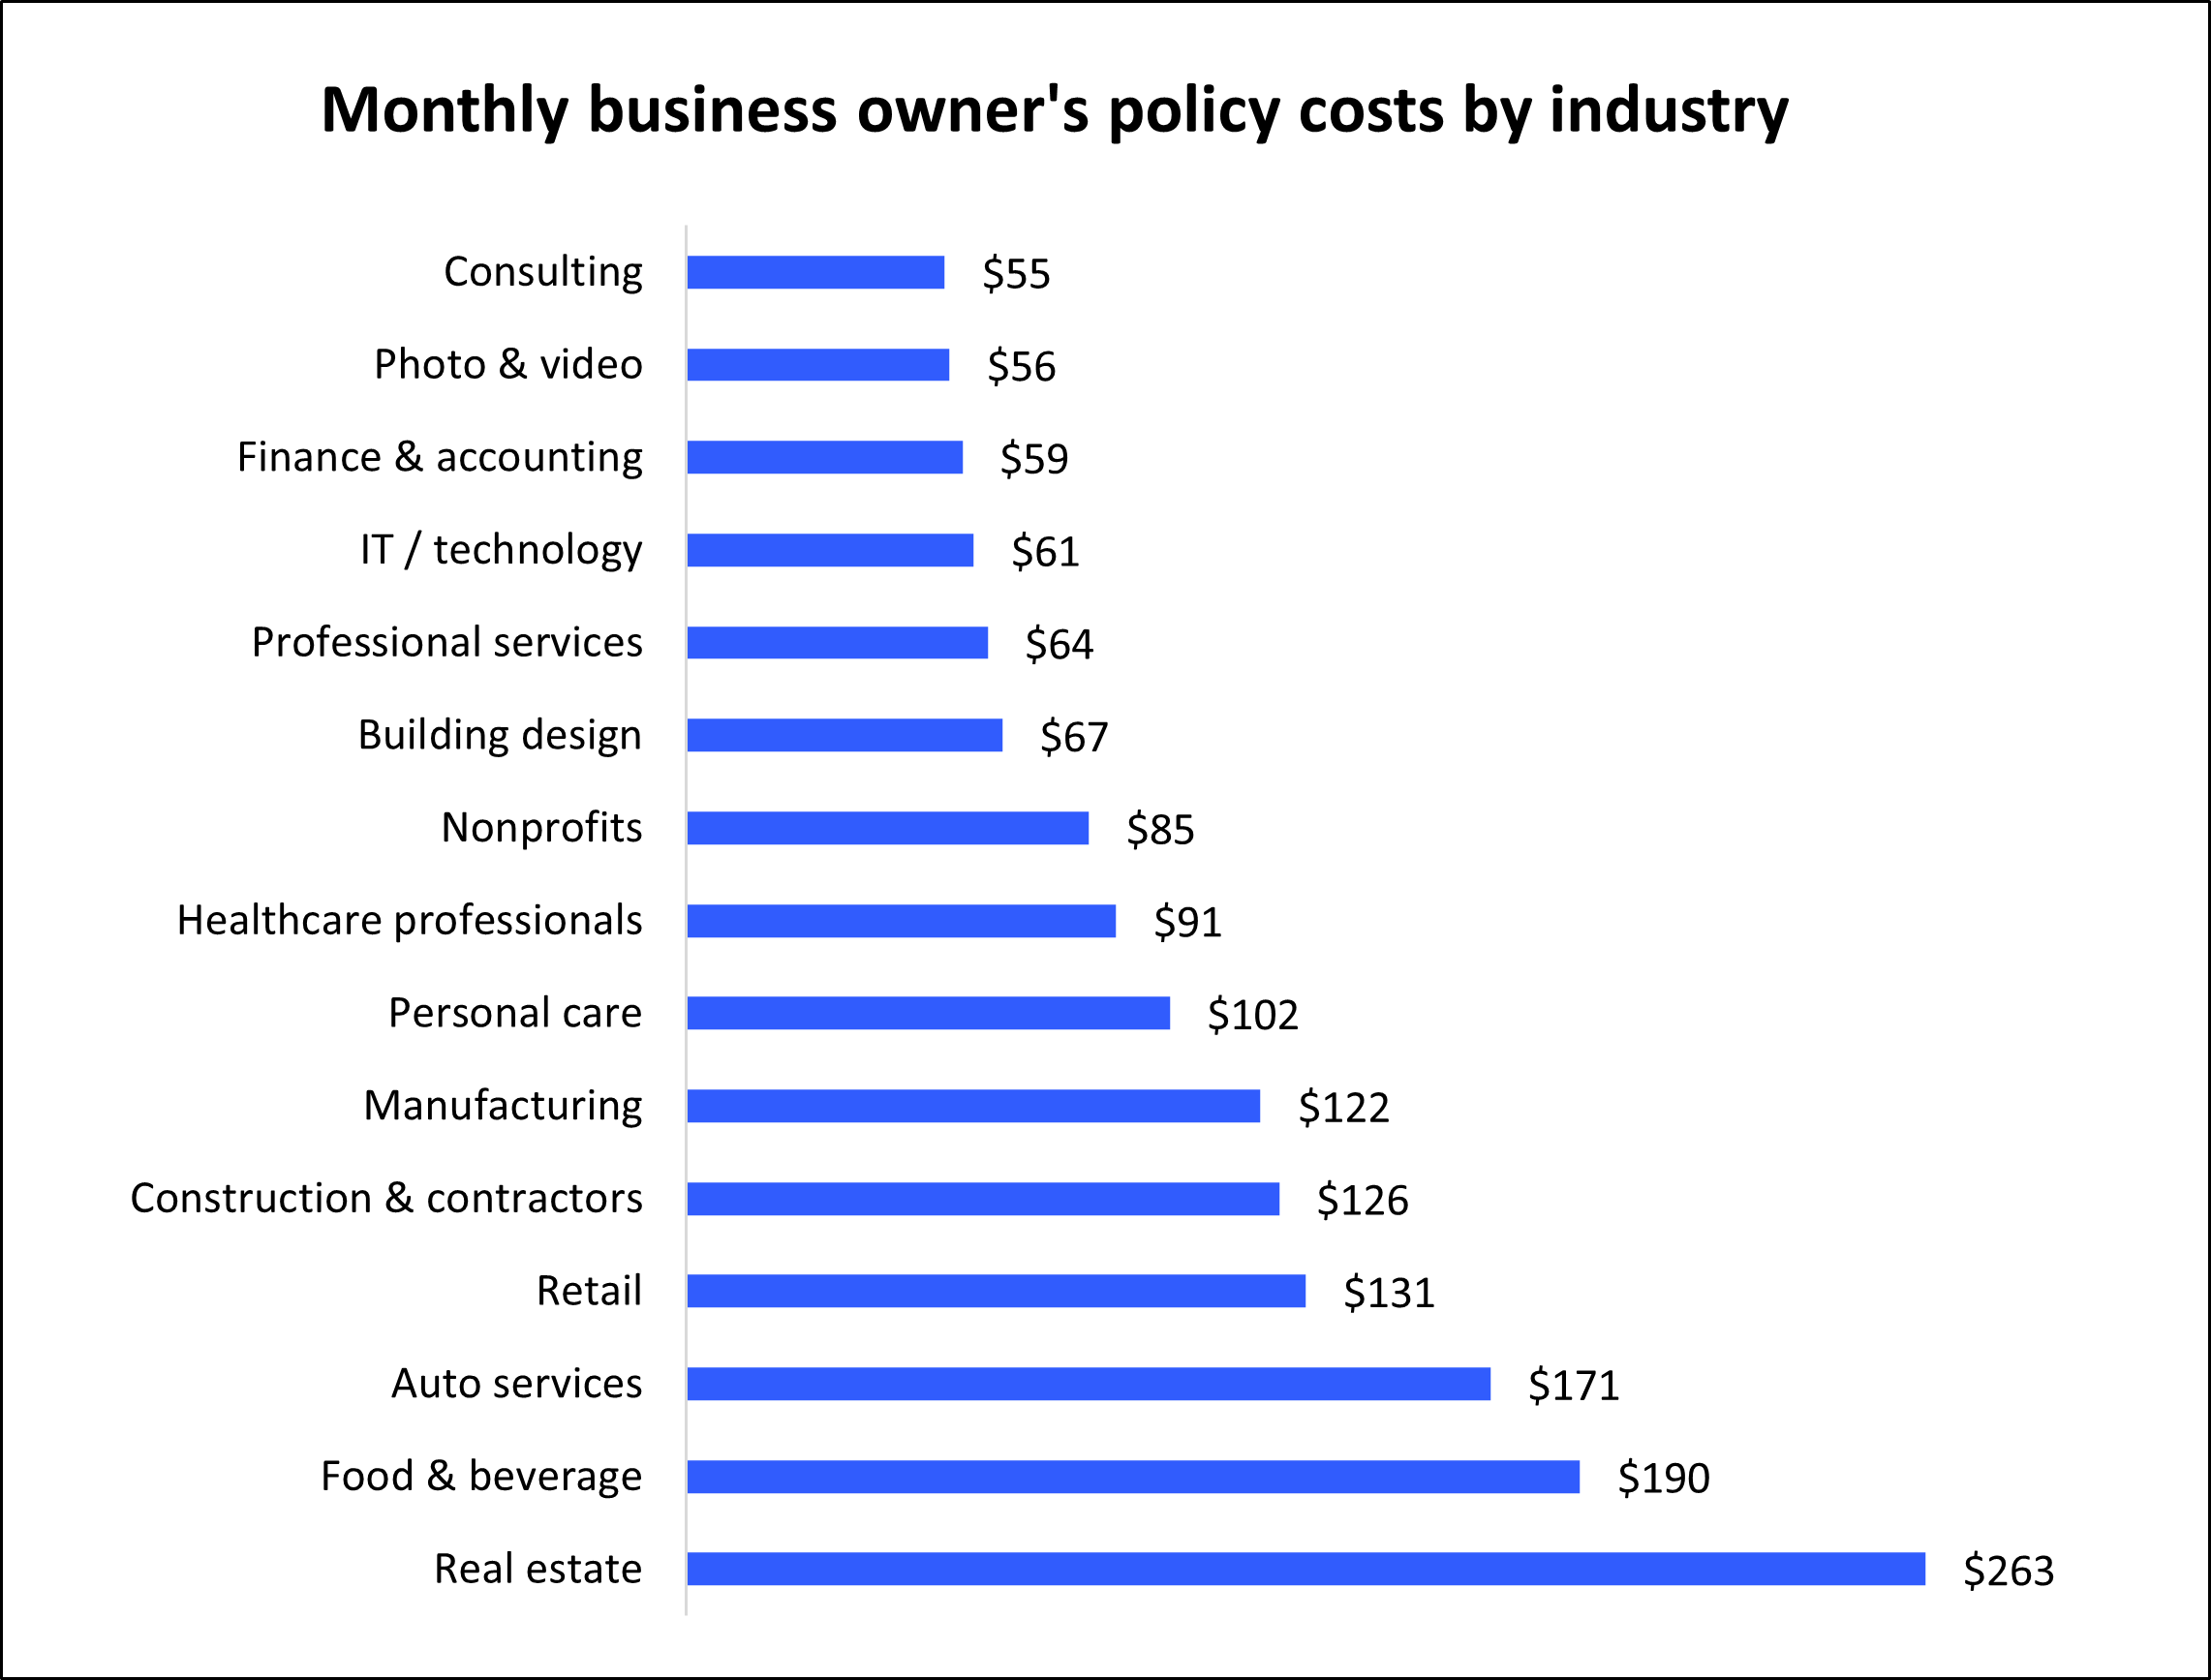
Your industry can significantly impact how much you'll pay for a business owner's policy. Costs are often lower for businesses that don't typically interact with the public or handle customer property. This includes consulting firms, IT businesses, and media companies.
However, industries like real estate, manufacturing, and construction generally have higher BOP rates because of their valuable equipment and property, as well as an increased chance of third-party claims for bodily injury or property damage.
The chart below illustrates how your type of business affects what you'll pay for a business owner's policy.
Top professions that need a BOP
Get cheap BOP quotes with Insureon
Complete Insureon's easy online application today to get free BOP insurance quotes from top-rated U.S. companies. You can also speak with an agent about the types of insurance package coverage your business needs and how you can save money on insurance.
Once you find the right policy, you can usually begin coverage and get your certificate of insurance (COI) in less than 24 hours.

General liability insurance

Workers’ compensation insurance

Professional liability insurance

Cyber insurance

Commercial auto insurance
The average costs on this page were derived from our data on 100,000 small business owners who purchased policies through Insureon. At least 5% of our customers pay at least or less than $35 per month for a business owner's policy.
Most of our customers have less than five employees, annual revenue ranging from less than $50,000 to more than $200,000, and five years or less in business.