

Cheap business insurance
Insuring your small business doesn't have to cost a fortune. At Insureon, we help you find affordable coverage that meets the unique needs of your small business, through a single online application. That way you can get peace of mind without breaking the bank.
How do I get cheap business insurance?
Starting at $22 per month for general liability insurance and $21 per month for workers' comp, it's easy to find affordable small business insurance with Insureon.
In addition, businesses with an office can get commercial property insurance starting at $29 per month, or bundle general liability and property insurance in a business owner's policy (BOP) at an average premium of $83 per month.
Every business owner can take these steps to lower their insurance costs:
- Compare quotes
- Bundle policies
- Customize policies
- Manage risks
You can compare quotes with Insureon's easy online application, which retrieves quotes from top-rated providers who specialize in your industry. Cost-saving bundles and inexpensive policy options provide another way to save, while you can also manage your risks to avoid claims and subsequent premium hikes.
- How do I get cheap business insurance?
- Compare quotes to find the best business insurance
- Bundle policies for broader coverage at a lower cost
- How much does small business insurance cost?
- What factors determine the cost of small business insurance?
- Customize your business insurance policies to match your needs
- Manage your risks to maintain budget-friendly coverage
- Cheapest states to purchase small business insurance
- Cheapest industries to purchase small business insurance
- Are there any small business insurance discounts?
- Get affordable commercial insurance with Insureon
Compare quotes to find the best business insurance
As with other items you buy for your business, you'll want to see what different companies are offering before you make a decision. Policies vary in both their coverage and their cost, and not every company will be a good match.
Insureon partners with trusted providers rated Superior or Excellent by AM Best to find the right commercial business insurance for your needs. Our easy online application retrieves quotes from the biggest names in the industry, such as Hiscox, Travelers, Chubb, The Hartford, and others with proven financial strength.
Our licensed insurance agents are available to help you find policies to satisfy client requirements, comply with state laws, or obtain a license for your profession. They can help you get the right policy limits, coverage options, and cost-saving bundles that you might not find shopping on your own.
Once you choose a policy, you can get coverage and a certificate of insurance (COI) in less than 24 hours.
Hear from customers like you



Bundle policies for broader coverage at a lower cost
Business owner's policy
Small, low-risk businesses can often bundle two common types of coverage in a business owner's policy (BOP) for a discount:
- Commercial general liability insurance is often the first policy purchased by a small business. It protects against costs related to everyday customer accidents, such as a slip-and-fall injury that leads to a lawsuit. It also covers accidental copyright infringement and other advertising injuries.
- Commercial property insurance covers costly repairs or replacement of business property and equipment. It can help your business recover quickly after a fire, storm, or burglary.
It may be tempting to cut costs by buying only a general liability insurance policy, but that exposes your business to risks. By paying a little more for a BOP, you gain protection against the most common and costly insurance claims, such as a burst pipe that destroys your business's inventory.
Midsize businesses or those that are higher risk can buy the same coverages bundled in a commercial package policy (CPP) instead. A CPP offers more flexible coverage options and higher policy limits if a BOP is not sufficient.
In addition, smaller, home-based businesses can combine general liability with professional liability insurance to cover claims of professional negligence, or add business personal property (BPP) insurance to cover computers, inventory, and other business-owned items.
Both BOPs and CPPs often include business interruption insurance, also called business income coverage, which pays for financial losses if a fire or other covered property claim forces your business to close. Our licensed agents can help you customize a policy bundle to fit your business's unique needs.
Tech errors and omissions insurance
Tech companies can often combine two important types of coverage in a bundle called technology errors and omissions insurance, or tech E&O. This policy includes the following protection:
- Cyber liability insurance, also called cybersecurity insurance, helps companies recover from cyberattacks and data breaches. It can also cover legal fees if your business is sued for failing to prevent a cyberattack or security breach.
- Errors and omissions insurance can cover the resulting legal defense costs if you miss a deadline or make a mistake in your work. This policy is also called professional liability insurance or malpractice insurance, depending on the profession.
Management liability insurance
To protect executives, managers, and other leaders they depend on, small business owners can bundle several types of management liability insurance at a reduced cost, including:
- Directors and officers (D&O) insurance protects your board members and officers from legal costs related to the decisions they make on behalf of your business.
- Employment practices liability insurance (EPLI) covers lawsuits related to discrimination, harassment, wrongful termination, and other violations of employee rights.
Having these policies in place can help attract top talent to your business, as they'll want to know they're financially protected when making important business decisions.
How much does small business insurance cost?
Small businesses with low risks don't have to pay a lot for insurance.
Average business insurance costs for Insureon's customers are:
- General liability: $45 per month
- Business owner's policy: $83 per month
- Workers' comp: $54 per month
Verified business insurance reviews
Hear from customers like you who purchased small business insurance.
What factors determine the cost of small business insurance?
Small businesses pay different premiums depending on the type of business insurance and their risk of a claim. Factors that affect business insurance costs include:
- Your industry and risks
- Business operations
- Number of employees
- Policy limits and deductibles
- Location
- Revenue
- Business structure (sole proprietor, LLC, etc.)
- Claims history
Customize your business insurance policies to match your needs
Commercial insurance products aren’t one size fits all. The right coverage will meet all aspects of your business needs but not exceed it.
For example, when purchasing business property insurance, your coverage limits should match the value of your business equipment. If that amount changes, you’ll need to change your policy too.
Some companies may choose to purchase inland marine insurance, which protects business equipment while in transit or stored off site. For others, it may not be needed.
You can also add business interruption insurance to cover expenses related to a forced closure from a fire or other covered property claim.
Commercial umbrella insurance is a good way to save money and extend liability coverage limits if you’re concerned about escalating legal costs.
Workers' compensation insurance is required in almost every state if you have employees. This policy helps pay for medical expenses if an employee gets injured, and in some cases you can buy it for yourself. Policyholders may be able to save money on their workers' comp with a pay-as-you-go policy or ghost policy.
In addition to workers' comp, some businesses may consider employment practices liability insurance (EPLI), which provides protection when a worker sues over employment-related issues.
Finally, most states require commercial auto insurance for small businesses that own a vehicle.
Choose policy options that provide the right amount of protection
Insureon's licensed agents can prevent you from paying for coverage you’ll never use or that exceeds your needs. Here are a few variables to keep in mind:
- Deductible. A high deductible can make your insurance premium more affordable. But you’ll have to pay more before you can collect insurance benefits.
- Policy limits. A policy limit is the amount your insurer will pay on claims. A lower limit usually means a cheaper premium, but it also means less coverage. Our expert agents can help you determine the right amount.
- Inclusions and exclusions. Inclusions are the events a policy covers, and exclusions are the ones it doesn't. Cheap insurance isn't a good deal if common risks aren't covered.
- Actual cash value versus replacement value. You can insure your business property for its actual cash value (depreciated value) to save money. Or you can insure it for the replacement value if you want to be able to purchase a new item after a loss.
Audit your insurance to avoid overpaying for coverage
As your business changes and grows, so too will your insurance needs. To avoid overpayment or underpayment, your insurance provider will conduct an annual premium audit to make sure you paid the correct amount.
Premium audits are most common for general liability and workers' compensation. A general liability audit, for instance, could reveal that you need more coverage due to opening a new location. A workers' comp audit might show that your estimated payroll for the year was lower than the actual value due to new hires.
Going forward, your insurance company will adjust your premiums based on their findings, and may make recommendations for changes in coverage as well.
Explore more ways to find low-cost business insurance
Manage your risks to maintain budget-friendly coverage
Insurance providers may charge more if they think you run a high-risk operation. The good news? You may qualify for cheaper business insurance if you address trouble spots.
Here are a few risk management strategies for small businesses.
Install security alarms and fire suppression systems
Many insurance companies offer a discount on commercial property coverage for businesses that invest in a central burglar alarm or sprinkler system.
Insurance carriers are particular about what qualifies for a premium reduction. Check first to make sure your upgrade will count for a cheaper policy.
Communicate clearly with clients and customers
An easy way small business owners can reduce the risks of errors and omissions claims is keeping in regular contact with customers.
Make sure you communicate often and honestly with your clients to resolve issues before they turn into a lawsuit. If everyone’s on the same page, you’re much less likely to end up in court.
Create a safe workplace
Implementing safety practices at your business can reduce the chance of general liability claims and workers’ compensation insurance claims. To lower the risk of visitor and employee injuries:
- Clean spills immediately
- Keep walkways clear of clutter
- Add lighting to dark areas
- Install handrails on stairs
- Remove loose rugs and other tripping hazards
An effective loss control program can help you avoid claims and subsequent premium hikes. Plus, fewer accidents saves your business money even beyond lower insurance costs.
Implement cybersecurity protocols
When it comes to cyber insurance, your provider isn't only there for you when you've already suffered an attack. Many insurance providers offer programs that help you reduce your cyber risks.
Implementing cybersecurity controls can reduce the odds of a security breach and save you money on your policy. For instance, your carrier might recommend multi-factor authentication (MFA) for more secure logins, or virtual private networks (VPNs) that encrypt your data to prevent a breach.
In some cases, an insurance provider might have specific requirements before you can secure coverage, as they share your interest of avoiding cyber claims.
Find cheap business insurance with Insureon
[video: a subheading displays the text: "How to get cheap small business insurance"]
MALE VOICEOVER: You know you need insurance for your small business, but where to start? And how can you keep costs down?
[video: an illustrated header displays the text: "Affordable insurance. Fast."]
Insureon is here for you.
[video: an illustrated header displays the text: "Start here" and a screenshot of the Insureon.com homepage]
You can get customized quotes from top carriers.
[video: an illustrated header displays the text: "Customized quotes"; "Policies you need." and a screenshot of Insureon's quotes comparison page]
Most small businesses start with a general liability policy.
[video: an illustrated header displays the text: "General liability insurance: About $42/month"]
You can combine property coverage with your liability insurance at a discount of $57 per month.
[video: an illustrated header displays the text: "Business Owner's Policy: About $57/month"]
Maintaining a safe work environment can help you manage risk and lower your insurance costs too.
[video: an illustrated header displays the text: "Add safety measures. Lower costs."]
Get affordable insurance from the best carriers.
[video: an illustrated header displays the text: "Save money."]
Start your application now!
[video: an illustrated header displays the text: "Get a quote today!"]
Insureon. Protection is peace of mind.
[video: the Insureon logo]
Cheapest states to purchase small business insurance
| State | General liability insurance cost | Workers' comp insurance cost | Professional liability insurance cost |
|---|---|---|---|
$42 per month | $32 per month | $71 per month | |
$42 per month | $38 per month | $83 per month | |
$49 per month | $44 per month | $59 per month | |
$44 per month | $46 per month | $66 per month | |
$40 per month | $45 per month | $70 per month |
Cheapest industries to purchase small business insurance
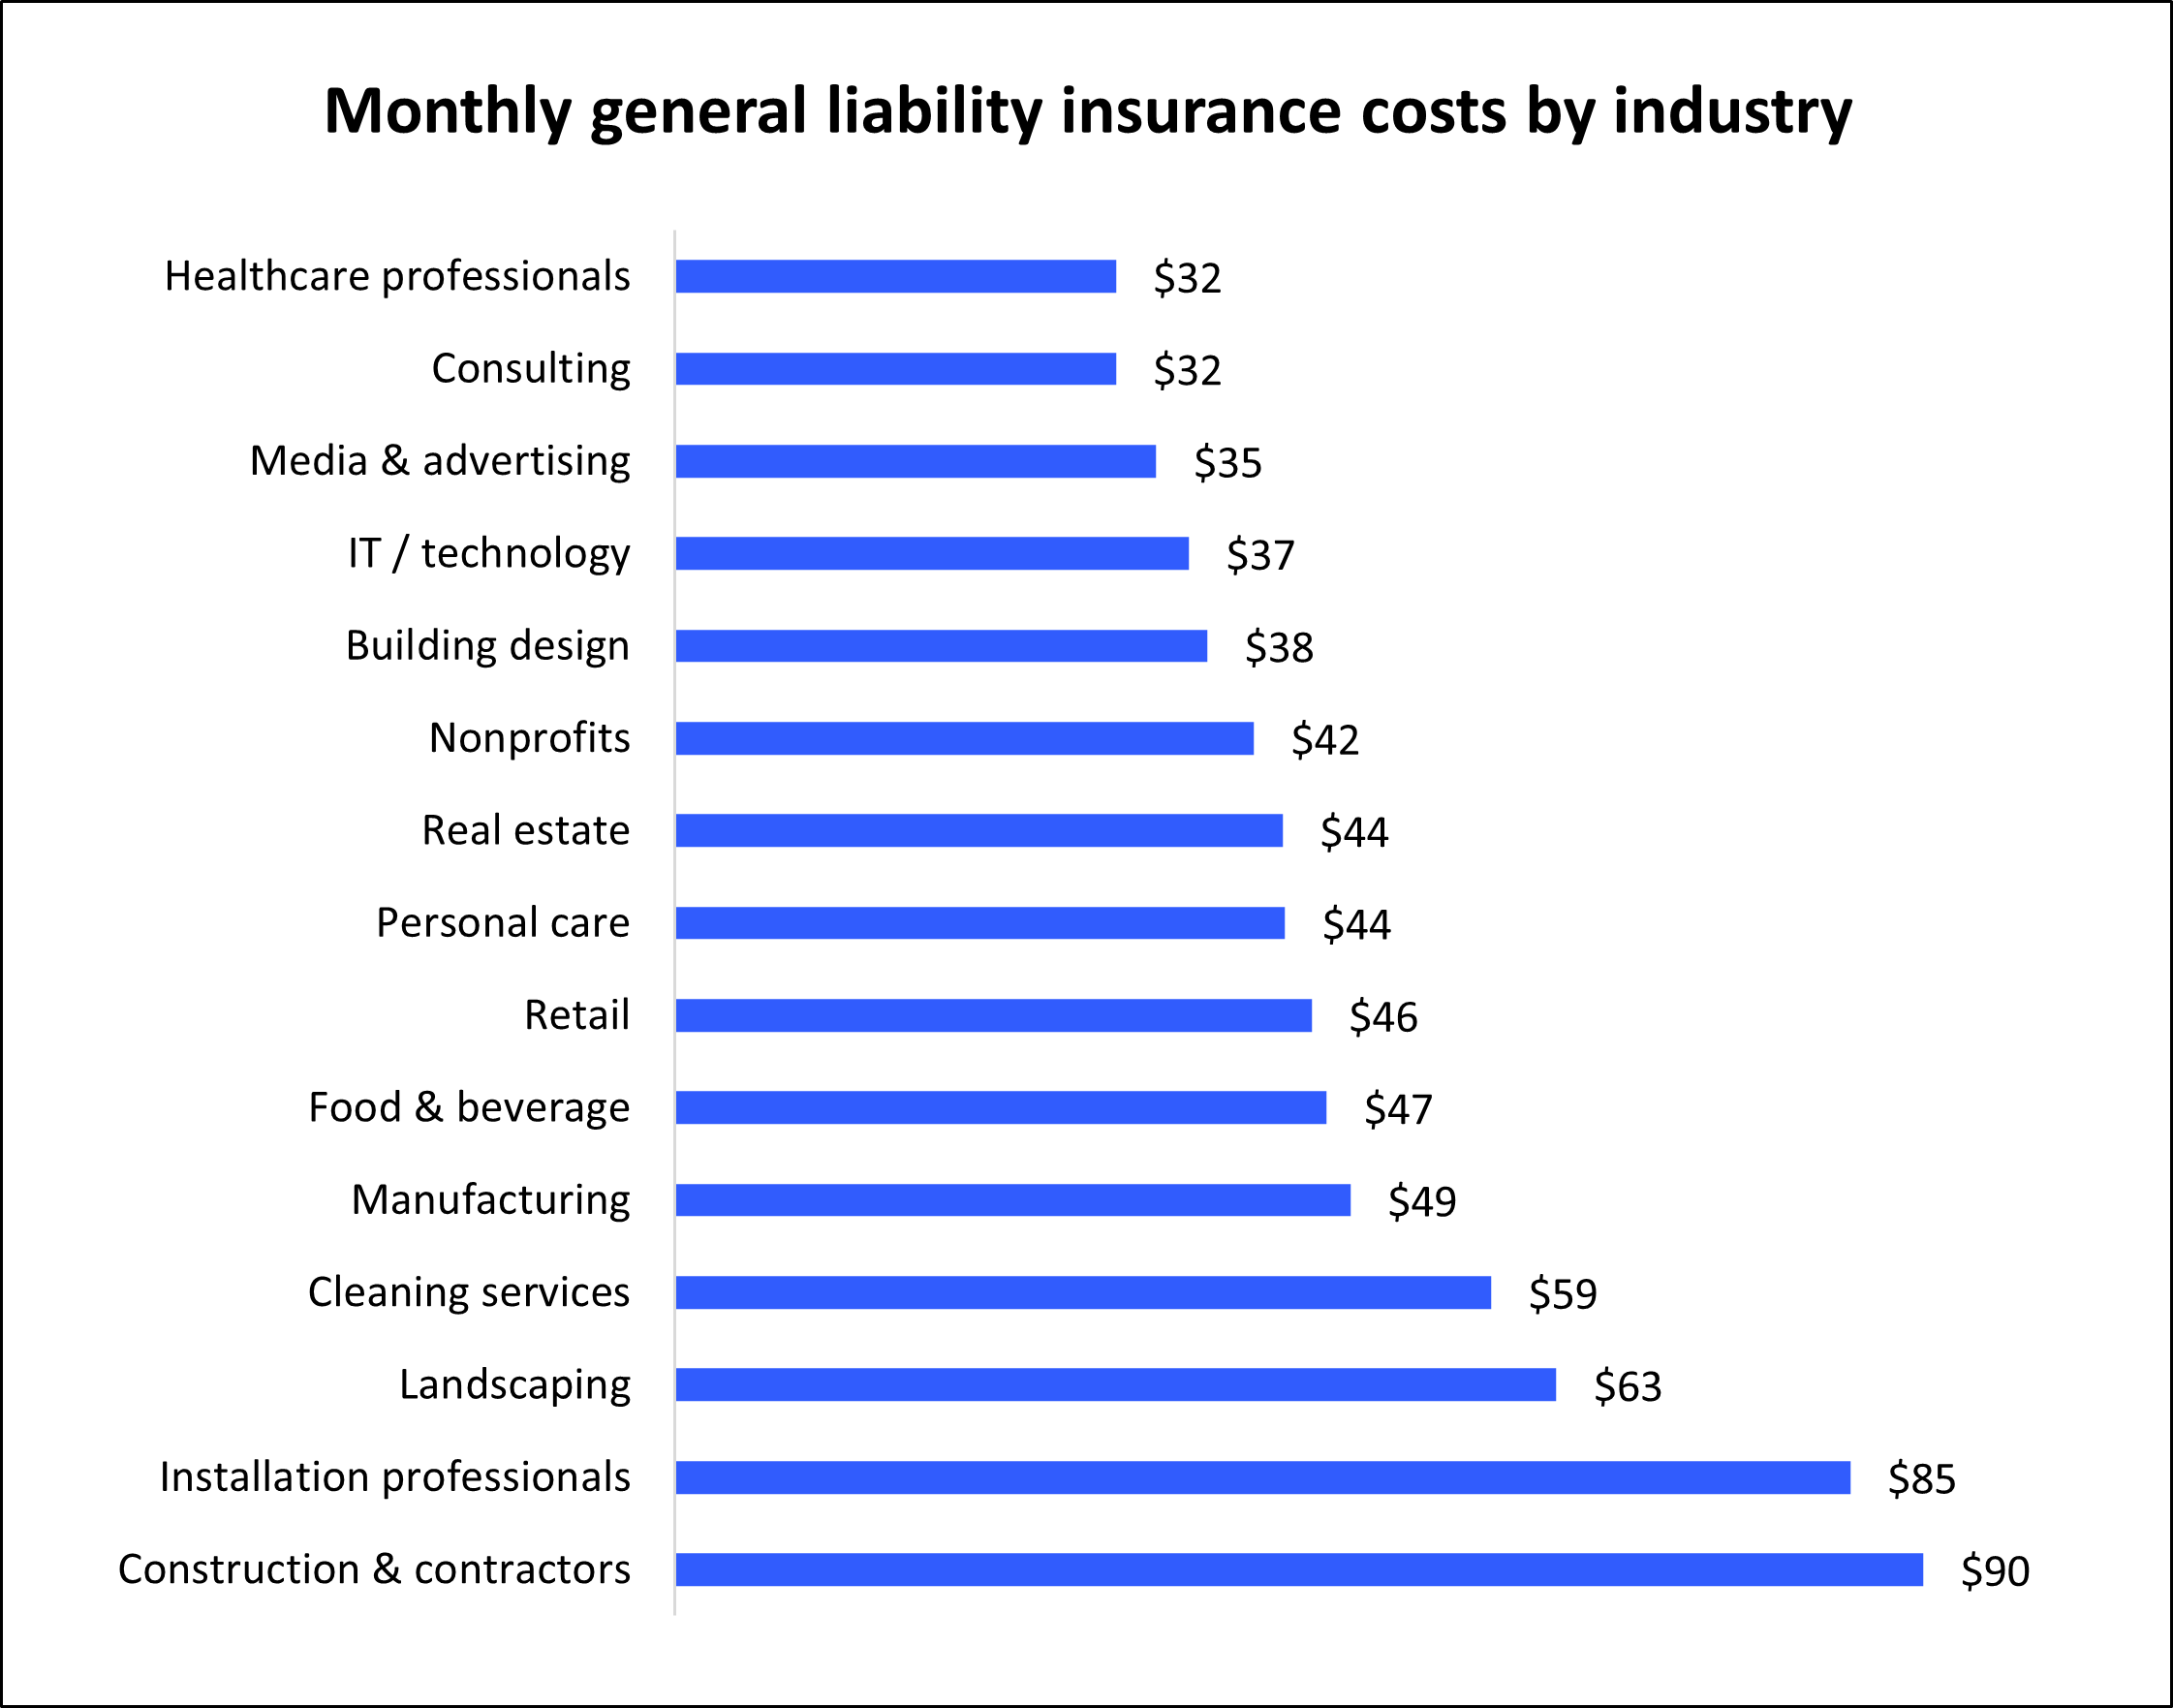
Businesses with a low risk of injuries pay less for general liability
With general liability insurance, industries that have a lower risk of third-party bodily injuries or property damage can expect to pay a lower premium. For example, photographers and companies that offer professional services have minimal risks compared to more hazardous industries like construction and installation.
Workplace injuries drive the cost of workers' compensation insurance
As with general liability, businesses with a low risk of bodily injuries can expect to pay less for workers' compensation insurance. It will cost far less to insure accountants, IT consultants, and other office workers than roofers, general contractors, and other workers who are often injured as a result of their work.

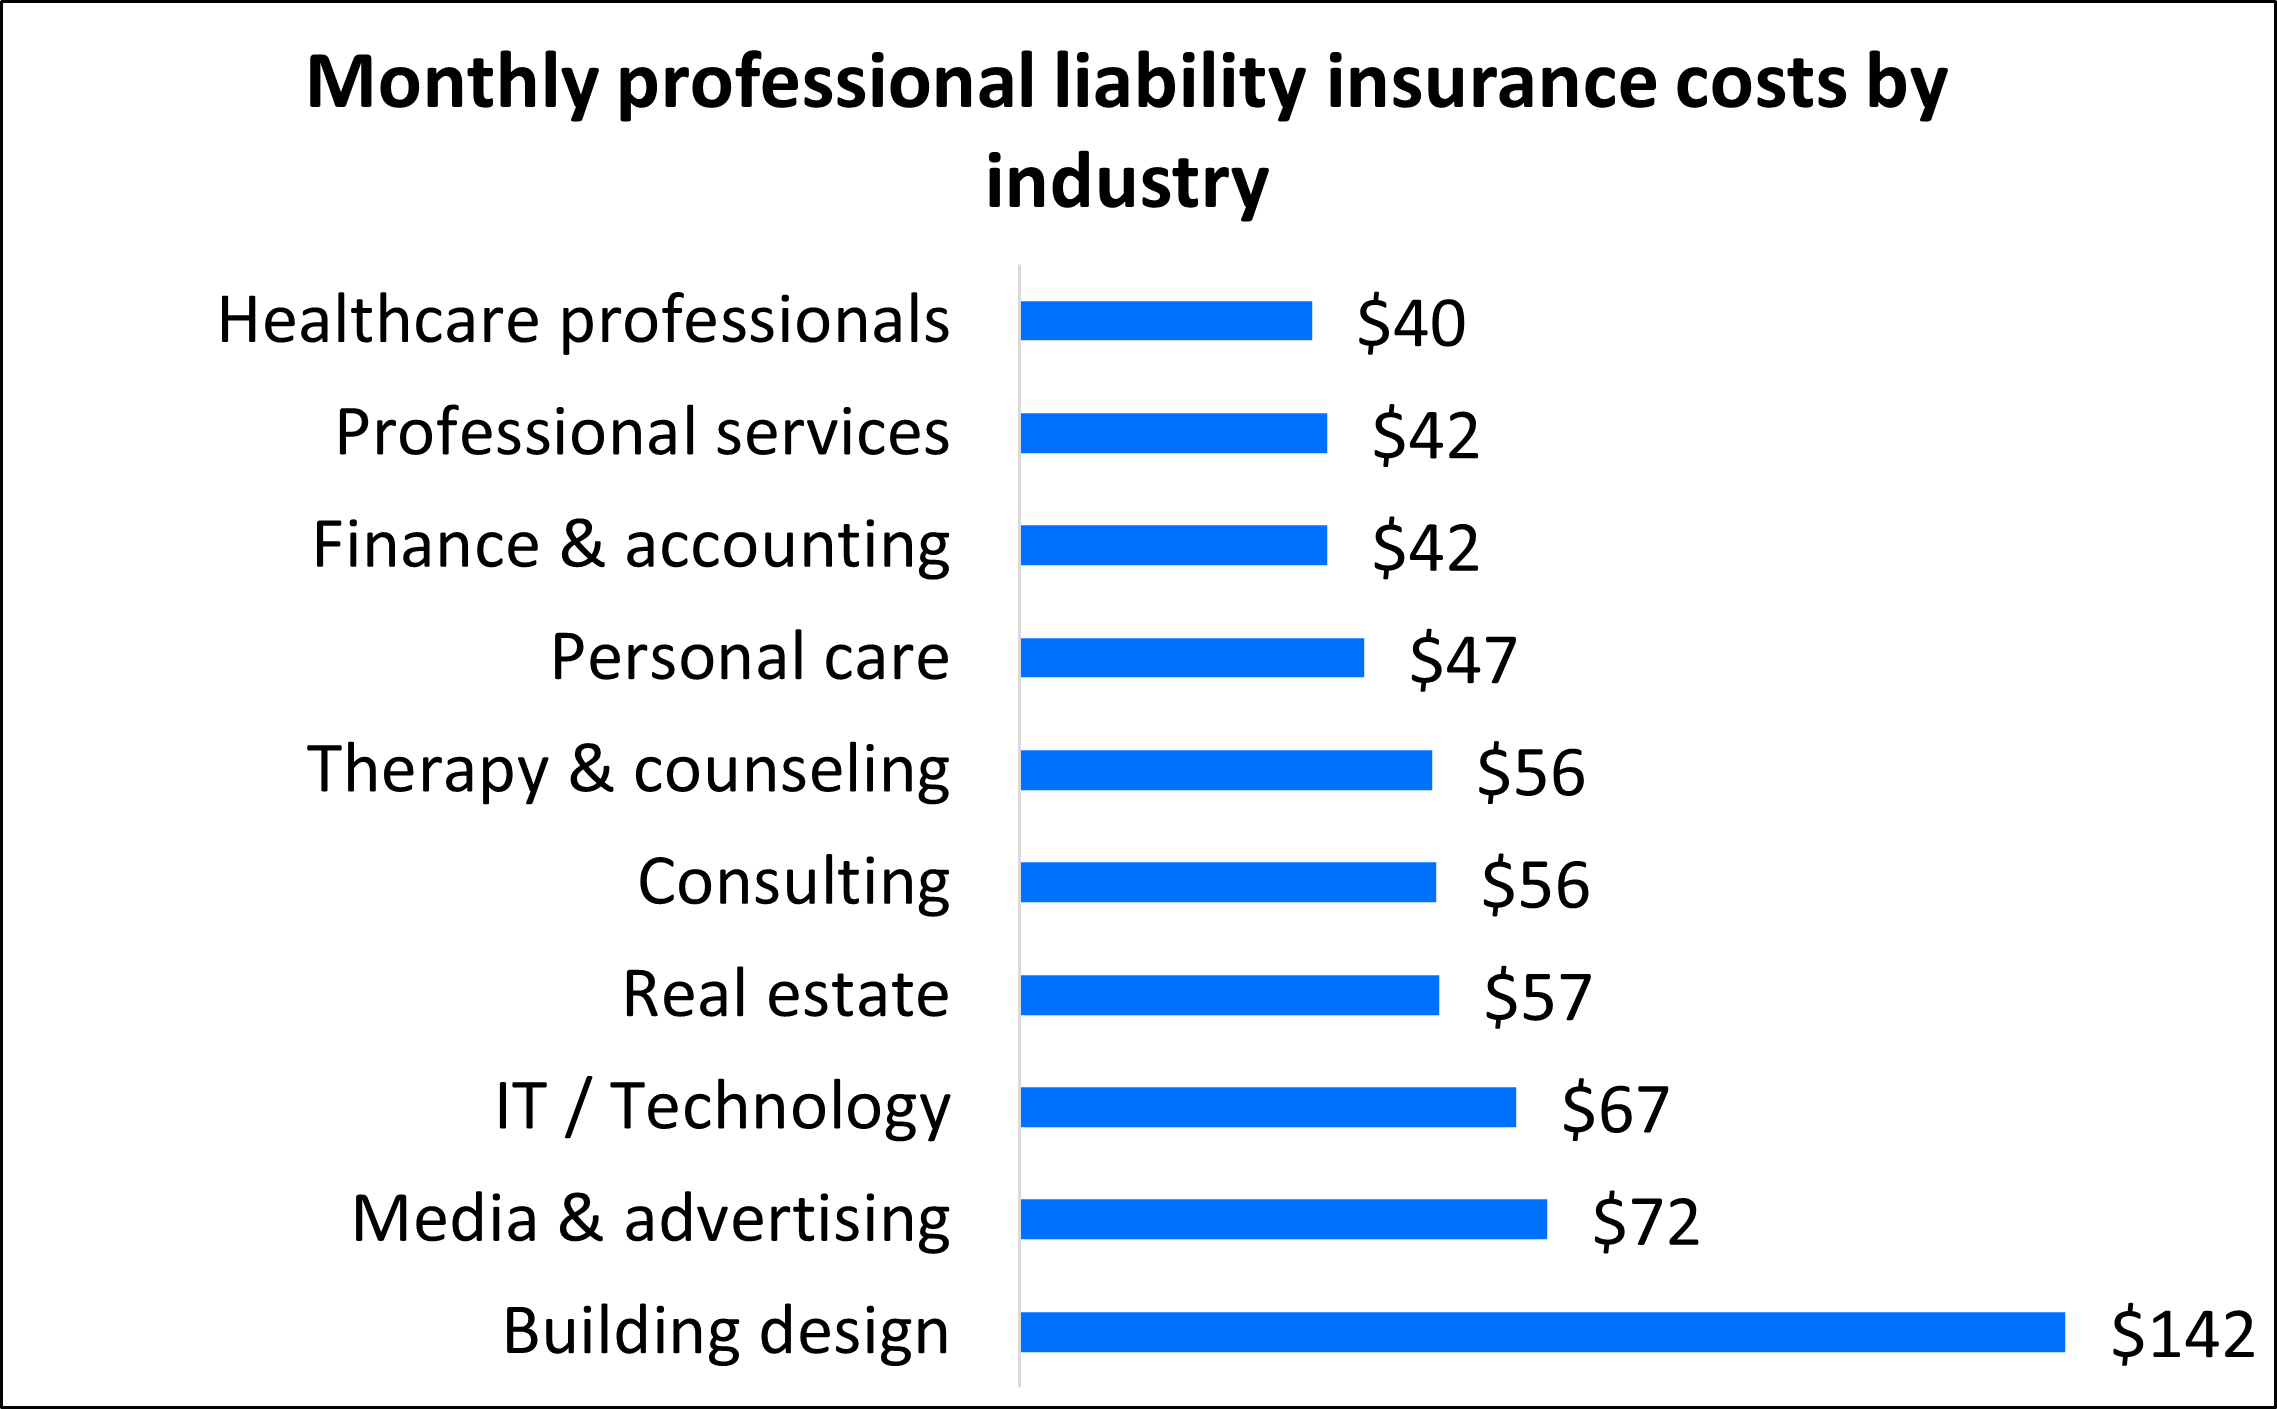
The odds of a client lawsuit affect professional liability costs
For professional liability insurance, the relevant factor isn't physical injuries but financial damages. If your work directly impacts how much money a client makes—or how much they might lose—then you can expect to pay more for this policy.
Architects and other building design professionals can expect higher costs for this coverage, as a flaw in a building could end up costing the owner or developer a fortune.
Are there any small business insurance discounts?
As with other expenses that are ordinary and necessary for your business, insurance coverage is tax-deductible. Business owners can usually deduct their policy premiums from their taxable income.
Some businesses may qualify for insurance discounts, grants, or subsidies from professional associations, government programs, or state initiatives. The specifics depend on the type of business and the offers available in your region.
Your local chamber of commerce can help you find business resources and discounts in your area.
Get affordable commercial insurance with Insureon
With Insureon, it's easy to get insured. Fill out our free application to get small business insurance quotes from top-rated providers.
Our licensed agents will help make sure you get the right coverage for your needs at a price you can afford. Once you choose a policy, you buy online and get proof of insurance within 24 hours.
The average costs on this page were derived from our data on 100,000 small business owners who purchased policies through Insureon. Most of our customers have less than five employees, annual revenue ranging from around $50,000 to more than $200,000, and five years or less in business.
Find free quotes for your small business


Want free expert advice right in your inbox?
By entering your email address and subscribing, you agree to our Terms of Use and Privacy Policy