

Business owner’s policy

Business owner’s policy
A business owner’s policy (BOP) bundles general liability insurance with commercial property insurance. It typically costs less than purchasing these policies separately.
What is a business owner's policy (BOP)?
A business owner’s policy combines general liability and commercial property insurance coverage to protect you against lawsuits and damages. In one convenient package, it covers several major lawsuit risks that your small business could face, including those resulting from:
- Third-party bodily injuries
- Third-party property damage
- Product liability incidents
- Advertising and personal injuries
BOPs also provide financial support when your building or commercial property is damaged by an incident the policy covers, typically:
- Fire
- Theft
- Vandalism
- Named weather-related events
Who needs a business owner's policy?
If you own or rent a workspace, you likely need a business owner’s policy (BOP).
Most small businesses need general liability and business property insurance when they rent or own an office or other commercial space. On top of that, client contracts often require general liability coverage.
Even when coverage isn’t required, a BOP is a wise choice for small businesses that work directly with the public and own valuable business property. This policy protects against financial losses from customer accidents and incidents like fires and burglaries.
However, not all businesses qualify for a BOP. For example, if you own a building with both residential and commercial spaces, you may need mixed-use property insurance instead.
To qualify for BOP savings, businesses typically must:
- Do business in a low-risk industry
- Do business outside the owner’s home
- Have fewer than 100 employees
- Have annual sales of less than $1 million
- Do business primarily on site
- Have a relatively small commercial space
What does a business owner's policy cover?
A business owner's policy includes both general liability insurance and commercial property insurance coverage, sometimes called business hazard insurance. Together, they protect your small business against common liability risks, such as slip-and-fall lawsuits, and stolen or damaged business property.
Specifically, a business owner's policy typically covers:

Third-party bodily injuries
If a customer or other third party is injured on your property, the general liability portion of your business owner’s policy can help cover their medical expenses. It can also pay for legal costs if you’re sued over the incident.
Third-party property damage
The general liability portion of a BOP covers accidents that damage or destroy other people’s property. It can also pay for legal fees if a customer sues over the damage.
Product liability
If a business sells, manufactures, or distributes products, it can be sued over the harm those products cause to people or property. Having product liability coverage in a BOP can provide protection from these types of risks, including product defects.
Advertising injuries
If someone sues a business owner or one of their employees over an advertising injury, such as libel, slander, or copyright infringement, the liability portion of a BOP can help pay for lawsuit expenses.
Medical payments
Medical payments coverage is a no-fault feature commonly built into a general liability policy. It’s designed as a form of “goodwill” protection, helping cover minor injuries quickly without requiring a legal claim or lawsuit.
For example, if a customer trips on your front step and sustains a minor injury, this coverage can pay for their medical bills regardless of who was at fault. Coverage limits are typically modest, often around $5,000.
Business property damage
The commercial property insurance portion of a BOP can help pay for repair or replacement of your business property if it's stolen or damaged by fire or some weather-related events.
If you don't have a building, you can add a business personal property (BPP) endorsement to your general liability policy. It provides protection for the items your business owns, such as computers, furniture, and machinery.
How much does a business owner's policy cost?
The average cost of a business owner’s policy is $83 per month. About 25% of Insureon's customers pay less than $50 per month for this policy, however annual premiums can range from around $400 to over $6,000 per year.
The majority of Insureon's customers (79%) choose a BOP with limits of:
- $1 million per-occurrence limit
- $2 million aggregate limit
Your premium depends on the limits and deductible you choose, among other factors.
What factors impact the cost of a business owner's policy?
The cost of a business owner’s policy (BOP) varies based on several factors related to your business’s risk level, property value, and coverage needs. Insurers use this information during underwriting to estimate the likelihood and potential cost of a claim.
Here are the main factors that typically influence BOP premiums:
- Value of your property and equipment: The more valuable your business property is, the more it costs to insure. A business with expensive equipment, inventory, or furnishings will typically pay more for coverage than one with minimal assets. For example, a restaurant with commercial kitchen equipment will likely have higher property coverage costs than a small consulting office with only computers and desks.
- Type of business: Your industry plays a major role in determining risk. Businesses with higher chances of accidents, property damage, or customer injuries usually pay more for a BOP. For instance, a retail store with regular foot traffic may face higher liability exposure than a freelance graphic designer who works from home.
- Business operations: What your business actually does day-to-day can also affect pricing. Operations that involve physical labor, hazardous materials, or work at client sites may increase risk. For example, a contractor who transports tools to jobsites may have greater exposure to theft or property damage than a bookkeeping service that operates entirely online.
- Business location: Where your business is located can impact your premium. Insurers consider risks such as local crime rates, weather patterns, and the likelihood of natural disasters. A business in an area prone to hurricanes, flooding, or high property crime might see higher insurance costs than a similar business in a lower-risk area since they may need to add coverage endorsements.
- Number of employees: Businesses with more employees may face a higher risk of accidents, injuries, or liability claims. As your workforce grows, insurers may adjust your premium to reflect the increased exposure.
- Policy limits and deductible: Higher coverage limits generally mean higher premiums because the insurer could pay more in the event of a claim. Choosing a higher deductible—the amount you pay out of pocket before insurance applies—can sometimes help reduce your premium. On average, Insureon customers pay a deductible of $500 for a BOP.
- Claims history: If your business has filed multiple insurance claims in the past, insurers may view it as a higher risk and charge more for coverage. On the other hand, a clean claims history can sometimes help keep premiums lower.
Together, these factors help insurers determine the overall risk profile of your business and calculate the cost of your BOP.
Verified BOP coverage reviews
Top professions we insure
What does a BOP not cover?
While business owner's policy insurance can help bundle coverage for a variety of business risks, it does not provide all the protection that a small business needs.
Specifically, a BOP will not include coverage for:

Employee injuries
Workers' compensation insurance covers medical expenses, physical therapy, and some lost income for employees who are injured at work. Most states require workers' comp for businesses with employees.
Employee discrimination lawsuits
Employment practices liability insurance (EPLI) can cover legal expenses related to claims of harassment, discrimination, and wrongful termination.
Vehicles used by a business
Commercial auto insurance provides coverage for business vehicles. It’s required in most states when your business owns the vehicle or you use it primarily for work.
Destroyed payment records
If a fire or other incident destroys your customer records, you could have trouble collecting outstanding payments. This is not a covered loss of commercial property insurance, unless your policy has an accounts receivable endorsement.

Workers’ compensation insurance

Professional liability insurance

Commercial auto insurance

Cyber insurance

Commercial umbrella insurance
FAQs about a business owner's policy
Find answers to frequently asked questions about business owner’s policies and other insurance products.
Is it possible to add coverage to a BOP policy?
Yes. Business owner's policies are flexible. You can add on other coverages, called endorsements, to a BOP to meet your specific needs.
Small business owners often bundle their BOP with other types of business insurance policies, such as:
- Business interruption insurance, also called business income insurance, covers loss of income and day-to-day expenses when there is a temporary disruption in your business operations.
- Equipment breakdown insurance covers costs when equipment that your business depends on, such as a refrigerator or freezer, fails and causes a disruption.
- Business renter's insurance is an insurance bundle that covers your rented business space in the event of fire, vandalism, or weather damage. It is similar to renter’s insurance for apartment occupants.
- Tools and equipment insurance, a type of inland marine insurance, covers business property in transit and stored off-site. It can provide protection for a general contractor or handyman who transports tools and equipment to different jobsites.
- Data breach insurance, also known as cyber insurance, helps e-commerce stores and other businesses recover when a data breach exposes email addresses, credit card numbers, or other customer information.
- Electronic data processing (EDP) insurance covers your business's computers, backup systems, and data in the event of a power surge, fire, natural disaster, or similar incident.
- Electronic data liability coverage protects against legal costs related to accidental damage to a client's computer, hard drive, or other data storage equipment. While cyber insurance usually covers data lost from a targeted software attack, electronic data liability insures a data loss when there’s accidental physical damage to a network or storage device.
- Employee dishonesty insurance protects your business from employee theft, such as an employee stealing from the cash register or forging a check.
- Hired and non-owned auto insurance (HNOA) provides coverage for leased, rented, and personal vehicles that a business owner occasionally uses for commercial purposes like visiting clients.
- Liquor liability insurance protects bars and restaurants if they serve alcohol to an intoxicated person who goes on to cause property damage or harm someone else.
- Ordinance or law coverage helps cover the extra costs required to meet current building codes when damaged commercial property needs to be rebuilt.
- Professional liability insurance, also known as errors and omissions insurance (E&O), protects businesses when a client disputes the quality of a professional service.
- Commercial umbrella insurance extends the limits on your general liability coverage and other types of liability policies, meaning your insurance company can cover more expensive lawsuits. You may need it if you serve large clients or run a high-risk business.
What is the difference between general liability coverage and a business owner's policy?
Businesses that interact with the public rely on a general liability policy to cover third-party lawsuits over bodily injuries and property damage. But this insurance doesn’t cover fire, theft, and other incidents that damage or destroy your property.
A business owner’s policy, on the other hand, provides this same general liability coverage and also pays for theft and damage to your building, equipment, and inventory.
If you have a physical location, consider a business owner's policy. A BOP offers both general liability and commercial property coverage at a lower cost than buying the policies separately. That makes it a smart choice for small business owners.
Learn more about the difference between general liability insurance and a BOP.
What is the difference between a business owner's policy and a commercial package policy?
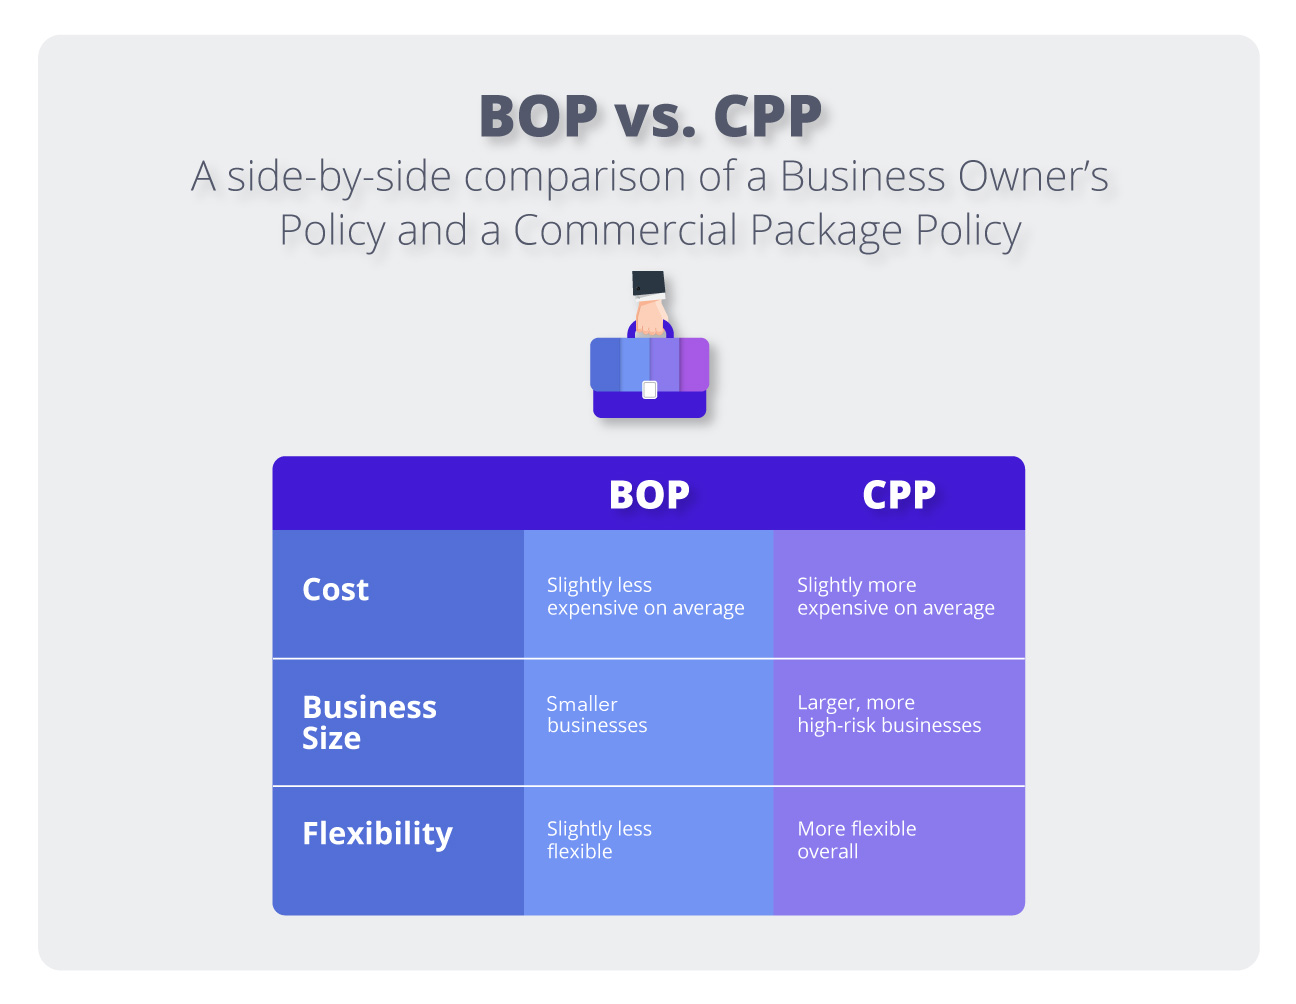
A business owner’s policy combines general liability insurance and commercial property insurance in one policy, and it's usually less expensive than buying the coverages separately. It’s often purchased by small business owners and startups to save money on their liability insurance.
A commercial package policy (CPP) is typically purchased by larger businesses with higher risks, including small or midsize businesses with several employees. A CPP allows you to bundle multiple liability policies together, with more flexibility in terms of the risks covered and their coverage limits.
It also allows you to add endorsements, sometimes called as riders, to increase or modify the types of coverage you have and tailor them to your specific insurance needs.
With an average premium of $117 per month, a CPP tends to be slightly more expensive than a BOP. The exact cost will depend on several factors, including your industry risks.
Learn more about the difference between a business owner's policy and a commercial package policy.
How do you get proof of insurance?
Business owners can usually get proof of insurance on the same day that they apply for insurance quotes with Insureon.
It can take several weeks for a traditional insurance agency to send a certificate of liability insurance to new customers. That’s an issue for business owners who need immediate proof of insurance to sign a lease or get licensed.
With Insureon, you can quickly provide proof of insurance to clients, landlords, and anyone else who requests it. If your bank or lessor requires other proof of insurance, you can contact an agent for assistance.
What are the exclusions on a business owner's policy?
BOPs have some coverage exclusions. For example, a BOP doesn't usually pay for property damage caused by natural disasters like earthquakes, hurricanes, tornadoes, and floods. If you need coverage for these events, you'll need to add a special endorsement to your policy.
A BOP also doesn't pay legal defense costs for lawsuits involving intentional copyright infringement or willful negligence—which can be criminal offenses. Purposeful customer injury or property damage falls into the same category and isn't covered by the policy.
Incidents that involve alcohol are also excluded from a BOP. With a liquor liability endorsement, you can get coverage for these claims.
Check with a licensed insurance agent to make sure your business owner's policy includes all the coverage you need.
Where can I learn more about a BOP?
If you want to learn more about this policy, you can find additional information in our frequently asked questions about business owner's policies.
If you have any other questions or if you'd like help finding the right coverage options for your small business, ask an Insureon agent.