


Cheap errors and omissions (E&O) insurance
Your small business can save money on errors and omissions insurance by avoiding claims and choosing a higher deductible, among other methods. Learn how you can pay less on E&O and still get the protection you need.
How do I find cheap errors and omissions (E&O) insurance?
Errors and omissions insurance (E&O), also known as professional liability insurance or malpractice insurance, is an important policy for small businesses that give professional advice or provide professional services to clients.
E&O coverage protects your business from financial loss in the event that a client claims your mistake or oversight cost them money. This includes paying for defense costs and other legal fees.
Starting at $32 per month, errors and omissions insurance can be affordable for small businesses.
There are many ways for you to keep costs low and avoid more expensive rates. For example, you can compare rates from different insurance companies, such as through Insureon's easy online application that retrieves quotes from trusted carriers.
In addition, bundling your E&O policy with other insurance products, selecting cost-saving options on your errors and omissions insurance coverage, and keeping your claims history clean can also help you pay less.
Table of contents
- Compare E&O insurance quotes
- Bundle E&O with other policies
- How much does errors and omissions insurance cost?
- Customize your E&O policy
- Keep your claims history clean
- Cheapest states to purchase E&O insurance
- Cheapest industries to purchase E&O insurance
- Get E&O insurance quotes with Insureon
- Additional coverages to consider
Compare errors and omissions insurance quotes
Different insurance companies will offer different prices for errors and omissions insurance. Some may even specialize in serving your industry and offer more affordable policies with tailored protection.
You could reach out to insurance companies directly and ask for quotes on their errors and omissions policies. Thankfully, there’s an easier method.
You can work with a digital insurance agency—like Insureon—to get errors and omissions quotes from top-rated providers, such as The Hartford and Chubb, with a single online application.
Insureon's licensed insurance agents can help you navigate different coverage options to find an affordable E&O policy that meets all your needs. Plus, they can ensure the policy you purchase provides the coverage you need to fulfill contracts, meet legal requirements, and reduce risks common to your profession.
You can begin coverage and get a certificate of insurance on the same day.



Bundle E&O insurance with other policies
Insurance companies often give discounts when you bundle multiple policies together. This includes your errors and omissions policy.
Tech and IT companies can often combine their E&O coverage and cyber insurance in a bundle called technology errors and omissions insurance, or tech E&O.
A tech E&O policy provides liability coverage related to:
- Oversights and mistakes
- Failure to deliver promised IT services
- Accusations of professional negligence
- Third-party cyber insurance (data breach lawsuits)
- Intellectual property and media liability (for certain professions)
Learn more about the types of claims tech E&O insurance covers.
How much does errors and omissions insurance cost?
The average cost of errors and omissions insurance for Insureon's customers is $88 per month.
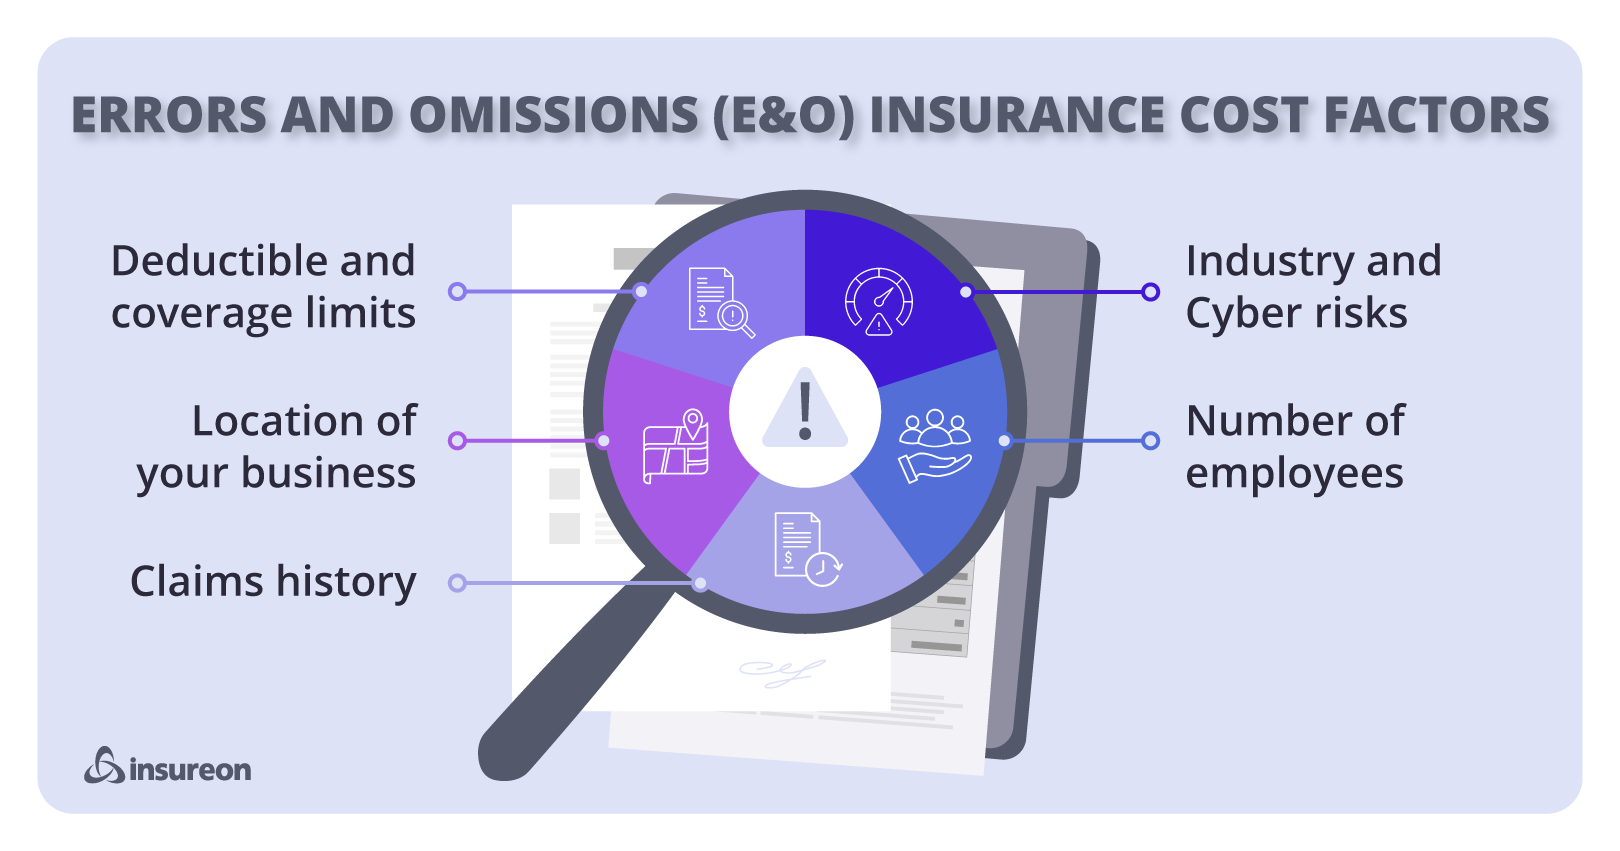
Your premium is based on several factors, including:
- Coverage limits
- Claims history
- Industry risk factors
- Business size
- Day-to-day operations
- Number of employees
Verified errors and omissions coverage reviews
Customize your E&O policy to reduce costs in the long-term
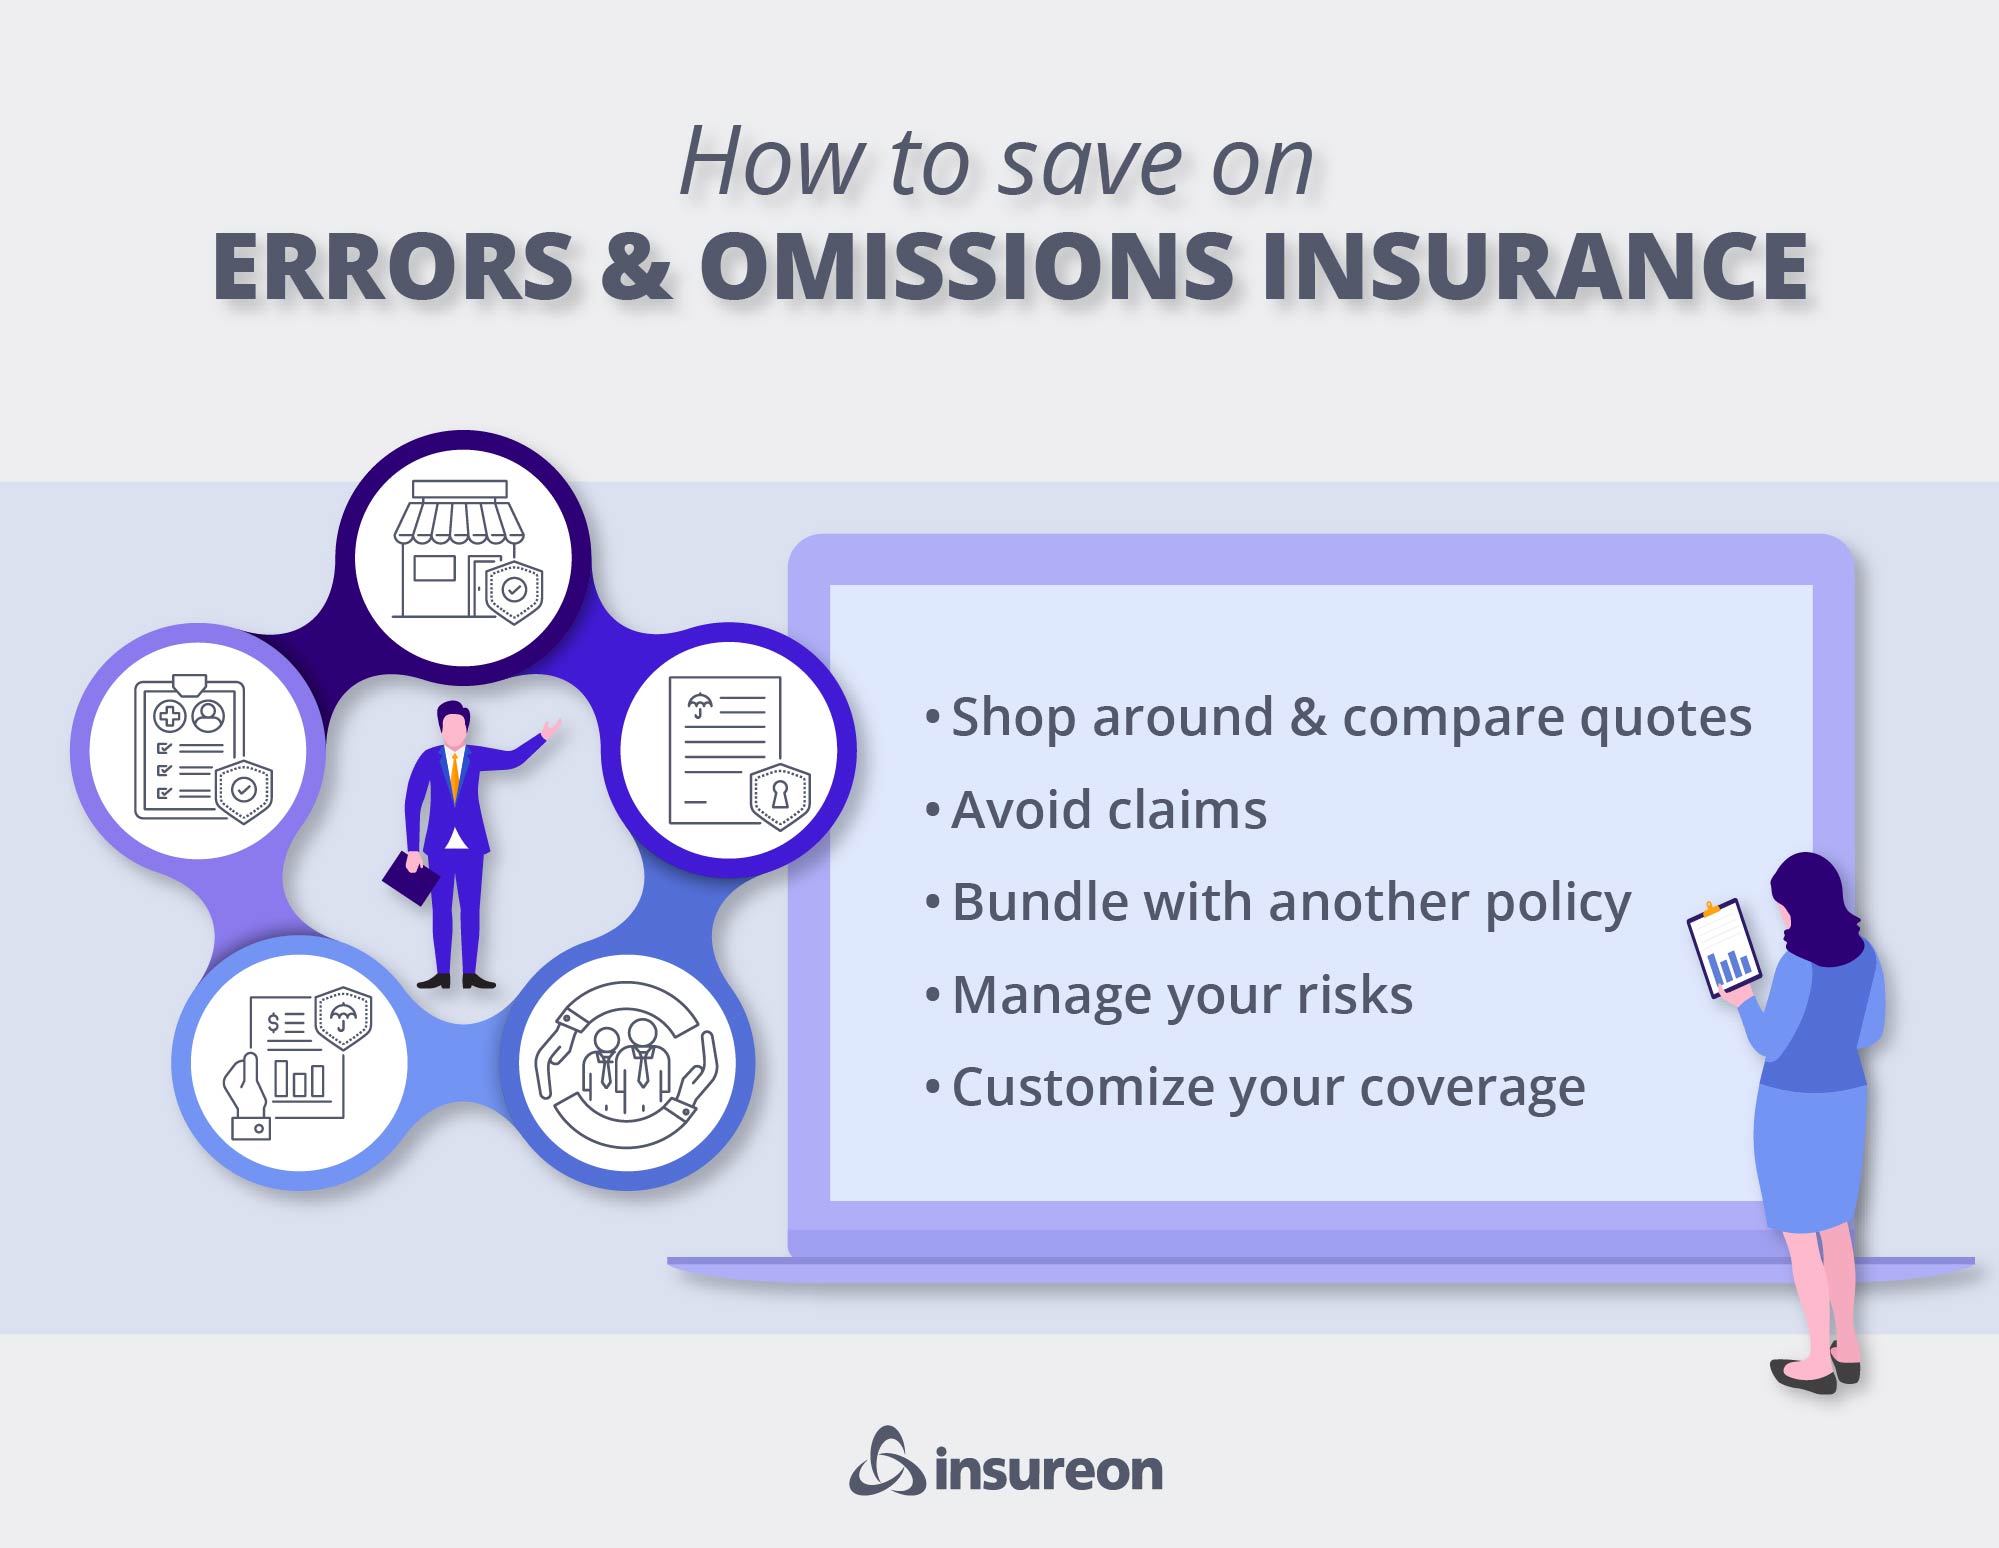
Even though most errors & omissions policies provide similar coverage, you can customize your policies in unique ways to save more money.
This includes:
Choose a higher deductible
A deductible is the amount of money you must pay toward a claim before your insurance benefits kick in. Say an E&O lawsuit costs a total of $50,000 and your deductible is $5,000. The insurance policy will cover $45,000, after you have paid the $5,000 deductible.
When it comes time to choose an insurance policy, the deductible should be an important factor in your decision. In general, higher deductibles mean lower premiums. The trade-off is that in the event of a claim, your business is responsible for paying a larger share up front.
A higher deductible might be worth it if you're mostly concerned about unlikely but very expensive claims.
If a claim does occur, the amount you pay towards the deductible might be insignificant compared to what the insurance policy covers. On the other hand, smaller losses that are less than your deductible may not be covered at all under the policy.
You can choose to pay your insurance premiums once a year rather than on a monthly billing cycle. While making a smaller payment each month requires less money upfront, it often costs more since insurers often offer discounts to businesses that pay an annual premium.
Keep continuous coverage
While it’s possible to purchase errors and omissions coverage when you start a project and drop coverage when you complete the project, this cost-cutting strategy can backfire.
To collect insurance benefits, your “claims-made” E&O policy must be active:
- When an alleged mistake occurs
- When the claim is filed
In short, continuous coverage is key if you don't want to pay out of pocket for E&O lawsuits.
Keep your claims history clean
As with auto insurance, a claim on your E&O policy can cause your premium to go up. Insurance companies may also be reluctant to insure a business with a lengthy record of claims, unless that business is willing to pay more.
Fortunately, you can take steps to reduce the likelihood of an E&O claim. Errors and omissions claims often arise from disagreements with clients. Clear communication, detailed contracts, and other measures can help you and your clients stay on the same track.
By keeping your claims history clean, you will reduce your losses. Having direct and straightforward conversations with clients, while also maintaining other controls, can help prevent potential losses.
Cheapest states to purchase errors and omissions insurance
| State | E&O insurance cost |
|---|---|
$72 per month | |
$69 per month | |
$70 per month | |
$71 per month | |
$71 per month | |
$67 per month | |
$70 per month | |
$70 per month | |
$71 per month | |
$71 per month |
Cheapest industries to purchase errors and omissions insurance
In addition to your location, your industry can affect how much you pay for an E&O insurance policy. Generally speaking, industries that face greater consequences if a mistake or negligence occurs can expect to pay a higher premium.
For example, an architect who is responsible for building a new high rise will likely pay more for their errors and omissions insurance coverage than a photographer who takes family pictures.
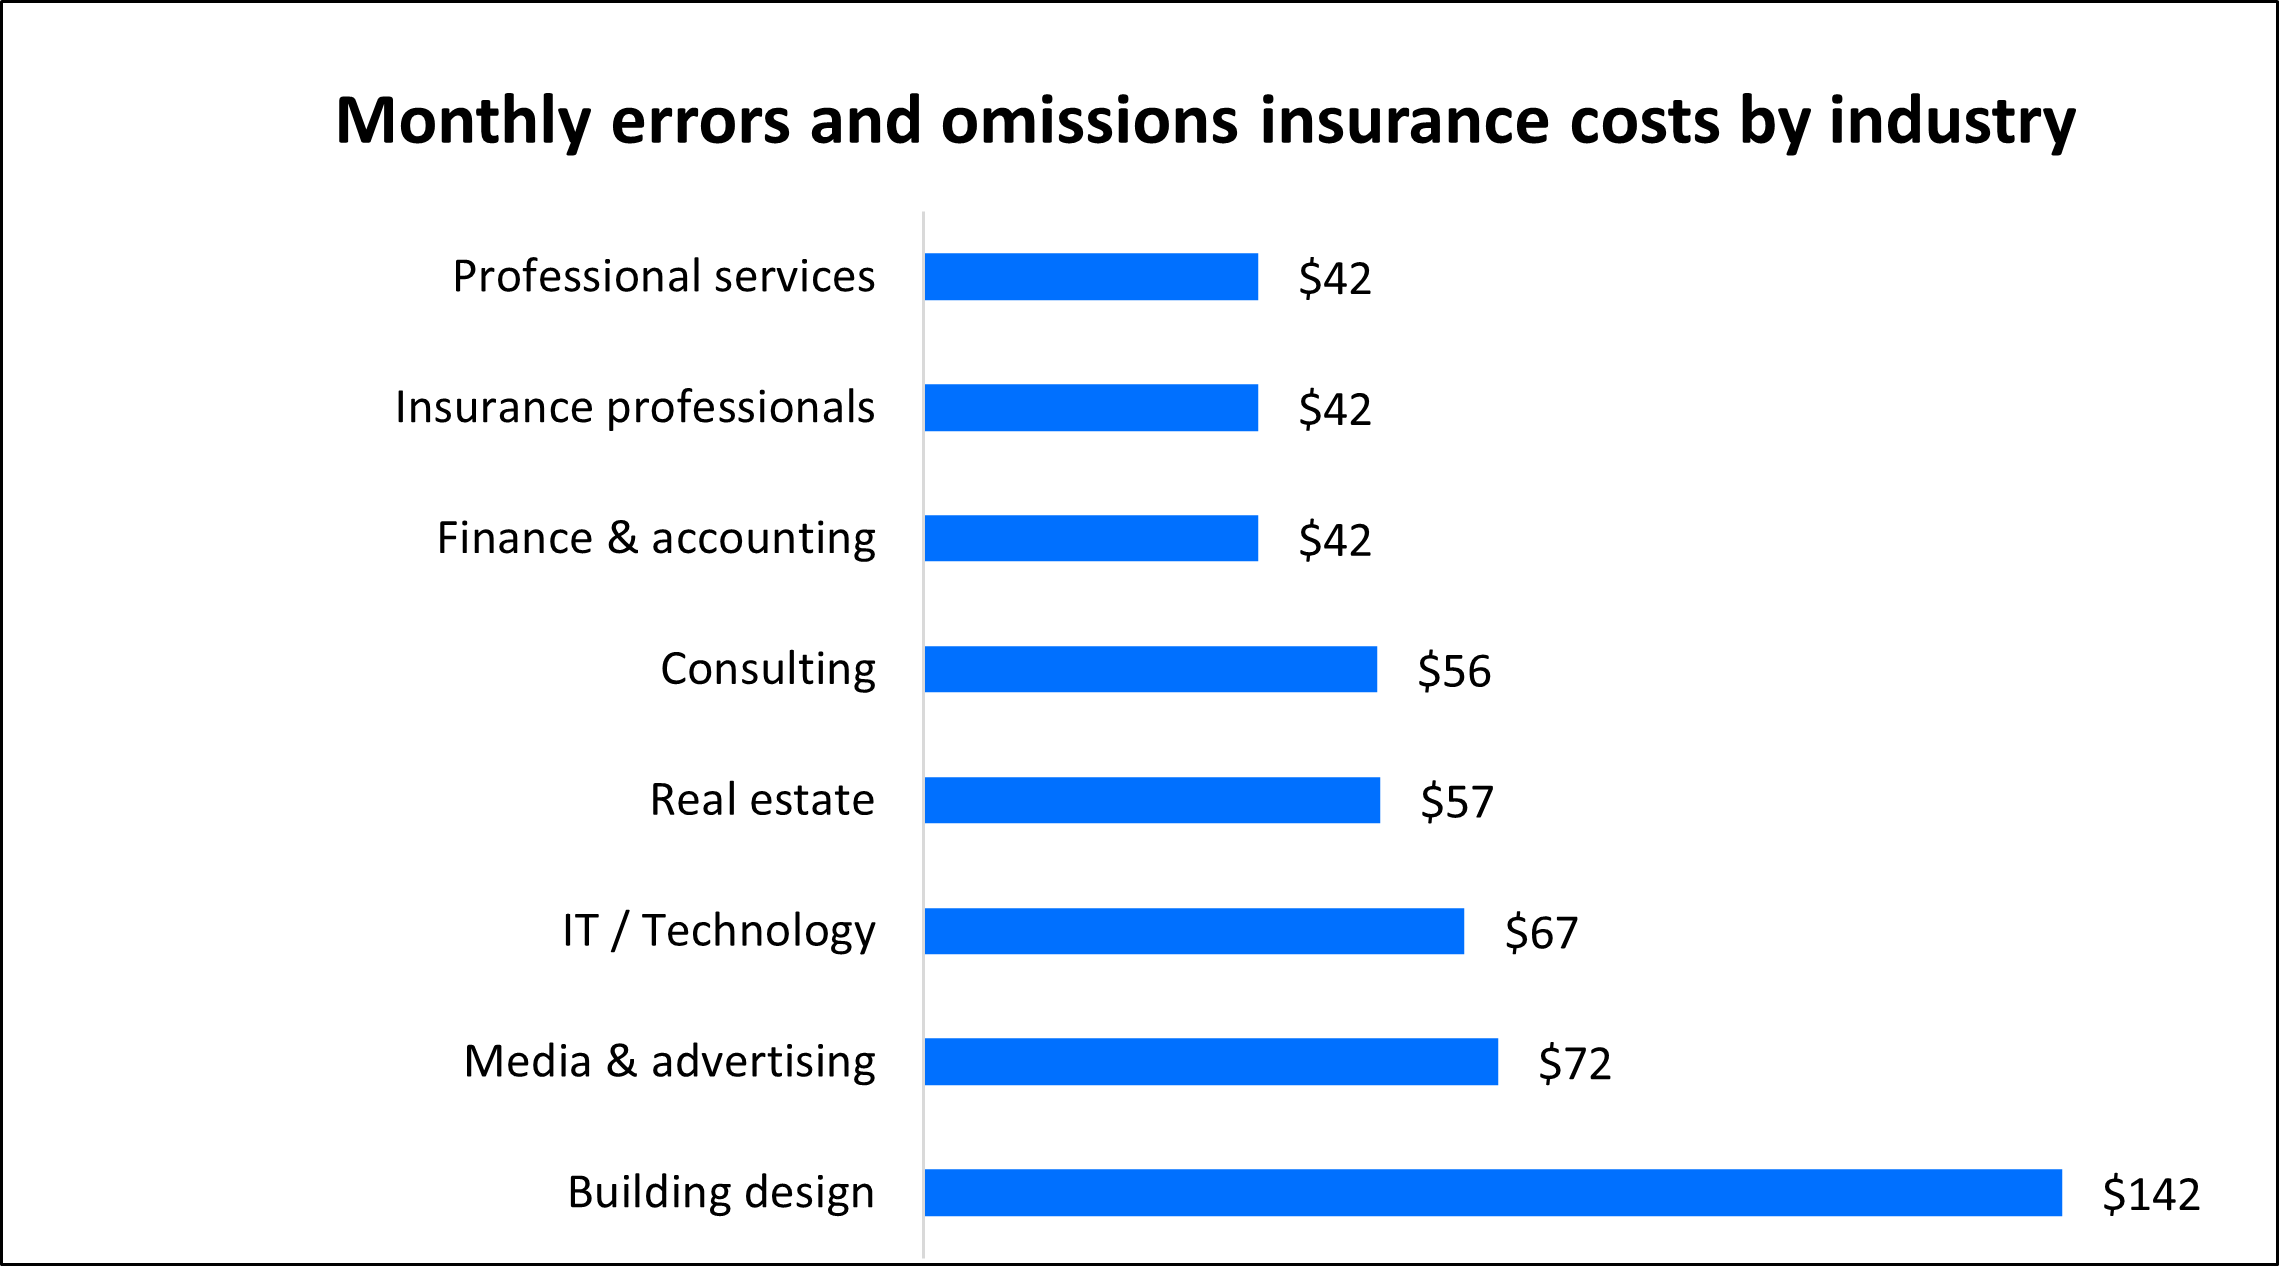
Among Insureon policyholders, industries such as professional services, insurance, and finance and accounting tend to pay less compared to higher risk industries like building design and media and advertising.
Here's a look at errors and omissions insurance costs for different types of businesses:
Top professions that need E&O insurance
How to get E&O insurance quotes from trusted carriers with Insureon
Complete Insureon’s easy online application today to find affordable errors and omissions insurance coverage from top-rated U.S. companies.
At any point while completing our application, you can consult with an insurance agent on your business insurance needs, such as any endorsements you should consider adding to your E&O insurance policy or how to find affordable workers’ comp and commercial auto policies.
Once you find the right types of insurance for your small business, you can begin coverage and receive your certificate of insurance in less than 24 hours.

General liability insurance

Business owner’s policy

Workers’ compensation insurance

Cyber insurance

Commercial auto insurance
The average costs on this page were derived from our data on 100,000 small business owners who purchased policies through Insureon. At least 5 percent of our customers pay as much or less than $22 per month for errors and omissions coverage.
Most of our customers have less than five employees, annual revenue ranging from less than $50,000 to more than $200,000, and five years or less in business.