

Inland marine vs. builders risk insurance
What’s the difference between inland marine and builder's risk insurance?
Builder's risk and inland marine insurance are closely related forms of property coverage, but they protect different assets and exposures:
- Inland marine insurance is a broader category of policies that cover property being transported or stored off-site, but would not assist with the costs related to construction or damaged client property that occurs during the course of construction.
- Builder's risk protects construction projects, including business supplies, materials, and buildings being actively worked on, but likely won't extend to company property that is damaged or stolen while being stored or transported away from the construction site.
General contractors and other construction professionals who work on jobsites often purchase both policies. However, there are key differences between them.
Here’s a closer look at each type of insurance coverage:
What is inland marine insurance?
Inland marine insurance (also called tools and equipment insurance in the construction industry) covers your business property while in transit over land or when it's stored off-site, including equipment, tools, and products transported to and from job sites.
Unlike a traditional commercial property policy that protects your property at a fixed location, inland marine insurance is a "floater" policy that follows your property while away from your business location.
There are a few types of inland marine insurance in addition to the standard policy, including:
- Bailee insurance, which insures property that is not owned by your business but is temporarily in your care.
- Installation floater insurance, which protects against damaged materials being transported or stored at a jobsite.
Despite how the name sounds, inland marine insurance has nothing to do with the sea. The name refers to the fact that it covers a range of policies related to financial losses during land transportation, while ocean marine insurance covers losses related to water transportation.
What is builder's risk insurance?
Builder's risk insurance, also called course of construction insurance, is a type of inland marine coverage that covers physical losses and physical damage to the building under construction and materials due to:
- Non-severe weather events, including wind, rain, and hail, that cause physical damage
- A fire at a construction site that damages or destroys property
- Vandalism that sets a project back by months
- Theft of equipment, materials, and tools left at a construction site
Builder's risk is often purchased as a short-term risk management measure to help construction businesses avoid expensive mistakes or accidents that can occur during the course of construction. Many clients will request a builder's risk policy to be purchased before signing a contract and starting a new project.
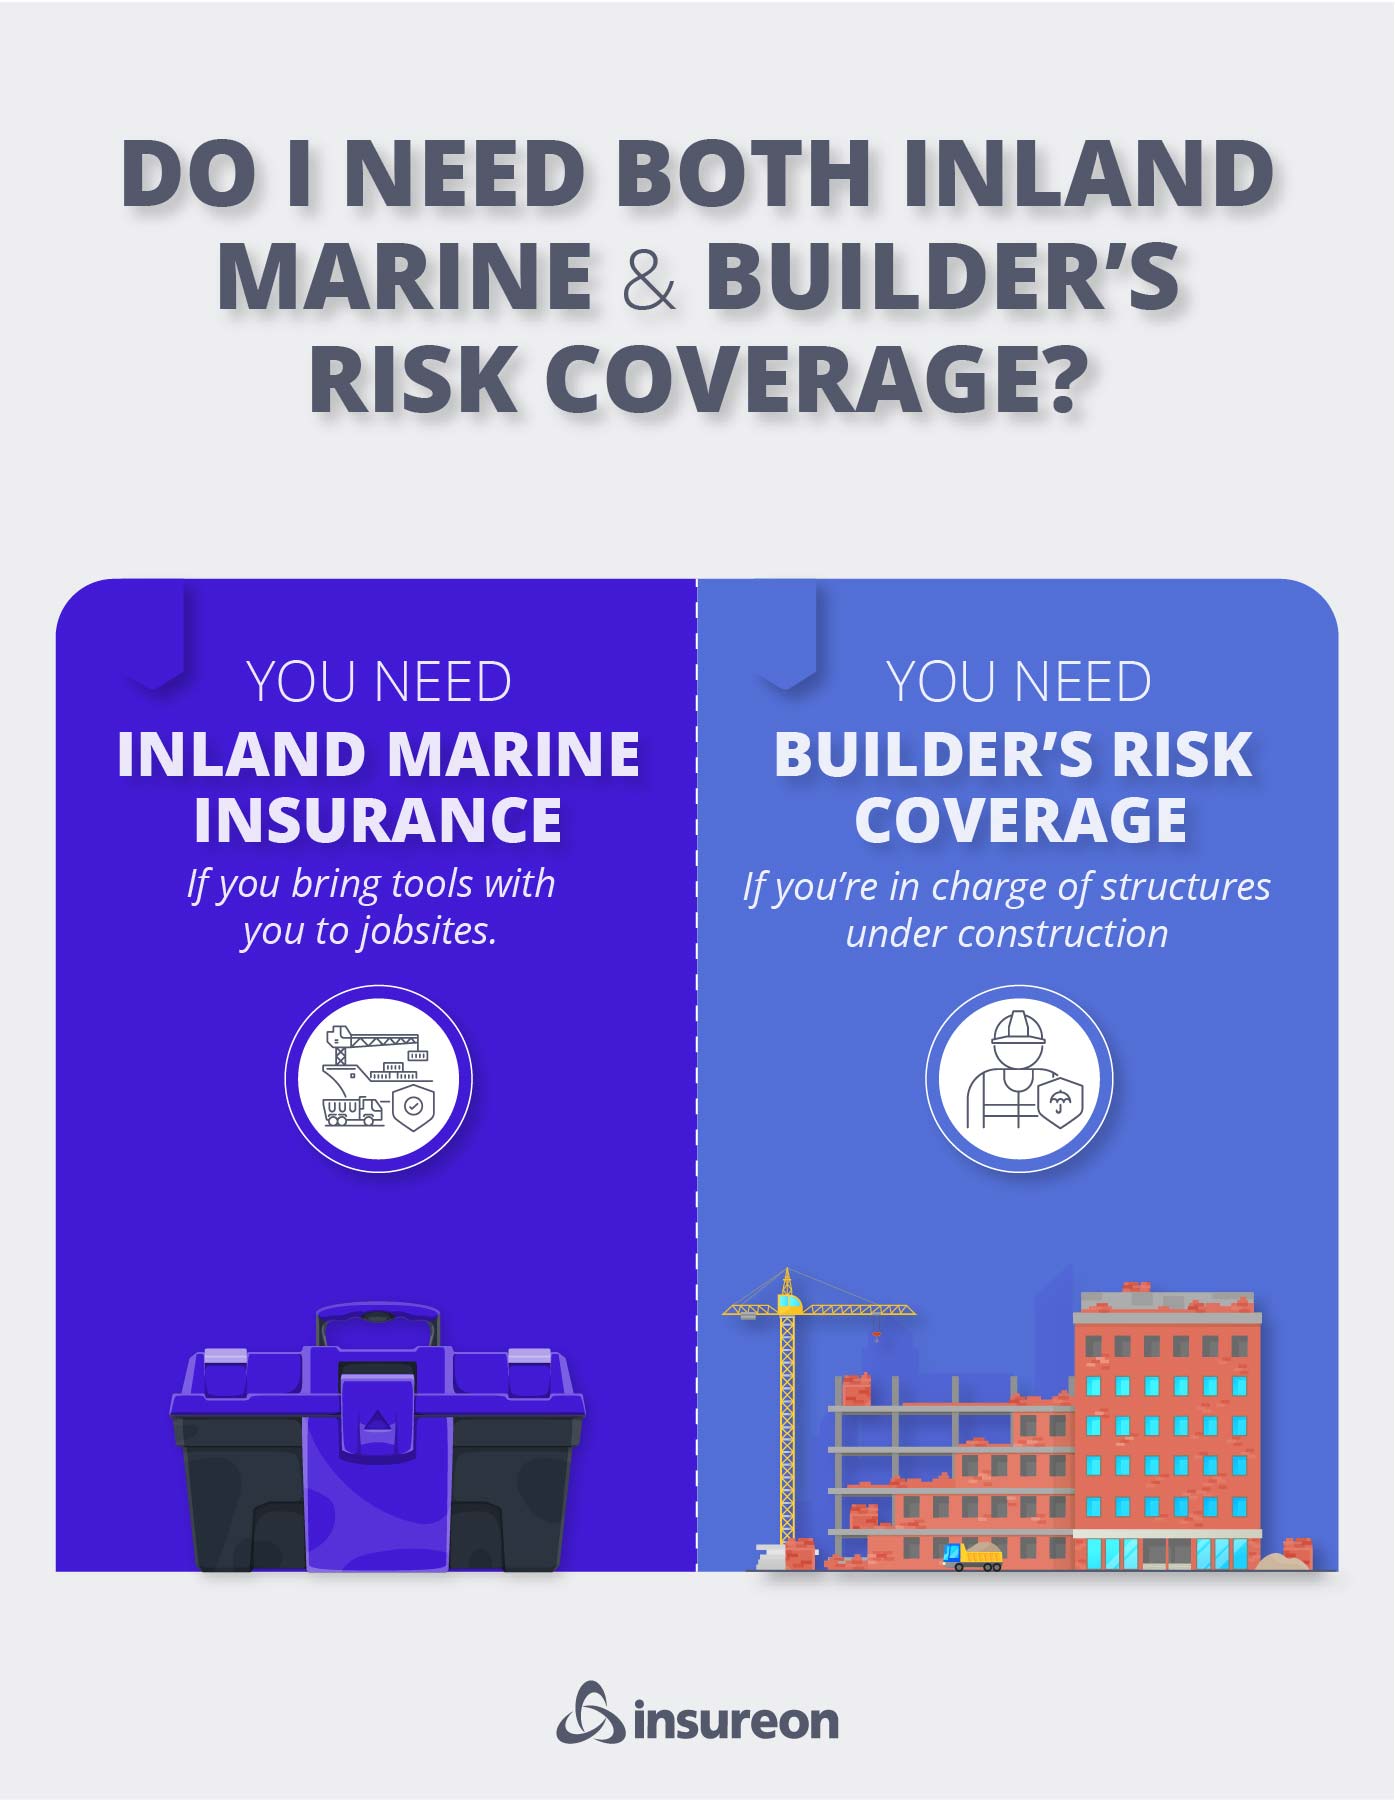
Do you need both inland marine insurance and builder's risk insurance?
You may need both policies depending on your business needs, client requests, and exposures.
For example, if you frequently transport or store business property when not specifically performing construction projects, you may only need an inland marine policy.
Inland marine policies are relevant to non-construction businesses, such as photographers, food trucks, and IT consultants who often transport expensive property but do not perform construction.
You may only need a builder’s risk policy if you use and store equipment and building materials at construction jobsites. However, builder’s risk coverage generally does not protect your property while it’s being transported to or from a jobsite, so you may need inland marine insurance for those exposures.
If you work in construction and frequently transport costly property, you should strongly consider carrying both policies to ensure your business is fully protected from costly property damage while away from your commercial property.
Additionally, clients, subcontractors, building owners, or commercial builders may require one or both policies before signing a contract.
Top professions that need small business insurance
Protect your business with the right insurance policies with Insureon
With one easy online application, Insureon can help you find quotes from the U.S.'s leading insurance companies.
If you have questions about your insurance coverage, you can speak to our licensed insurance agents, who are knowledgeable about the best policies for the construction industry and beyond.
In addition to inland marine and builder's risk coverage, you can also discuss other important policies, such as general liability insurance and commercial property insurance, for protecting your business, clients, and employees.
Once you find the right liability coverage for your unique business operations, you can start your insurance policy and obtain a certificate of insurance (COI), often within 24 hours.

Verified business insurance reviews
Hear from customers like you who purchased small business insurance.
Find the right coverage for your business



Want free expert advice right in your inbox?
By entering your email address and subscribing, you agree to our Terms of Use and Privacy Policy