

Top professional services we insure
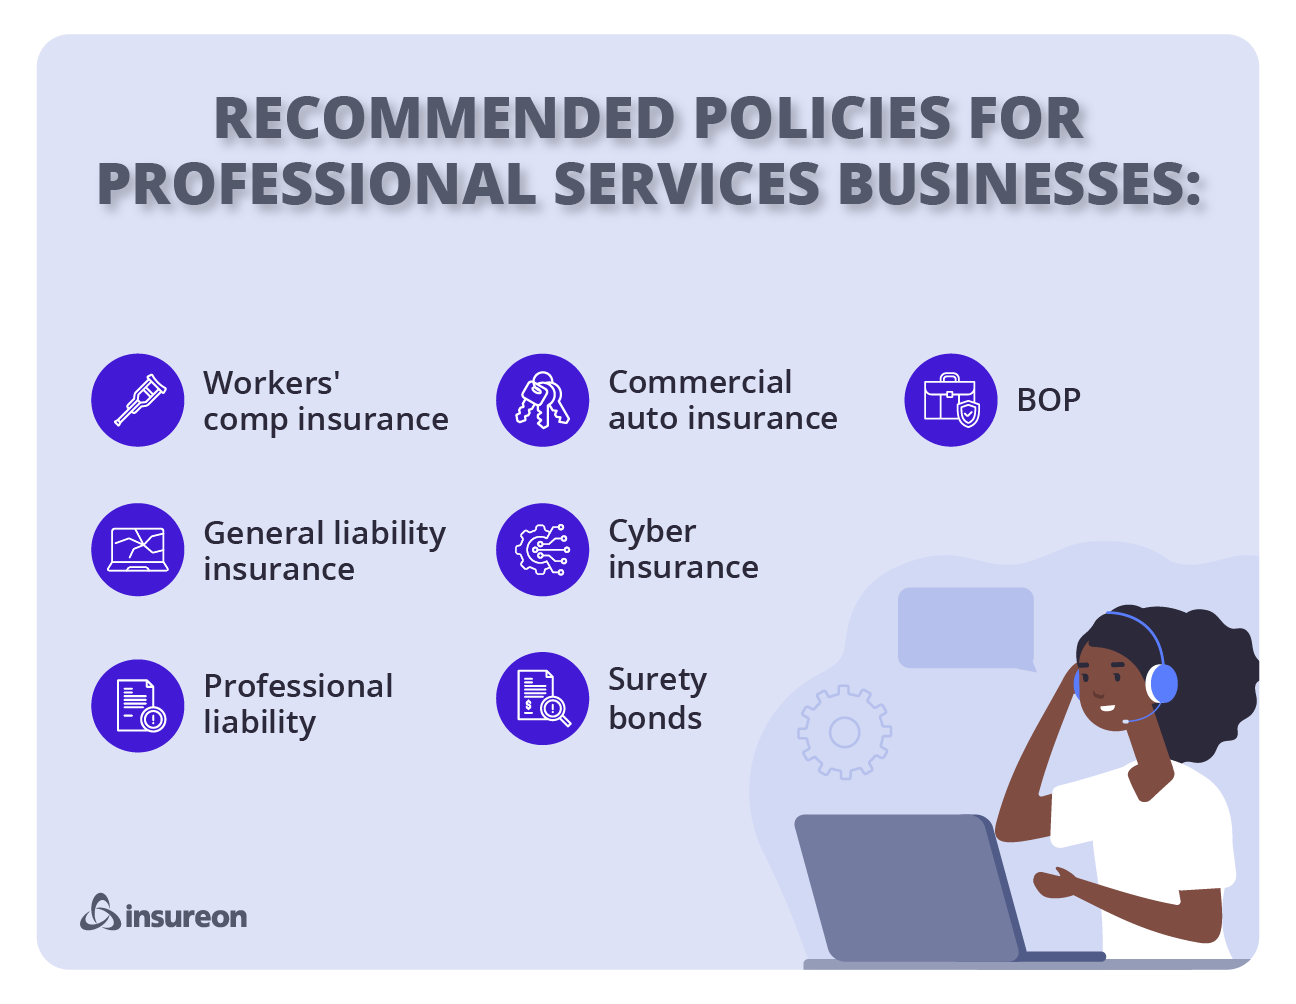
Recommended insurance policies for professional service businesses
From a public speaker accused of slander to a career coach sued for negligence, a lawsuit can devastate a small business. Gain protection against legal fees, healthcare bills, and costly repairs with insurance for professional services.

Business owner’s policy
A BOP is a type of professional services insurance that bundles general liability coverage and commercial property insurance at a lower rate than if they were purchased separately.
- Customer injuries
- Damaged customer property
- Damaged business property

General liability insurance
This policy covers basic business risks, such as client property damage and injuries. Bundle it with commercial property insurance for savings in a business owner’s policy.
- Customer injuries
- Customer property damage
- Libel and slander lawsuits

Professional liability insurance
Also called errors and omissions insurance, professional liability coverage includes legal defense costs if a public speaker or other professional is sued for unsatisfactory work.
- Professional mistakes
- Accusations of negligence
- Failure to deliver promised services

Workers’ compensation insurance
Most states require workers' comp for professional service businesses that have employees. It also protects sole proprietors from work injury costs that health insurance might deny.
- Employee medical expenses
- Partial missed wages
- Lawsuits over employee injuries

Commercial auto insurance
Commercial auto insurance covers financial losses when a professional services vehicle is involved in an accident. It's required for vehicles registered to a business.
- Property damage caused by your vehicle
- Medical payments from auto accidents
- Theft of a commercial vehicle

Cyber insurance
Also called cyber liability, it helps businesses recover from cyberattacks and data breaches. It's strongly recommended for businesses that handle sensitive information.
- Customer notification costs
- Fraud monitoring services
- Data breach investigations
How much does insurance cost for professional service businesses?
Insurance companies look at several factors to calculate insurance costs for professional services, including:
- Your specialty, such as consulting, executive coaching, or public speaking
- Business equipment and property
- Annual business revenue
- Location, such as your home or a commercial building
- Number of employees
- Coverage limits, endorsements, deductibles, and exclusions
- Claims history
How do I get business insurance for professional services?
It’s easy to find insurance solutions for your type of business. Whether you’re a career coach, event planner, notary, or tutor, you’ll need to have some basic information about your business available.
Our application will ask you for your annual revenue and payroll, among other details. You can buy a policy online and get a certificate of insurance with Insureon in three easy steps:
- Complete a free online application
- Compare free quotes and choose a policy
- Pay for your policy and download a certificate for proof of insurance
Insureon's licensed insurance agents work with top-rated U.S. providers to find the right insurance coverage to complete your risk management plan and meet your business needs, whether you work-from-home as a virtual assistant, work on a small team of real estate agents, or run a medical billing company with multiple employees.
Verified business insurance reviews
Hear from customers like you who purchased small business insurance.
FAQs about professional services insurance
Are lawyers and other service professionals required to carry insurance?
While not all attorneys and other service providers are mandated to carry insurance, some states and cities have professional liability coverage requirements, such as a legal malpractice insurance. This policy is also referred to as professional liability insurance coverage, errors and omissions (E&O) insurance, or indemnity insurance.
Regardless of state requirements, any business that offers professional services or advice should carry insurance coverage to protect against financial costs related to errors and oversights, third-party bodily injury and property damage, theft, and copyright infringement.
What other insurance coverage do professional service businesses need?
To fully protect your professional service business from complex risks and exposures, you may need additional types of coverage, including:
- Business income coverage, also called business interruption insurance, compensates small business owners for their normal operating expenses and other associated costs if a fire or other commercial property insurance claim forces your management consultant practice to temporarily close its doors.
- Extra expense coverage pays for expenses above and beyond a business's normal operating costs after a disruptive event. You can get this coverage as a standalone policy, as a rider to commercial property insurance, in a package with business interruption insurance, or as part of a business owner's policy.
- Employment practices liability insurance (EPLI) protects your small business if an employee sues over wrongful termination, sexual harassment, or another violation of employee rights.
- Directors and officers (D&O) insurance, often combined with EPL insurance in a management liability insurance bundle, covers claims related to decisions made by your board of directors, as well as officers elected or appointed by the board, during the policy period after the retroactive date.
- Commercial crime insurance, also referred to as fidelity insurance, financially protects your business from criminal acts committed by employees against customers or clients.
- Surety bonds act as a contract between a business, a client, and an insurance company. They guarantee the surety company will reimburse the client if the business fails to deliver contracted services. It's important to note that bonds must be paid back to the surety company.
- Equipment breakdown coverage protects your company's computers, electrical systems, production machinery, and other equipment from sudden and accidental malfunctions that commercial property insurance typically excludes.
- Commercial umbrella insurance provides additional coverage for liability claims made on general liability, commercial auto, or employer’s liability insurance.
Get professional services insurance quotes
Read our blog posts


Want free expert advice right in your inbox?
By entering your email address and subscribing, you agree to our Terms of Use and Privacy Policy