

Workers' compensation insurance for real estate businesses
Workers’ compensation insurance covers medical expenses and lost wages for employees who suffer a work-related injury or illness. For real estate businesses, this can include injuries that occur while showing properties, meeting clients, traveling for work, or performing office duties. Most states require businesses with employees to carry workers’ comp coverage.
Workers' compensation protects employees at your real estate office
Whether at the office or on-site at a property, your employees are susceptible to work-related injuries. The cause could be as simple as moving heavy furniture or tripping on an uneven step. Even a minor injury can result in medical bills and time taken off work.
Workers’ compensation insurance provides coverage in three primary areas:
- Employee medical expenses
- Employee injury lawsuits
- Compliance with state laws
How does workers' compensation benefit employees of a real estate business?
A workers' compensation insurance policy provides important financial support for real estate sales agents or other professionals who are injured or become ill because of their work.
It can help pay for medical expenses related to a work injury, including emergency treatment, hospital visits, and ongoing care such as physical therapy.
If an employee is unable to work while recovering, workers' comp can also provide disability benefits and replace a portion of their lost wages. In the event of a fatal workplace accident, the policy may provide death benefits to the employee's family.
Do real estate business owners need workers' compensation insurance?
Whether real estate business owners need workers' compensation insurance depends on state law and how the business is structured. Even when coverage isn't required, it can provide valuable financial protection.
Personal health insurance may not cover injuries that occur while performing work-related duties, leaving business owners responsible for medical expenses out of pocket. Workers' compensation can help cover those costs, along with a portion of lost income if a real estate broker is unable to work while recovering from a covered injury.
Most workers' compensation policies also include employer’s liability insurance, which can help protect a real estate business if an employee files a lawsuit over a work-related injury or illness. This coverage can help pay for attorney fees, court costs, settlements, and judgments, reducing the financial impact of a costly legal claim.
For example, an employee could file a lawsuit after being injured while setting up an open house or showing a property if they believe unsafe working conditions contributed to the accident.
State laws set workers' compensation requirements for real estate businesses
In most states, real estate businesses must provide workers’ compensation insurance as soon as they hire their first employee. Without this policy, you could face fines, payments to a state uninsured employers fund, or even jail time.
Each state has its own laws for workers’ compensation requirements. For example, every real estate business in New York must carry workers’ compensation for its employees—even part-time workers. However, Alabama businesses are only required to carry workers’ compensation when they have five or more employees.
Sole proprietors, independent contractors, and partners don’t have to carry workers’ compensation insurance or remain self-insured, but you can purchase a policy to protect yourself, too. It's a good idea to carry this coverage, as health insurance providers can deny claims related to your job.
Workers' compensation laws in your state
Monopolistic state funds for workers’ compensation
In certain states, real estate businesses must purchase coverage through a monopolistic workers' comp state fund. Those states are:
If you purchase workers’ comp through a monopolistic state fund, it might not include employer’s liability insurance. However, you can purchase it as stop gap coverage from a private insurance company.
Top real estate professionals we insure
How much does workers’ compensation insurance for real estate professionals cost?
A small real estate firm with only a few realtors on staff will pay less for coverage than a large brokerage with several brokers and support staff.
The average cost of workers' compensation insurance for real estate businesses is $51 per month. However, you could pay more or less depending on your unique risks.
Underwriters will look at several factors when determining your premium, including the services you provide, any risks associated with your firm, and the amount of coverage you need.
How are real estate workers' compensation insurance costs calculated?
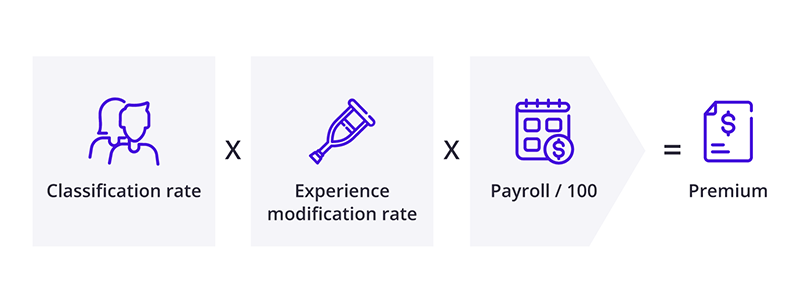
The amount you pay for workers’ compensation is a specific rate based on every $100 of your business’s payroll. Your workers' comp premium is determined by the type of work done by your employees (classification rate), your experience modification rate (claims history), and your payroll (per $100).
The formula providers use in underwriting to calculate workers' comp rates is:
Several factors can influence how much a real estate business pays for workers' comp insurance, including:
- Real estate services offered: Businesses that manage properties, supervise maintenance staff, or support large teams of real estate salespersons may face different risks than firms focused primarily on office-based administrative work. The type of services provided can affect the likelihood of workplace injuries and influence insurance costs.
- Business equipment and property: Real estate professionals who regularly transport signs, staging materials, marketing displays, or other equipment may have greater exposure to lifting, carrying, and setup-related injuries, which can impact premiums.
- Annual payroll and revenue: Workers' compensation premiums are typically based on payroll, so businesses with higher payroll costs often pay more for coverage. Revenue and commissions may also be considered as an indicator of business size and overall risk exposure.
- Number of employees: A larger workforce generally increases the likelihood of workplace accidents and workers' compensation claims, which can affect the overall cost of coverage.
- Location: Workers' compensation laws, medical costs, and claim trends vary by state. Businesses operating in areas with higher claim costs or stricter requirements may pay higher premiums.
- Claims history: Real estate businesses with a history of workplace injuries and filing claims often pay higher rates than those with fewer claims.
- Workplace safety and risk management practices: Insurers may offer more favorable rates to businesses that provide safety training, implement injury prevention programs, and establish procedures for activities such as property showings, travel, and open house setup.
Lower workers' comp costs with risk management
Even office workers are at risk for an injury. They could slip on a wet floor or trip over a power cord. If an employee is injured on the job, it could lead to an insurance claim and a rise in your premiums.
Business owners can mitigate risks by providing safety training and eliminating hazards such as loose rugs, clutter, and dim lighting. Taking these steps could reduce workplace injuries and help keep your insurance rates low.
Other important policies for real estate professionals
While workers’ compensation protects your employees, and to some extent, your business, it doesn't provide complete protection. Because accidents can happen in any real estate profession, some other policies to consider include:
General liability insurance: A general liability policy covers common business risks like customer injuries, damage to a customer’s property, and advertising injuries.
Commercial umbrella insurance: Umbrella insurance provides additional coverage for liability claims made on your general liability, commercial auto, or employer’s liability insurance, once a policy's limit is reached.
Business owner's policy (BOP): A BOP combines general liability coverage with commercial property insurance, typically at a lower rate than buying the policies separately.
Commercial auto insurance: This policy covers business-owned vehicles. It typically pays for accidents and damages related to theft, weather, and vandalism.
Cyber insurance: Also called cybersecurity insurance, this type of coverage helps real estate businesses survive cyberattacks and data breaches by paying for recovery expenses and other associated costs.
Errors and omissions insurance: Also called professional liability insurance or E&O, this policy can cover legal fees of lawsuits related to a real estate professional's business decisions.
Lessor's risk only (LRO) insurance: This policy protects commercial landlords from tenant lawsuits over property damage and injuries.
Surety bonds: Real estate professionals sometimes need a surety bond to get licensed in their state. It acts as a financial guarantee they'll comply with contract terms and regulations.
Get free workers' comp quotes and buy online with Insureon
Are you ready to safeguard your real estate business with workers' compensation insurance?
Simply complete Insureon’s easy online application today. We partner with top-rated U.S. insurance companies to get you the best workers' comp insurance. You can also consult with an insurance agent on the types of business insurance you need, and how to get affordable workers' compensation coverage within your budget.
Once you find a policy that fits your needs, you can begin coverage and access your certificate of insurance (COI) in less than 24 hours.
Verified workers' compensation insurance reviews
The average costs on this page were derived from our data on small business owners in the real estate field who purchased policies through Insureon. Most of our customers have less than five employees, annual revenue ranging from around $50,000 to more than $200,000, and five years or less in business.
Find workers’ comp insurance quotes



Want free expert advice right in your inbox?
By entering your email address and subscribing, you agree to our Terms of Use and Privacy Policy