

Utah workers' compensation insurance
Almost all Utah employers are required to carry workers’ compensation insurance. This policy helps pay for medical treatment and provides partial lost wages when employees are injured on the job.
Who needs workers’ compensation insurance in Utah?
Utah state law mandates strict workers’ compensation insurance coverage for employers. With just a few exceptions, every Utah company that hires employees must provide workers’ compensation insurance.
Once you hire even one employee, you must provide workers’ comp insurance to that worker and all future employees. Only a few categories of workers are exempt:
- Some agricultural employees
- Casual or domestic employees
- Some real estate and insurance brokers
A business can elect to exclude some or all of its corporate officers and directors from workers’ comp insurance. However, it must first file notice with its workers’ comp insurer and file for an exemption with the State of Utah Labor Commission.
Who is exempt from Utah workers’ compensation insurance?
Most employers must provide workers’ comp insurance in Utah. However, business owners with no employees, such as sole proprietors, independent contractors, partnerships, and limited liability companies (LLCs), aren’t required to purchase this policy.
Even when it's not required, buying workers' comp coverage is a smart financial move. Your health insurance company might deny a claim for a workplace injury, which could leave you responsible for costly medical bills.
With just a few exceptions, every Utah company that hires employees must provide workers' compensation insurance.
What does workers' compensation insurance cover for Utah businesses?
Here are several examples of how workers' compensation coverage helps pay expenses for injured workers:
- A fast food worker burns themselves while preparing an order for a customer. Workers' comp would cover their medical bills and pain medication.
- A retail store employee slips on a wet floor and hits their head. In this instance, workers' compensation would cover their emergency room trip, head MRI, and any follow-up visits with their medical provider during their recovery.
- A registered nurse develops a shoulder injury from lifting and turning patients. Workers' comp would cover their surgery, medications, and physical therapy. It also provides temporary disability benefits until they have recovered, including a certain amount of compensation to account for their lost wages.
- A wholesale stocker develops an arm impairment from many years of lifting and moving heavy stock onto pallets and trucks. Workers' comp would cover their medical provider appointment, medications, and then two months of physical therapy to help them recover.
Top industries we insure


What does workers' compensation insurance not cover?
Additionally, here's what your workers' comp insurance policy won't cover:
- Injuries caused by intoxication, drugs, or company policy violations
- Injuries claimed after a firing or layoff
- Wages for a replacement worker
- Occupational Safety and Health Administration (OSHA) fines
How much does workers' compensation insurance cost in Utah?
The average cost of workers’ compensation in Utah is $44 per month, or $526 annually, based on policy data from Insureon customers.
Your workers' compensation premium depends on several factors, such as:
- Payroll
- Location, such as Salt Lake City or West Valley City
- Number of employees
- Industry and risk factors
- Coverage limits
- Claims history
How to buy workers' compensation insurance coverage in Utah
Utah business owners have a few choices when it comes to buying a workers' compensation policy:
- Private insurance companies. You could contact each workers' compensation insurance carrier independently to compare their products and rates, but that's where agents and brokers like Insureon come in. As the nation's leading digital insurance agency, Insureon has access to 100+ top-rated insurance carriers to deliver the right coverage for your business. Fill out an easy online application to get started.
- If denied, you can obtain coverage from the assigned risk pool. If you’re unable to purchase workers’ comp insurance through the voluntary market referenced above because of your firm’s high-risk status, you can buy coverage from the Workers’ Compensation Fund of Utah (WCF). This is Utah’s workers’ comp provider of last resort.
- You can self-insure your business. Utah employers who qualify can also self-insure their workers' compensation claims. This means they’ll pay for their own workers’ comp benefits rather than submit them to an insurance company. In Utah, employees must file a workers’ comp claim to the Industrial Accidents Division within one year from the date of injury or illness.
Verified workers' compensation insurance reviews
Insurance providers use a specific formula for calculating workers' comp premiums: Classification rate x Experience modification rate x (Annual payroll / $100).
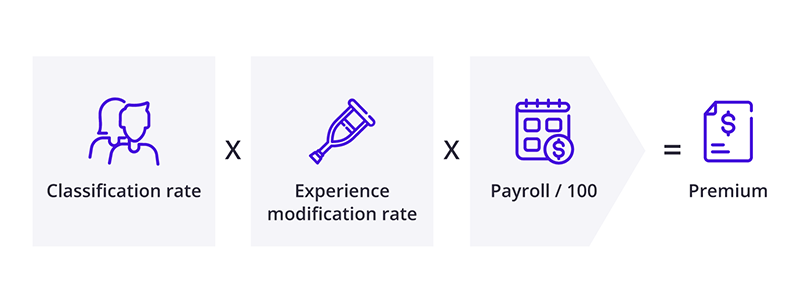
Here's a breakdown of this equation:
- The classification rate reflects your employees' risk. Each worker has a classification code for the type of work they do. Insurers look up those codes in a database to find the associated rate, which is lower for office workers and higher for carpenters, tree trimmers, and others with a higher rate of injuries. Like most other states, Utah relies on the National Council on Compensation Insurance (NCCI) database.
- The experience modification rate (EMR) reflects your business's risk. The average experience modification rate is 1.0, which means a business is similar in risk to others in its profession. Higher EMRs reflect higher risks, such as a history of claims. The EMR only comes into play for annual workers' comp premiums of at least $5,000, so it's not a factor for many small business owners.
- The insurer multiplies these numbers by your payroll divided by 100 to determine your workers' compensation rate. Workers' compensation audits are typically conducted annually to ensure your business pays the correct premium for this coverage.
How can Utah business owners save money on workers' comp?
To save money on workers' comp insurance, it's important to make sure you classify your employees correctly. Employees with desk jobs or other jobs with a low risk of injury cost less to insure. This also helps you avoid misclassification fines.
In some cases, Utah employers can choose to buy pay-as-you-go workers' compensation. This type of workers' comp policy has a low upfront premium, and lets you make payments based on your actual payroll instead of an estimated payroll. It's useful for businesses that hire seasonal help or have fluctuating numbers of employees.
A ghost policy is a cheap option in some states, although it is not permitted in Utah. A ghost policy is a workers' comp policy in name only. It provides no protection or medical benefits, but can fulfill contractual requirements for a workers' comp certificate at a reduced price.
Finally, a documented safety program can help lower workers' comp costs. A safer workplace means fewer accidents, which helps keep your premium low.
How does workers’ compensation work in Utah?
When a worker is injured on the job, workers' comp covers the cost of their medical bills. This business insurance also provides indemnity benefits to help cover the employee's loss of income. In the event of permanent impairment or disability, workers' comp can provide disability compensation for the life of the worker.
Workers' compensation benefits for injured employees in Utah cover:
- Medical expenses for reasonable and necessary medical care related to the injury
- Temporary partial disability benefits
- Temporary total disability benefits
- Permanent partial disability benefits
- Permanent total disability benefits
- Death benefits for a surviving spouse or dependents
Policies usually include employer's liability insurance, which can help cover legal expenses if an employee blames their employer for an injury. The exclusive remedy provision in most workers' comp policies prohibits an employee from suing their employer once they accept workers' comp benefits.
For details, visit the Industrial Accidents Division within the Utah Labor Commission.
What are the penalties for not having workers’ comp insurance in Utah?
The penalties for violating Utah’s workers’ compensation statute can be severe:
- A penalty of at least $1,000
- A legal injunction against doing business in the state
- Loss of the so-called “exclusive remedy,” which protects employers from getting sued for workers’ comp benefits
Workers’ compensation death benefits in Utah
If one of your employees dies as a result of a work-related injury or industrial accident, the person’s dependents are entitled to receive death benefits. These include payments to cover burial and funeral expenses.
Under the Utah Workers' Compensation Act, survivors are entitled to weekly income benefits. This amount, based on whether the deceased worker had dependents and how many, is calculated on the basis of 67% of the employee’s average gross weekly pay.
Workers’ compensation law for settlements in Utah
A workers’ compensation settlement is an agreement between the injured employee, employer, and insurer that terminates a workers’ compensation claim. This benefits both the employee and the employer.
The Utah Labor Commission allows settlements of workers’ comp claims. Utah law requires the commission to approve these agreements, even though all parties have indicated their desire to settle.
There are two kinds of settlement agreements in Utah:
Compromise settlements are used when the parties disagree on whether the sick or injured worker is entitled to receive a workers’ comp benefit.
Commutation settlements are used when everyone agrees the worker should get a workers’ comp benefit.
Get free workers’ comp quotes with Insureon
If you are ready to buy a workers' compensation policy, start a free application with Insureon to compare quotes from top-rated insurance carriers. A licensed insurance agent will help answer your questions and explain your coverage options.
Once you find the right policy, you can usually begin coverage and get your certificate of insurance in less than 24 hours.
Find workers' comp insurance quotes


Want free expert advice right in your inbox?
By entering your email address and subscribing, you agree to our Terms of Use and Privacy Policy