

Get the right commercial insurance for your Washington, D.C. business
Which policies are recommended for Washington, D.C. businesses?
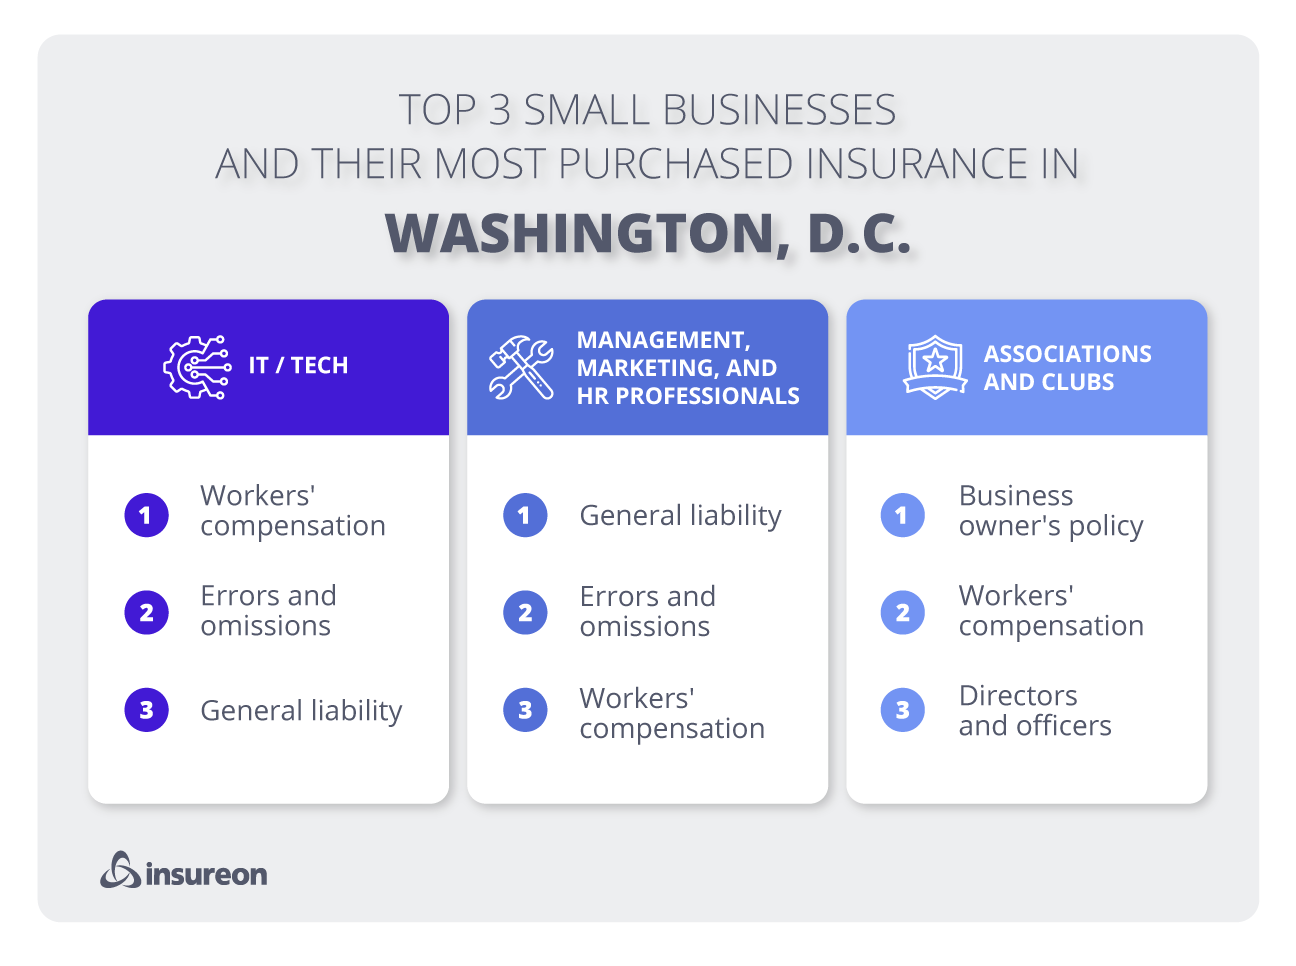
Small businesses in Washington, D.C. often buy these types of insurance.

General liability insurance
This policy is important for all Washington, D.C. businesses. It covers common risks, including customer property damage and injuries. Most commercial leases require this coverage.
- Customer injuries at your business
- Damaged customer property
- Libel and other advertising injuries

Workers’ compensation insurance
Workers’ compensation insurance is required for Washington, D.C. businesses that have one or more employees. It also protects sole proprietors from work injury costs that health insurance might deny.
- Employee medical expenses
- Disability benefits
- Lawsuits from employee injuries

Commercial auto insurance
This policy is required for business-owned vehicles in Washington, D.C. It covers injuries and property damage in an accident, along with vehicle theft and certain types of damage.
- Accidents involving business vehicles
- Theft of a business-owned vehicle
- Damage to a company vehicle

Business owner’s policy
This policy bundles commercial property insurance and general liability coverage. It's often the most cost-effective type of commercial insurance for a business in Washington, D.C.
- Customer injuries
- Damaged customer property
- Damaged business property

Professional liability insurance
This policy, also called errors and omissions insurance (E&O), protects professionals whose work depends on their expertise. It covers lawsuits over mistakes and missed deadlines.
- Work mistakes and oversights
- Professional negligence lawsuits
- Late or incomplete work

Errors and omissions insurance
E&O, sometimes called professional liability insurance, is common with professional services in Washington, D.C. It can cover the cost of lawsuits related to your work performance.
- Missed deadlines
- Accusations of negligence
- Errors and oversights

Cyber insurance
This policy helps Washington, D.C. businesses survive data breaches and cyberattacks by paying for client notification costs, legal fees, and other related expenses.
- Data breach lawsuits
- Client notification expenses
- Fraud monitoring costs

Commercial umbrella insurance
Umbrella insurance boosts coverage on your general liability insurance, commercial auto insurance, and employer's liability insurance when the underlying policy reaches its limit.
- Customer lawsuits
- Auto accident lawsuits
- Employee injury lawsuits

Commercial property insurance
This policy covers the value of a business's physical structure and its contents, such as inventory, equipment, and furniture. Bundle it with general liability coverage in a BOP for savings.
- Fire
- Theft and vandalism
- Weather damage
Verified business insurance reviews
Hear from customers like you who purchased small business insurance.
Which business insurance policies are required in Washington, D.C.?
Regional laws often affect business insurance requirements. These policies are required in Washington, D.C.

Workers' compensation insurance
Laws in Washington, D.C. require [PDF] businesses with one or more employees to carry workers’ comp insurance.
Sole proprietors can purchase workers’ comp for themselves, but are not required to unless they have employees. This policy covers medical payments for work-related injuries and illnesses.
Commercial auto insurance
All business-owned vehicles in Washington, D.C. must be covered by commercial auto insurance. This policy covers the cost of accidents involving your work vehicle.
Washington, D.C.'s car insurance requirements are:
- $25,000 bodily injury liability per person
- $50,000 bodily injury liability per accident
- $10,000 property damage liability
- $25,000 uninsured motorist coverage per person
- $50,000 uninsured motorist coverage per accident
- $5,000 uninsured motorist property damage
Trucking companies may need additional business insurance coverage to comply with regulations.
Though it's not required, personal vehicles driven for work purposes should be covered by hired and non-owned auto insurance (HNOA), as personal auto policies usually exclude business use. It can be added to general liability insurance or a business owner's policy.
How much does small business insurance cost in D.C.?
Commercial insurance can be affordable for small business owners. Based on policy data from Insureon customers in Washington, D.C., the average costs are:
General liability: $46 per month
Workers' comp: $88 per month
Professional liability/E&O: $118 per month
Factors that affect business insurance costs include:
- Your industry and risks
- Business operations
- Number of employees
- Policy limits and deductibles
Top professions we insure
FAQs about Washington, D.C. insurance
Review answers to frequently asked questions about business insurance in Washington, D.C.
How do I get a certificate of insurance for my business?
Insureon's licensed agents can help you find policies that fulfill Washington D.C.'s requirements and protect against financial loss. Once you've purchased insurance with us, you can download a certificate of insurance (COI) by logging into your account.
Can my company be held liable for a data security breach?
Yes – that's why cyber insurance is so crucial. Small businesses are a common target of cyberattacks since they often have fewer security measures in place.
Washington, D.C.'s data breach laws require businesses to report security breaches to affected residents, and the costs can escalate quickly. Cyber liability insurance lessens the financial impact by paying for notification costs, legal fees, and fines.
Does my industry affect regional insurance requirements?
Yes, your region may have special requirements for business insurance and bonds for your industry. You may also need a license depending on the work you do.
Contractors often need to carry general liability insurance or surety bonds to perform certain types of work. Having the right insurance and bonds helps you comply with regional licensing requirements.
Real estate agents and brokers and other professionals who offer advice or services sometimes need errors and omissions insurance to get licensed in their area.
Cities, counties, and states may also have their own laws.
How can I save money on Washington, D.C. business insurance?
As with any purchase, shopping around is one of the best ways to find an affordable option. With Insureon, you can compare quotes from top-rated providers by filling out a free online application.
Other ways to save include bundling policies for a discount, and choosing less expensive policy options, such as lower limits or a higher deductible. Learn more about how to find cheap business insurance.