

Get the right commercial insurance for your Portland business
Which insurance policies are recommended for Portland businesses?
From the tech startups of "Silicon Forest" and beyond, Portland fosters a wide range of innovative small businesses. Protect your Portland business with these insurance products.

General liability insurance
A general liability policy pays for legal costs from customer accidents, along with defamation and copyright infringement claims. Commercial leases in Portland often require this coverage.
- Customer accidents at your business
- Damage to a customer's property
- Slander and other advertising injuries

Professional liability insurance
A professional liability policy covers legal costs related to claims of negligence, such as advice that caused a client to lose money. It's sometimes called errors and omissions insurance (E&O).
- Mistakes that cause financial loss
- Accusations of professional negligence
- Missed deadlines

Cyber liability insurance
Cyber insurance helps small businesses in Portland recover after a data breach or a cyberattack. Every business that handles customer information should have this coverage.
- Data breach notification costs
- Fraud monitoring services
- PR campaigns after a breach

Business owner’s policy
A business owner's policy, or BOP, is an affordable way to buy general liability and commercial property insurance together. It's recommended for all small, low-risk businesses in Portland.
- Customer slip-and-fall injuries
- Damaged business property
- Theft and vandalism

Workers’ compensation insurance
Workers' comp is required for all Oregon businesses that have employees. It also covers work-related injuries for sole proprietors, which health insurance may deny.
- Medical bills from job-related injuries
- Disability benefits
- Lawsuits from injured workers

Commercial auto insurance
All vehicles owned by Portland businesses must be covered by commercial auto insurance. This policy primarily covers injuries and property damage caused by your vehicle.
- Injuries from an auto accident
- Damage caused by your vehicle
- Lawsuits from an auto accident

Errors and omissions insurance
E&O insurance protects consultants and professional services against legal defense costs from dissatisfied clients. It's also called professional liability insurance.
- Errors and oversights
- Breach of contract
- Professional negligence

Commercial property insurance
This policy covers physical damage to a Portland business's building and its contents, including any computers and equipment. You can bundle it with general liability in a BOP.
- Burglaries
- Fires
- Storm damage

Commercial umbrella insurance
An umbrella policy provides coverage once the limit is reached on your underlying general liability insurance, commercial auto insurance, or employer's liability insurance.
- Customer lawsuits
- Auto accident lawsuits
- Employee injury lawsuits
Verified business insurance reviews
Hear from customers like you who purchased small business insurance.
Which business insurance policies are required in Portland, OR?
State and local laws can determine the type of insurance you need. These policies help you comply with Oregon state business insurance requirements, as well as protect your business operations.

Workers' compensation insurance
Oregon state law requires all businesses with employees, including part-time employees, to carry workers’ compensation insurance. A workers' compensation policy pays for medical expenses from job-related injuries and illnesses. It also provides disability benefits for injured Oregon workers.
Most policies include employer's liability insurance, which protects against legal costs from workplace injuries.
Commercial auto insurance
Every vehicle owned by a Portland business must be covered by commercial auto insurance. This policy pays for medical costs, legal fees, and property damage after an auto accident.
Portland businesses must meet Oregon's requirements for auto liability coverage, which are:
- Bodily injury liability: $25,000 per person / $50,000 per accident
- Property damage liability: $20,000 per accident
- Uninsured motorist coverage: $25,000 per person / $50,000 per accident
- Personal injury protection (PIP): $15,000
Keep in mind that this is the minimum you're required to carry. It's worth considering higher limits, given the potential cost of a lawsuit. Trucking companies also may need more coverage to comply with regulations.
If you drive your own car for work purposes, it's important to know that your personal auto policy won't provide coverage. You can look to hired and non-owned auto insurance (HNOA) instead, which covers personal, leased, and rented vehicles used by your business.
How much does business insurance in Portland cost?
Small businesses in Portland don't have to pay a lot for commercial insurance. Here are a few average costs for Oregon businesses, based on policy data from Insureon customers:
General liability: $42 per month
Workers' comp: $60 per month
Professional liability/E&O: $70 per month
The cost of business liability insurance depends on factors such as:
- Type of business
- Business operations
- Number of employees
- Policy limits and deductibles
- Claims history
Top professions we insure
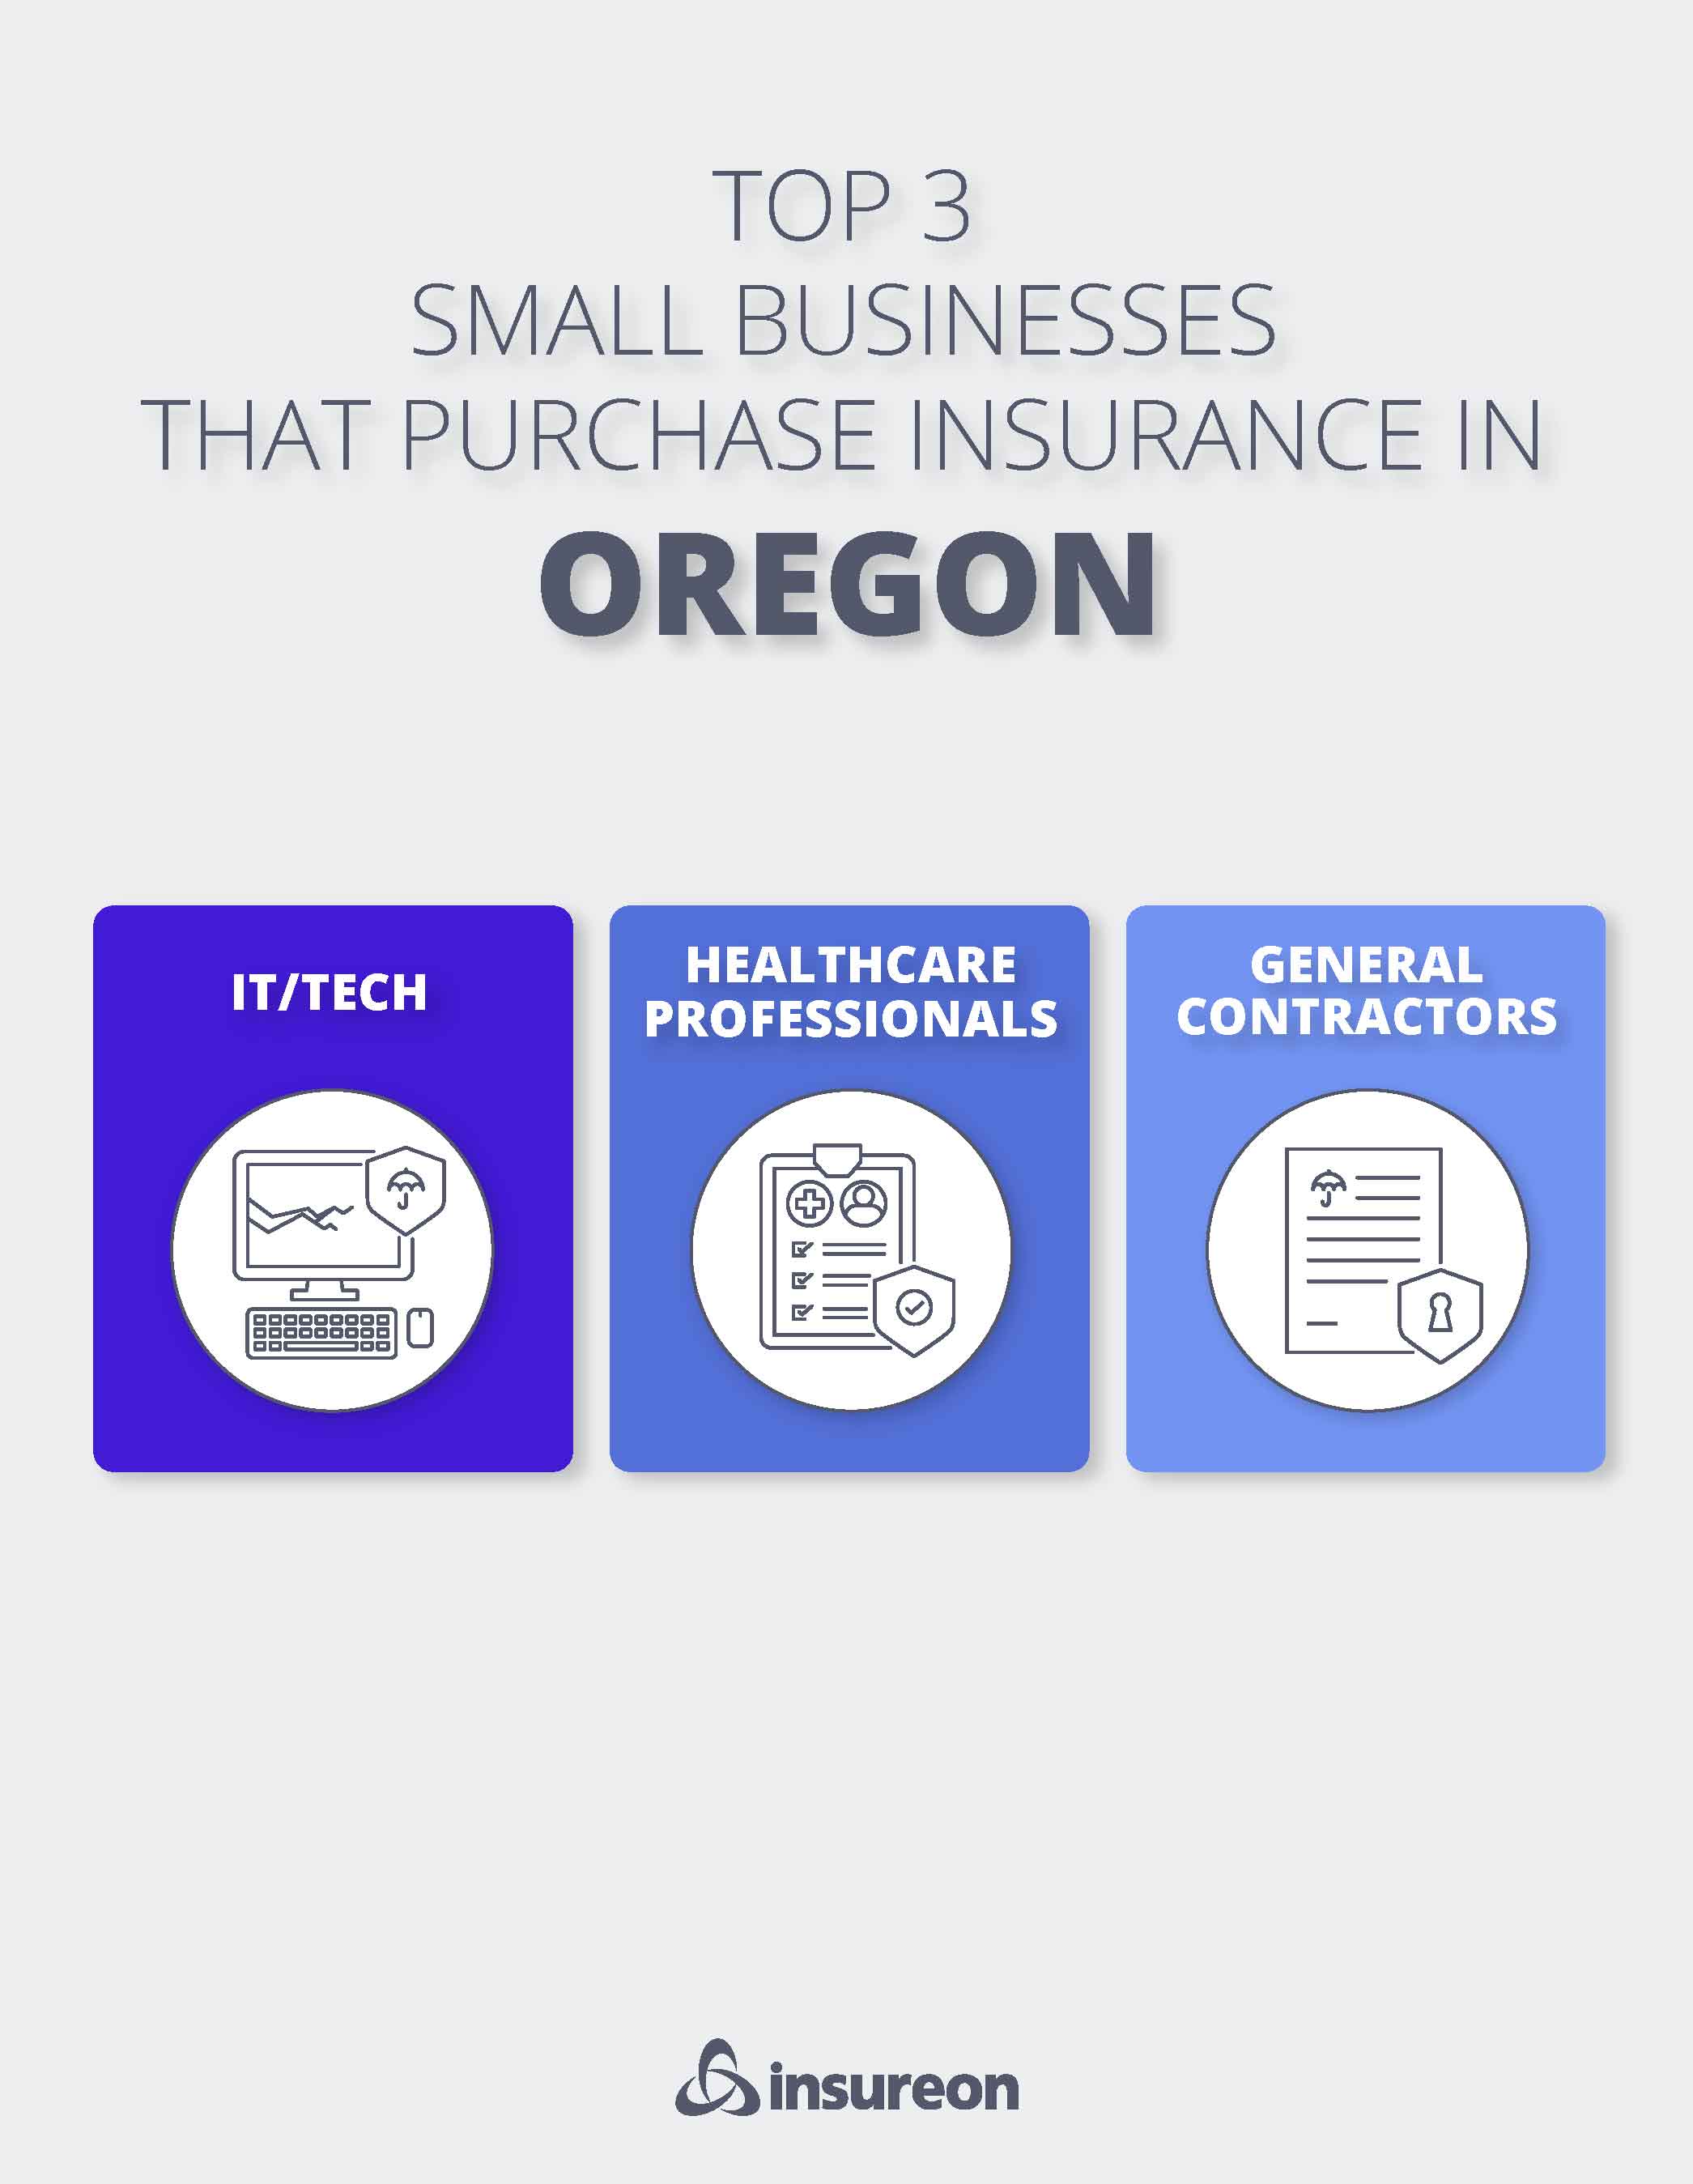
FAQs about Portland business insurance
Review answers to frequently asked questions about Portland insurance.
How do I get a certificate of insurance for my business?
Sometimes you need to get insured quickly to sign a contract or other agreement. With Insureon, you can get same-day insurance in three easy steps:
- Fill out our easy online application to get quotes from top-rated insurance carriers.
- Choose an insurance policy and pay for it online.
- Download a certificate of insurance (COI) by logging into your account.
Our licensed insurance agents will help you get the right types of coverage for your small Portland business that match your risks and insurance needs. Most businesses can get their certificate of insurance within a few hours of applying for quotes.
Can my business be held liable for a data security breach?
Yes – that's why cyber insurance is so crucial. Small businesses are a common target of cyberattacks since they often have fewer security measures in place.
Oregon's data breach laws require Portland businesses to notify any residents whose personal information is exposed in a data breach. Your business could also end up paying for a data breach investigation, a PR campaign, and other costs related to a security breach or cyberattack.
Cyber insurance covers these costs and provides resources so you can get back to business fast.
Does my industry affect Portland insurance requirements?
Unlike the state of Oregon, the city of Portland requires all businesses to be licensed. Both the state and the city may require business insurance and bonds depending on the type of work you do.
Here are a few examples of the obligations for different businesses:
- Contractors in Oregon must carry contractor general liability insurance and a surety bond to comply with state licensing requirements.
- Professional services businesses may need professional liability insurance, also called errors and omissions insurance (E&O), to get licensed in their profession or sign a contract. For example, all lawyers in Oregon are required to carry this coverage.
- Cannabis businesses in Oregon aren't required to carry business insurance to operate legally. However, coverage is strongly recommended to keep your business protected.
- Insurance companies in Portland and elsewhere in Oregon must carry E&O insurance for insurance consultants and managing general agents.
When running a business in Portland, you need to be aware of laws and regulations for Oregon, the city of Portland, and Multnomah County.
How can I get help starting a small business in Portland, OR?
The city of Portland has seen recent growth [PDF] in small businesses, fueled by microbusinesses of one to five employees. To help you get started, here's a list of local organizations that provide guidance and resources:
- The Oregon Secretary of State has a list of steps for how to set up shop in Oregon, from creating a business plan to hiring employees.
- The Multnomah County Library offers several resources for starting a small business in the county, including events and classes for entrepreneurs.
- The Portland Metro Chamber is one of many chambers of commerce in the area, which focus on networking events for small business owners.
- The Office of Small Business Assistance provides a list of resources designed to help entrepreneurs and nonprofits thrive in Oregon.
- The Portland Small Business Hub connects small business owners with advisors who can help you find loans, grants, and other opportunities.
- The Portland Small Business Development Center (SBDC) serves entrepreneurs pursuing business ownership through free consulting, training, and programs.
- The Oregon Association of Minority Entrepreneurs (OAME) promotes entrepreneurship and economic development for ethnic minorities in Oregon and southwest Washington.
- The Certification Office for Business Inclusion and Diversity (COBID) offers certifications for minority-owned, women-owned, and veteran-owned businesses to help level the playing field for government contracts.
- SCORE Portland offers free business advice and training, with support from experienced entrepreneurs from diverse industries and specialties.
- The Portland Office of the Small Business Administration (SBA) provides assistance with SBA services such as funding programs, counseling, and disaster recovery.
Keep in mind that many lenders will require you to first obtain several types of business insurance, which is yet another reason to insure your investment.
How can I save money on Oregon business insurance coverage?
Small business owners in Portland can save money by comparing quotes from different insurance companies. With Insureon, you can get free business insurance quotes from top-rated providers by completing our easy online application.
There are a few other ways to save, such as:
- Bundle policies for a discount. The most popular option is a business owner's policy.
- Choose less expensive policy options, such as lower limits or a higher deductible.
- Focus on workplace safety. Risk management helps reduce accidents, and a clean history of claims keeps your premium low.
Learn more about how to find cheap business insurance.