

Get the right commercial insurance for your Sacramento business
Which policies are recommended for Sacramento businesses?
Sacramento is a welcoming city for small businesses and startups alike. Protect your Sacramento small business with the following popular insurance policies.

General liability insurance
A general liability policy pays for legal costs from customer accidents, as well as defamation and copyright infringement claims. Commercial leases in Sacramento often require this coverage.
- Customer accidents at your business
- Damage to a customer's property
- Slander and other advertising injuries

Professional liability insurance
A professional liability policy covers legal costs related to claims of negligence, such as advice that caused a client to lose money. It's sometimes called errors and omissions insurance (E&O).
- Mistakes that cause financial loss
- Accusations of professional negligence
- Missed deadlines

Cyber insurance
Cyber insurance helps small businesses in Sacramento recover after a data breach or a cyberattack. Every business that handles customer information should have this coverage.
- Data breach notification costs
- Fraud monitoring services
- PR campaigns after a breach

Business owner’s policy
A business owner's policy, or BOP, is an affordable way to buy general liability and commercial property insurance together. It's recommended for all small, low-risk businesses in Sacramento.
- Customer slip-and-fall injuries
- Damaged business property
- Theft and vandalism

Workers’ compensation insurance
Workers’ comp covers medical bills and provides disability benefits for injured employees. It also protects sole proprietors from work-related medical bills that health insurance may deny.
- Medical bills from job-related injuries
- Disability benefits
- Lawsuits from injured workers

Commercial auto insurance
All vehicles owned by Sacramento businesses must be covered by commercial auto insurance. This policy primarily covers injuries and property damage caused by your vehicle.
- Injuries from an auto accident
- Damage caused by your vehicle
- Lawsuits from an auto accident

Errors and omissions insurance
E&O insurance protects consultants and professional services against legal defense costs from dissatisfied clients. It's also called professional liability insurance.
- Errors and oversights
- Breach of contract
- Professional negligence

Commercial property insurance
This policy covers physical damage to a Sacramento business's building and its contents, including any computers and equipment. You can bundle it with general liability in a BOP.
- Fires
- Burst pipes
- Storm damage

Commercial umbrella insurance
An umbrella policy provides coverage once the limit is reached on your underlying general liability insurance, commercial auto insurance, or employer's liability insurance.
- Customer lawsuits
- Auto accident lawsuits
- Employee injury lawsuits
Verified business insurance reviews
Hear from customers like you who purchased small business insurance.
Which business insurance policies are required in Sacramento?

Workers' compensation insurance
California state law requires businesses with any employees, full-time or part-time, to carry workers’ comp insurance.
Additionally, all licensed contractors are required by law to have workers' comp starting in January 2028, even if they don’t employ anyone else. Contractors who already need this coverage include roof contractors, tree service technicians, and HVAC contractors.
Workers' comp covers medical bills for work-related injuries and illnesses. It also provides disability benefits for injured Sacramento workers.
Commercial auto insurance
In California, all companies with commercial vehicles are required to carry commercial auto insurance. This policy covers legal costs, medical payments, and damages resulting from auto accidents that take place during business operations.
Sacramento small business owners need to carry the minimum California auto liability coverage of:
- $30,000 per person in bodily injury liability or death liability
- $60,000 for multiple people in bodily injury liability or death liability
- $15,000 per accident in property damage
Failing to have the minimum coverage can result in fines, vehicle impound, license suspension, and higher premiums. You may want to consider additional coverage for exceptionally costly accidents or lawsuits.
If you or any of your employees plan on driving a personal vehicle for work purposes, you'll need additional liability coverage called a hired and non-owned auto (HNOA) insurance policy.
Having the proper coverage is essential because personal auto insurance will typically not cover accidents that occur during work-related activities.
How much does business insurance in Sacramento cost?
Small businesses in Sacramento don't have to pay a lot for commercial insurance. Here are a few average costs for California businesses, based on policy data from Insureon customers:
General liability: $42 per month
Workers' comp: $63 per month
Professional liability/E&O: $94 per month
The cost of business insurance depends on factors such as:
- Type of business
- Business operations
- Number of employees
- Policy limits and deductibles
- Claims history
Top professions we insure
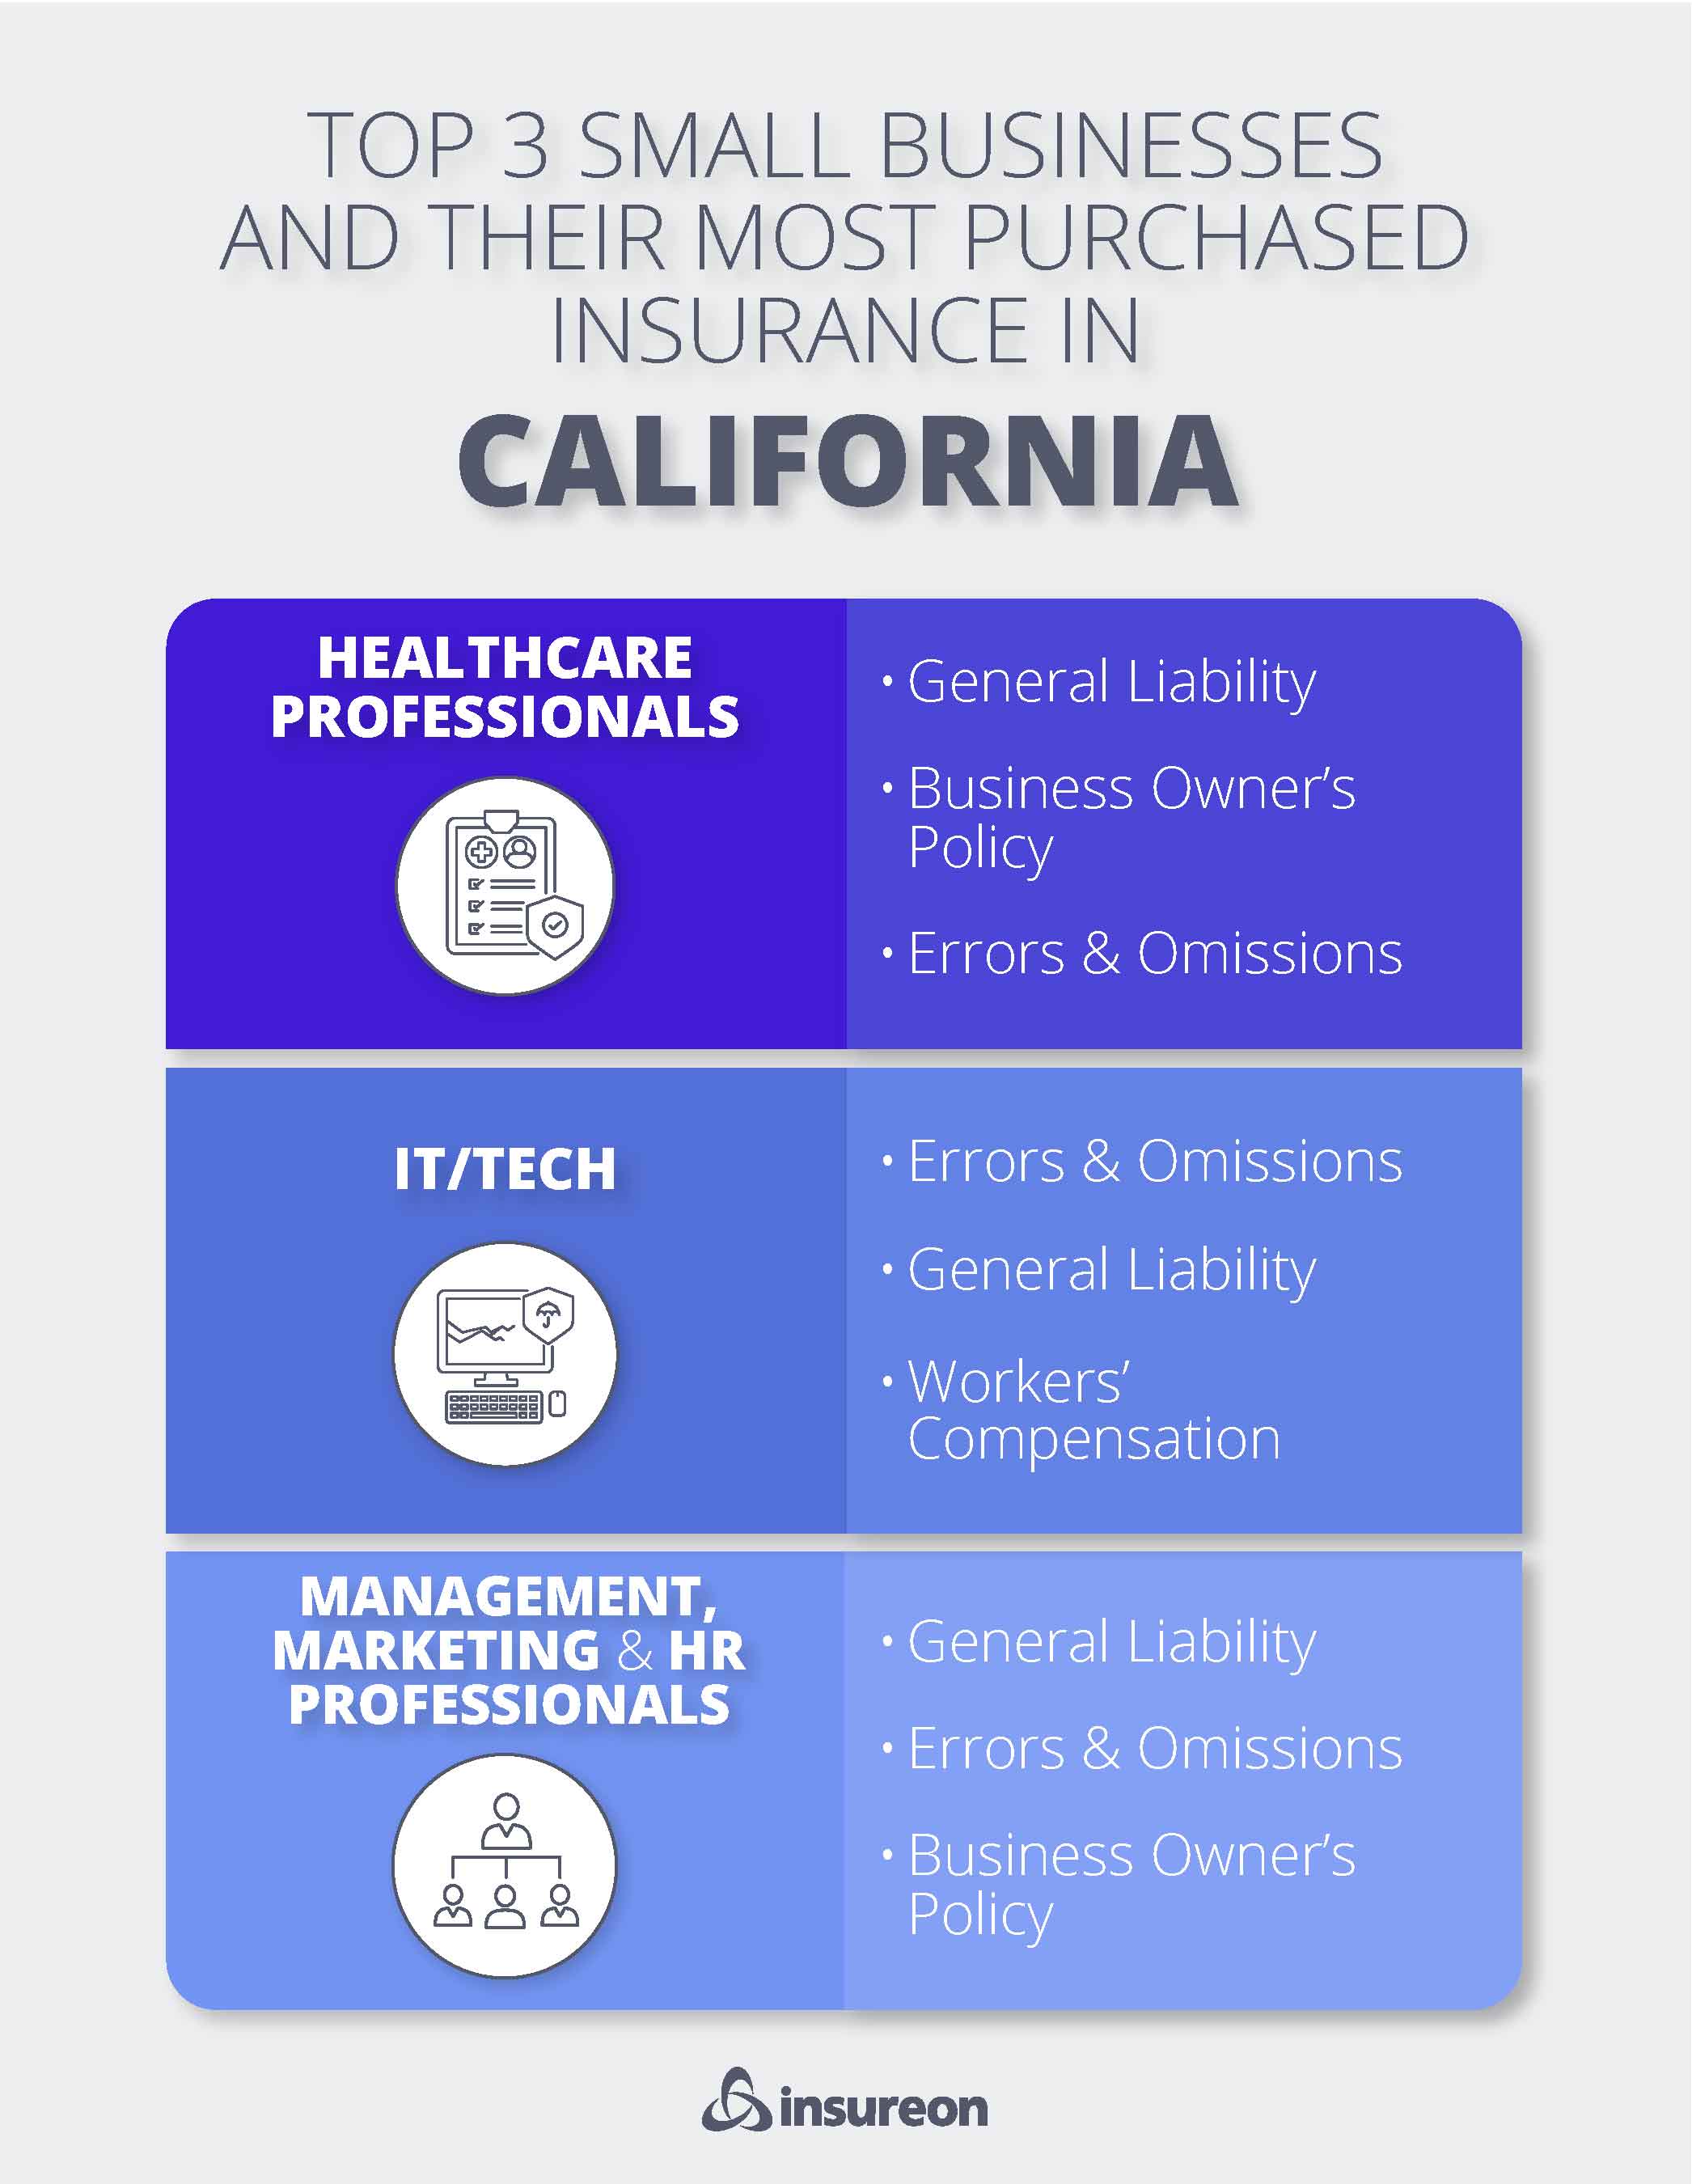
FAQs about Sacramento business insurance
How do I get a certificate of insurance for my business?
As a small business owner, you may need to get insurance quickly to sign a contract, a lease, or other business agreement. With Insureon, you can get same-day insurance quickly in three simple steps:
- Fill out an easy online application and get quotes from the nation's top insurance agencies.
- Pick a policy that matches your business and budget, and pay for it online.
- Download your certificate of insurance (COI) by logging into your account.
Insureon's agents are licensed in California and will help you get the coverage that works for your business needs. Most California businesses, from San Francisco to Los Angeles, receive their certificate of insurance and an active policy within just a few hours.
Can my business be held liable for a data security breach?
Yes—that's why cyber insurance is so crucial. Small businesses are a common target of cyberattacks since they often have fewer security measures in place.
Data breach laws in California require Sacramento businesses to notify residents in writing if their personal information has been compromised in a cyberattack. Depending on how many residents are impacted, the business may also need to alert the Attorney General.
Additionally, you may be responsible for providing at least twelve months of credit monitoring services to impacted residents.
A data leak may require you and your business to pay for an investigation, lawsuits, and other related expenses. Purchasing cyber insurance will help cover the costly expenses of managing compromised personal information.
Does my industry affect Sacramento insurance requirements?
Your industry can determine the type of insurance plan you may need to operate within Sacramento. Some businesses require additional coverage depending on the risks associated with their industry.
Examples of some professionals and industries that may require additional coverage in Sacramento include:
- Landscaping businesses in California must have general liability insurance.
- Lawyers need to carry professional liability insurance or disclose to their clients that they do not have this policy.
- Though not required by law, California home-based businesses should have commercial property insurance because personal renter's insurance and homeowner's insurance don't typically cover business property.
- Childcare facilities also need to carry general liability insurance or inform their clients that they do not have general liability via a signed affidavit.
- Cannabis businesses in Sacramento are required to carry business liability insurance as well as a surety bond to sell cannabis products in the state.
- Contractors in California typically must have a contractor general liability insurance policy, workers' comp, and a surety bond.
Many small businesses are not required to carry insurance in order to operate in Sacramento. However, each type of business has insurance solutions that would benefit them in the event of a lawsuit, accident, or other risks associated with their day-to-day operations.
How can I get help starting a small business in Sacramento?
If you'd like assistance starting or growing your Sacramento small business, consider the following resources for help with funding, business planning, mentorship, and more.
- Sacramento Works Business Information Center helps small businesses with recruiting, counseling, and workshops.
- The Sacramento Valley Small Business Development Center provides advising, funding, webinars, and other support for current and prospective small business and startup owners.
- California State University, Sacramento assists small business owners with financial resources, marketing plans, and strategic planning.
- At the Sacramento Public Library, you can research business opportunities, create marketing mailing lists and visuals, and access a wide range of legal and business resources.
- Sacramento County has a comprehensive online guide for starting a business in the area.
- The United States Small Business Administration Sacramento District Office provides disaster relief services, financial programs, contract certifications, and advising programs to small business owners in the Sacramento area.
How can I save money on Sacramento business insurance?
Saving money on small business insurance is simple with Insureon's easy online application. We provide quotes from the nation's top insurance companies to help you compare coverage and pick the best policies for your small business insurance needs.
Some other ways to save on your insurance coverage options include:
- Only purchase the coverage you need for your industry. You have some flexibility to pick and choose the best insurance products for your specific industry's risks and liabilities, which can save you money.
- Focus on workplace safety, accessibility, and fair business practices. The fewer lawsuits, injuries, or accidents your company faces, the lower your premiums will be.
- Bundle policies for a discount. Some types of insurance can be bundled to lower costs. A business owner's policy (BOP) is one of the most common bundles.
Speak with one of our licensed insurance agents to discuss the best ways to save money on your insurance, or read more about obtaining cheap business insurance.