


Get the right commercial insurance for your San Francisco business
Which policies are recommended for San Francisco businesses?
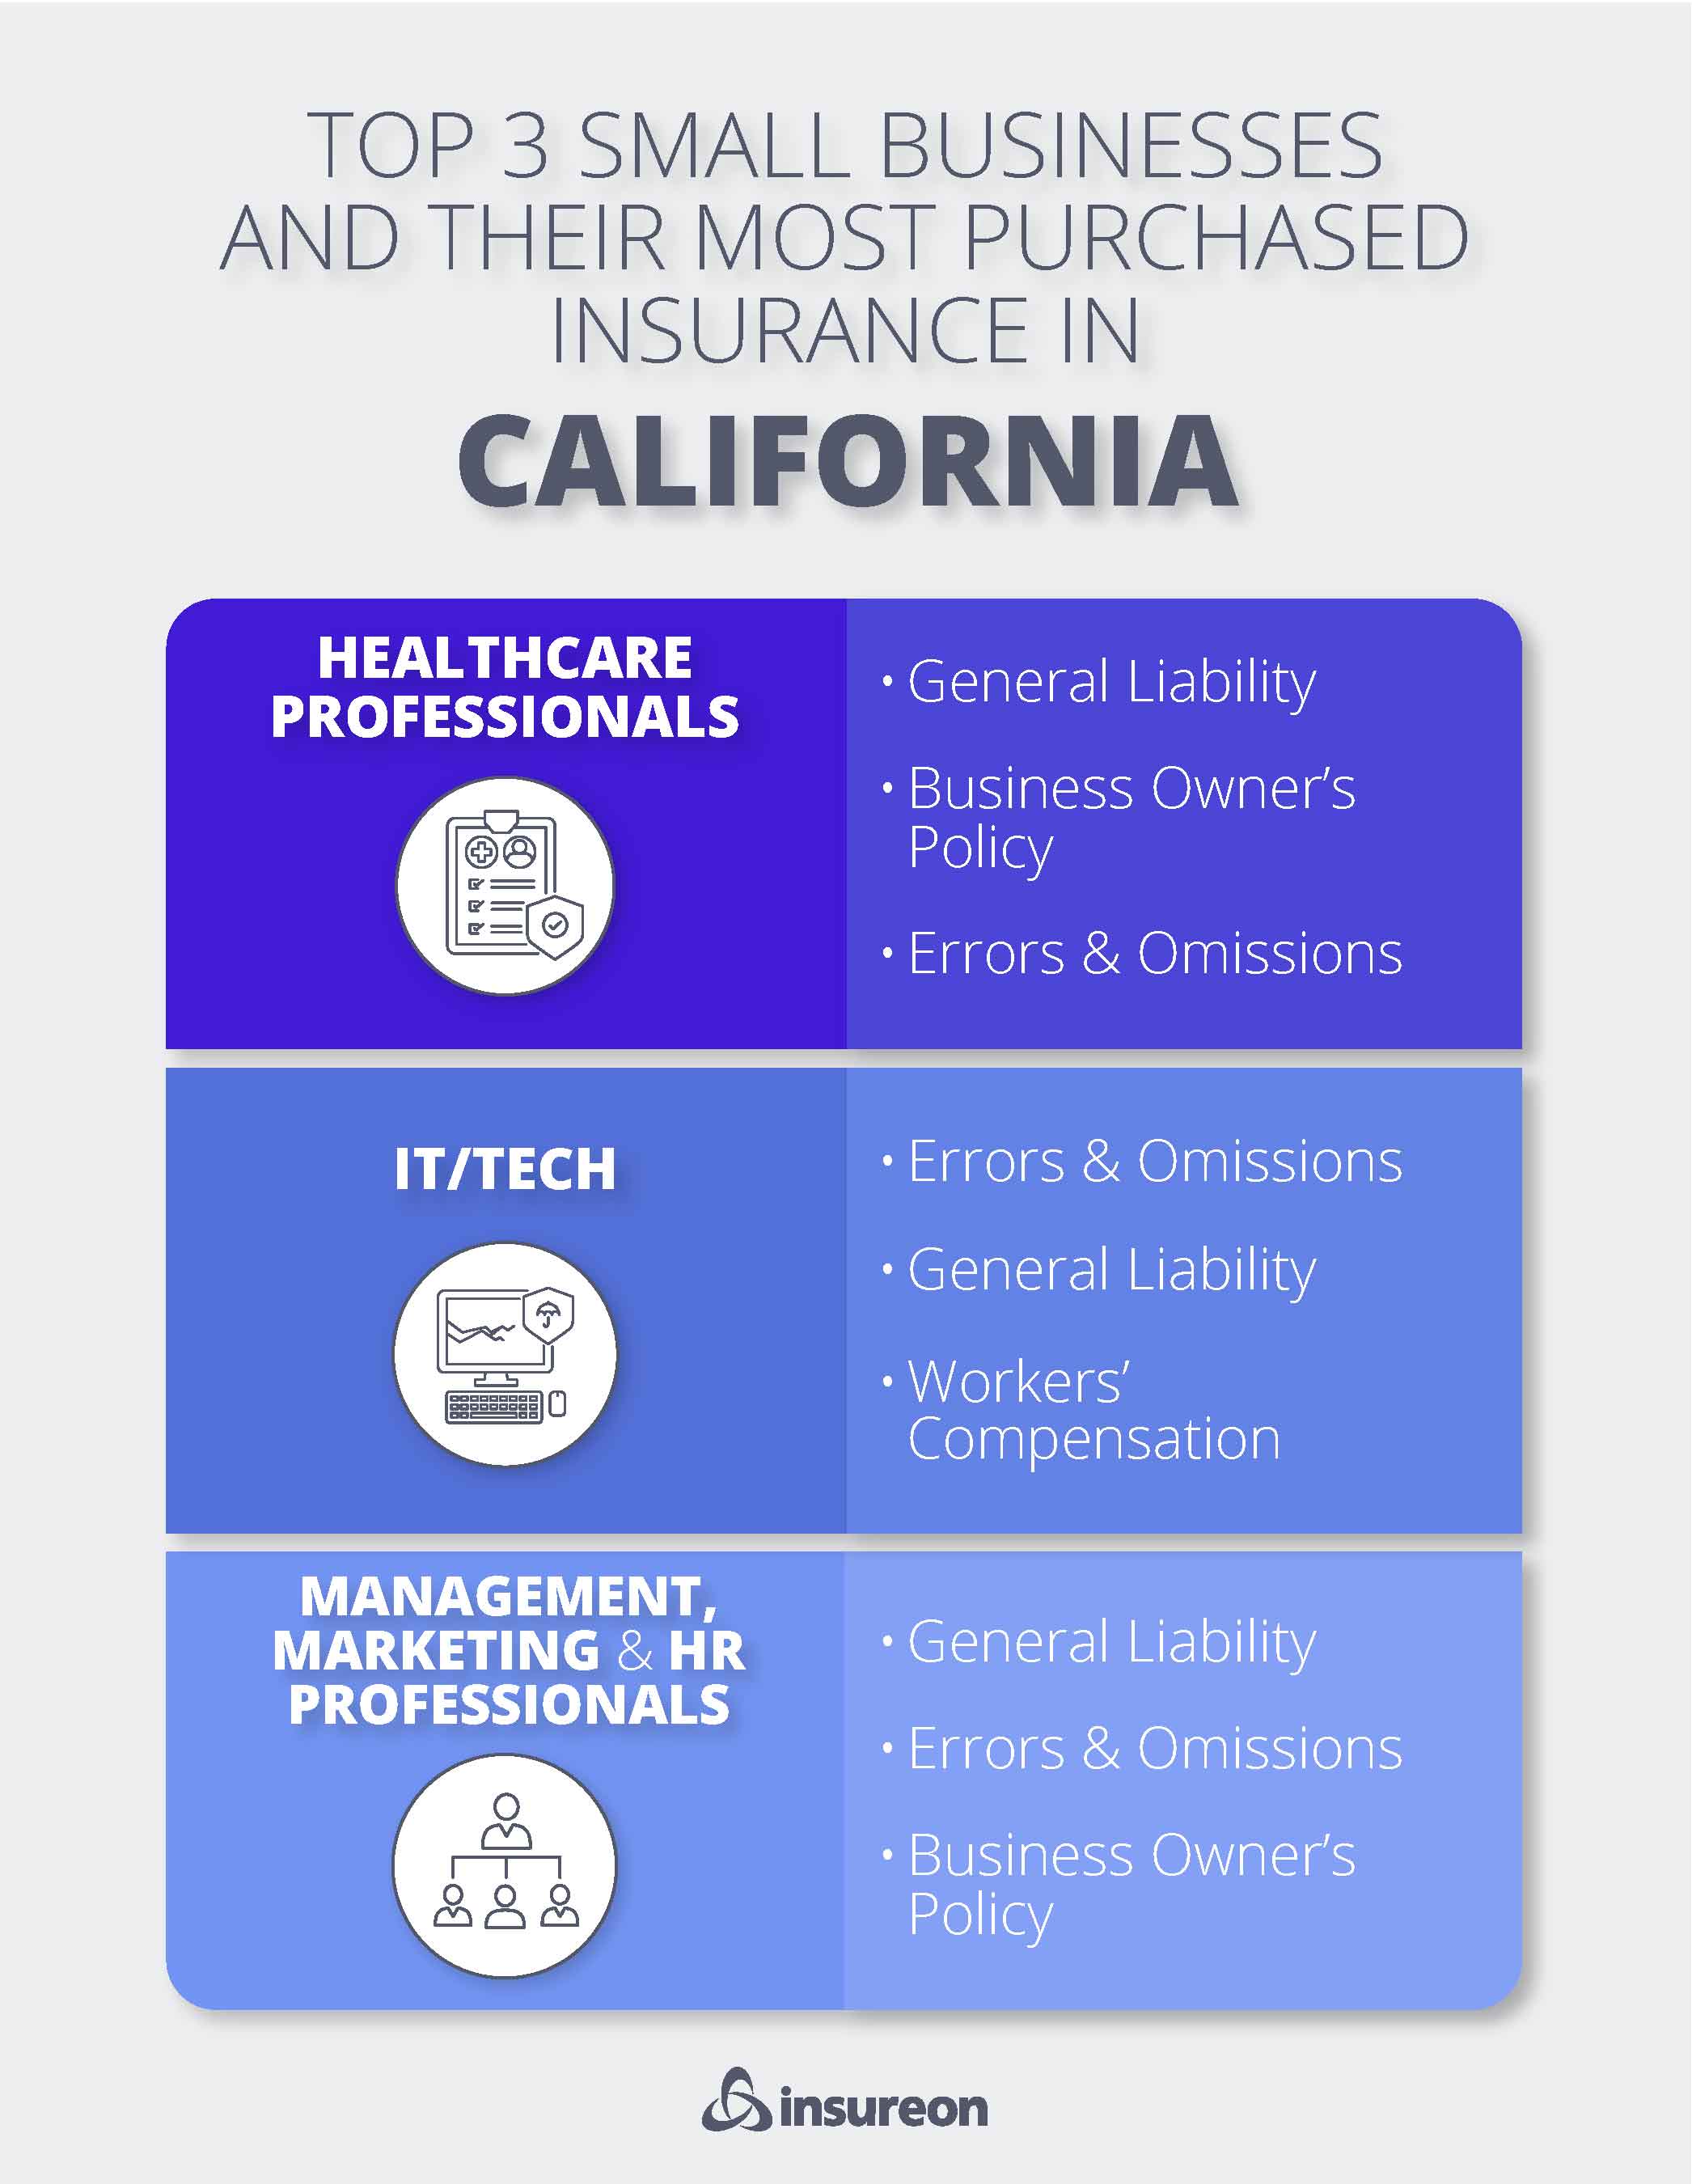
Forbes called San Francisco the "Best Small Business City in America." Protect your San Francisco business with these popular insurance policies.

General liability insurance
A general liability policy pays for legal costs from customer accidents as well as advertising injury claims, such as libel. Commercial leases in San Francisco often require this coverage.
- Customer accidents at your business
- Damage to a customer's property
- Slander and other advertising injuries

Professional liability insurance
A professional liability policy covers legal costs related to claims of negligence, such as advice that caused a client to lose money. It's sometimes called errors and omissions insurance (E&O).
- Mistakes that cause financial loss
- Accusations of professional negligence
- Missed deadlines

Cyber insurance
Cyber insurance helps small businesses recover after a data breach or a cyberattack. Every business that handles customer information should have this coverage.
- Data breach notification costs
- Fraud monitoring services
- PR campaigns after a breach

Business owner’s policy
A business owner's policy, or BOP, is an affordable way to buy general liability and commercial property insurance together. It's recommended for all small, low-risk businesses in San Francisco.
- Customer slip-and-fall injuries
- Damaged business property
- Theft and vandalism

Workers’ compensation insurance
Workers’ comp covers medical bills and provides disability benefits for injured employees. It also protects sole proprietors from work-related medical bills that health insurance may deny.
- Medical bills from job-related injuries
- Disability benefits
- Lawsuits from injured workers

Commercial auto insurance
All vehicles owned by San Francisco businesses must be covered by commercial auto insurance. This policy primarily covers injuries and property damage caused by your vehicle.
- Injuries from an auto accident
- Damage caused by your vehicle
- Lawsuits from an auto accident

Errors and omissions insurance
E&O insurance protects consultants and professional services against legal defense costs from dissatisfied clients. It's also called professional liability insurance.
- Errors and oversights
- Breach of contract
- Professional negligence

Commercial property insurance
This policy covers physical damage to a San Francisco business's building and its contents, including any computers and equipment. You can bundle it with general liability in a BOP.
- Fires
- Burst pipes
- Storm damage

Commercial umbrella insurance
An umbrella policy provides coverage once the limit is reached on your underlying general liability insurance, commercial auto insurance, or employer's liability insurance.
- Customer lawsuits
- Auto accident lawsuits
- Employee injury lawsuits
Verified business insurance reviews
Hear from customers like you who purchased small business insurance.
Which business insurance policies are required in San Francisco?

Workers' compensation insurance
California state law requires businesses with any employees, full-time or part-time, to carry workers’ comp insurance.
Additionally, all licensed contractors are required by law to have workers' comp starting in January 2028, even if they don’t employ anyone else. Contractors who already need this coverage include roof contractors, tree service technicians, and HVAC contractors.
Workers' comp covers medical bills for work-related injuries and illnesses. It also provides disability benefits for injured San Francisco workers.
Commercial auto insurance
Commercial auto insurance is mandatory for all vehicles owned by San Francisco businesses.
San Francisco businesses must carry minimum auto liability coverage, which consists of:
- $30,000 per person in bodily injury liability or death liability
- $60,000 for multiple people in bodily injury liability or death liability
- $15,000 per accident in property damage
Consider higher coverage limits to protect against exceptionally costly accidents and lawsuits. Trucking companies often require additional coverage based on their vehicle types.
If you or any of your employees plan on using personal vehicles for work purposes, you may need a hired and non-owned auto insurance policy. Personal auto insurance does not typically cover work-related accidents.
How much does business insurance in San Francisco cost?
Small businesses in the San Francisco Bay Area don't have to pay a lot for commercial insurance. Here are a few average costs for California businesses, based on policy data from Insureon customers:
General liability: $42 per month
Workers' comp: $63 per month
Professional liability/E&O: $94 per month
The cost of business insurance depends on factors such as:
- Type of business
- Business operations
- Number of employees
- Policy limits and deductibles
- Claims history
Top professions we insure
FAQs about San Francisco business insurance
How do I get a certificate of insurance for my business?
Sometimes you need to get small business insurance fast, such as when you need to secure a policy to sign a rental agreement. Insureon can help you get same-day coverage for your San Francisco business. Just follow these three easy steps:
- Fill out our easy online application to get quotes from the nation's top insurance providers.
- Pick a policy that suits your insurance needs and pay for it online.
- Download your certificate of insurance (COI) by logging into your account.
Our insurance brokers are licensed in California and can help you get the coverage you need. Most San Francisco businesses get their certificate of insurance and an active policy within a few hours.
Can my business be held liable for a data security breach?
Yes—that's why cyber insurance is so crucial. Small businesses are a common target of cyberattacks since they often have fewer security measures in place.
San Francisco businesses that experience a data breach are required by California state law to notify residents if their personal information is compromised.
Recovering from a data breach is a long and costly process. Your business might need to pay for an incident investigation, a PR campaign, notification costs, or even legal costs if they were responsible for another business's cybersecurity.
Does my industry affect San Francisco insurance requirements?
Your industry helps determine the kind of business insurance and bonds you need to operate in San Francisco.
Here are several examples of industries that may require additional levels of insurance:
- California contractors typically must carry general liability insurance for contractors, workers' comp, and a surety bond.
- Lawyers are not required to carry professional liability insurance in California, but they are required to disclose to their clients if they do not have this policy.
- Similarly, San Francisco childcare facilities either need to carry general liability insurance or must have all clients sign an affidavit stating they understand that the facility does not carry insurance.
- Lawn care businesses in California are required to carry general liability insurance.
- Cannabis dispensaries in San Francisco must have business liability insurance and a surety bond to operate.
Other San Francisco professionals, such as housekeepers, nurses, and photographers, are not legally required to carry coverage, though contracts might require it. They should still invest in protection against property damage, lawsuits, and other common risks that could otherwise bankrupt their business.
How can I get help starting a small business in San Francisco?
San Francisco has been ranked one of the best cities in the United States for starting a small business. If you're interested in developing or growing your small San Francisco business, consider the following resources for funding, training, mentorship, and more.
- The City of San Francisco's Office of Small Business has guides for starting your business, free counseling services, and support with obtaining necessary permits.
- The San Francisco Small Business Development Center helps businesses with free webinars, trainings, advising services, and funding support.
- The U.S. Small Business Administration has a San Francisco division that provides training sessions, federal contract information, and funding programs for small business owners.
- The San Francisco Public Library offers resources for startups and small businesses. It has business planning resources, grant and loan information, as well as business directories.
- BART's Office of Civil Rights provides support services for minority, women, veterans, and LGBTQ-owned businesses that want to bid for contracts with the San Francisco government.
How can I save money on San Francisco business insurance?
Comparing quotes from different insurance companies is one of the easiest ways to save money on small business insurance. With Insureon, you can get free quotes from top-rated insurance companies by completing one easy application.
Some other tips to save money on small business insurance:
- Pick the right types of business insurance. Different industries have different risks, and picking only the insurance products you need will help you save.
- Bundle your policies. Certain policies can be bundled by your insurance agency at a discount. A business owner's policy is a common choice.
- Focus on workplace safety and compliance. The fewer lawsuits and accidents your business has, the lower your premiums will be.
Learn more about finding the best cheap business insurance coverage.