

Get the right commercial insurance for your Seattle business
Which insurance policies are recommended for Seattle businesses?
Home to tech giants and startups alike, Seattle ranks among the top cities for small business. Protect your Seattle business with these insurance products.

General liability insurance
A general liability policy pays for legal costs from customer accidents, along with defamation and copyright infringement claims. Commercial leases in Seattle often require this coverage.
- Customer accidents at your business
- Damage to a customer's property
- Slander and other advertising injuries

Professional liability insurance
A professional liability policy covers legal costs related to claims of negligence, such as advice that caused a client to lose money. It's sometimes called errors and omissions insurance (E&O).
- Mistakes that cause financial loss
- Accusations of professional negligence
- Missed deadlines

Cyber liability insurance
Cyber insurance helps small businesses in Seattle recover after a data breach or a cyberattack. Every business that handles customer information should have this coverage.
- Data breach notification costs
- Fraud monitoring services
- PR campaigns after a breach

Business owner’s policy
A business owner's policy, or BOP, is an affordable way to buy general liability and commercial property insurance together. It's recommended for all small, low-risk businesses in Seattle.
- Customer slip-and-fall injuries
- Damaged business property
- Theft and vandalism

Workers’ compensation insurance
Workers' comp is required for all Washington businesses that have employees. It also covers work-related injuries for sole proprietors, which health insurance may deny.
- Medical bills from job-related injuries
- Disability benefits
- Lawsuits from injured workers

Commercial auto insurance
All vehicles owned by Seattle businesses must be covered by commercial auto insurance. This policy primarily covers injuries and property damage caused by your vehicle.
- Injuries from an auto accident
- Damage caused by your vehicle
- Lawsuits from an auto accident

Errors and omissions insurance
E&O insurance protects consultants and professional services against legal defense costs from dissatisfied clients. It's also called professional liability insurance.
- Errors and oversights
- Breach of contract
- Professional negligence

Commercial property insurance
This policy covers physical damage to a Seattle business's building and its contents, including any computers and equipment. You can bundle it with general liability in a BOP.
- Fires
- Burst pipes
- Storm damage

Commercial umbrella insurance
An umbrella policy provides coverage once the limit is reached on your underlying general liability insurance, commercial auto insurance, or employer's liability insurance.
- Customer lawsuits
- Auto accident lawsuits
- Employee injury lawsuits
Verified business insurance reviews
Hear from customers like you who purchased small business insurance.
Which business insurance policies are required in Seattle?
State and local laws can determine the type of insurance you need. These policies help you comply with Washington state business insurance requirements, as well as protect your business operations.

Workers' compensation insurance
Washington state law requires all businesses with employees, including part-time employees, to carry workers’ compensation insurance. Because Washington is one of four monopolistic states for workers' comp, small business owners must buy this policy through the state fund instead of a private insurer.
Workers' comp pays for medical expenses from job-related injuries and illnesses, such as a cleaning company employee becoming sick from cleaner fumes. It also provides disability benefits to injured Seattle workers.
Policies purchased through the state fund do not include employer's liability insurance, which protects against legal costs from workplace injuries. You can add it as stop gap insurance from a private insurance company.
Commercial auto insurance
Every vehicle owned by a Seattle business must be covered by commercial auto insurance. This auto policy pays for medical costs, legal fees, and property damage after an auto accident.
Seattle businesses must meet the state's requirements for auto liability coverage, which are:
- $25,000 bodily injury liability per person
- $50,000 bodily injury liability per accident
- $10,000 property damage liability per accident
Keep in mind that this is the minimum you're required to carry. It's worth considering higher limits, given the potential cost of a lawsuit. Trucking companies may also need more coverage to comply with regulations.
If you need business insurance coverage for a personal, rented, or leased vehicle, you may want to consider hired and non-owned auto insurance (HNOA) instead.
How much does business insurance in Seattle cost?
Small businesses in Seattle don't have to pay a lot for commercial insurance solutions. Here are a few average costs for Washington businesses, based on policy data from Insureon customers:
General liability: $45 per month
Professional liability/E&O: $89 per month
Business owner's policy: $77 per month
The cost of business liability insurance depends on factors such as:
- Type of business
- Business operations
- Number of employees
- Policy limits and deductibles
- Claims history
Top professions we insure
FAQs about Seattle business insurance
Review answers to frequently asked questions about Seattle insurance.
How do I get a certificate of insurance for my business?
Sometimes you need to get insured quickly to sign a contract or other agreement. With Insureon, you can get same-day insurance in three easy steps:
- Fill out our easy online application to get quotes from top-rated insurance carriers.
- Choose the insurance option that suits your coverage needs and pay for it online.
- Download a certificate of insurance (COI) by logging into your account.
Our licensed insurance agents will help you get the right types of coverage for your small Seattle business that match your risks and insurance needs. Most businesses can get their certificate of insurance within a few hours of applying for quotes.
Can my business be held liable for a data security breach?
Yes – that's why cyber insurance is so crucial. Small businesses are a common target of cyberattacks since they often have fewer security measures in place.
Washington's data breach laws require Seattle businesses to notify any residents whose personal information is exposed in a data breach. Your business could also end up paying for a data breach investigation, a PR campaign, and other costs related to a breach or cyberattack.
Cyber insurance covers these costs and provides resources so you can get back to business fast.
Does my industry affect Seattle insurance requirements?
Yes, the city of Seattle may have special requirements for business insurance and bonds, depending on the type of work you do.
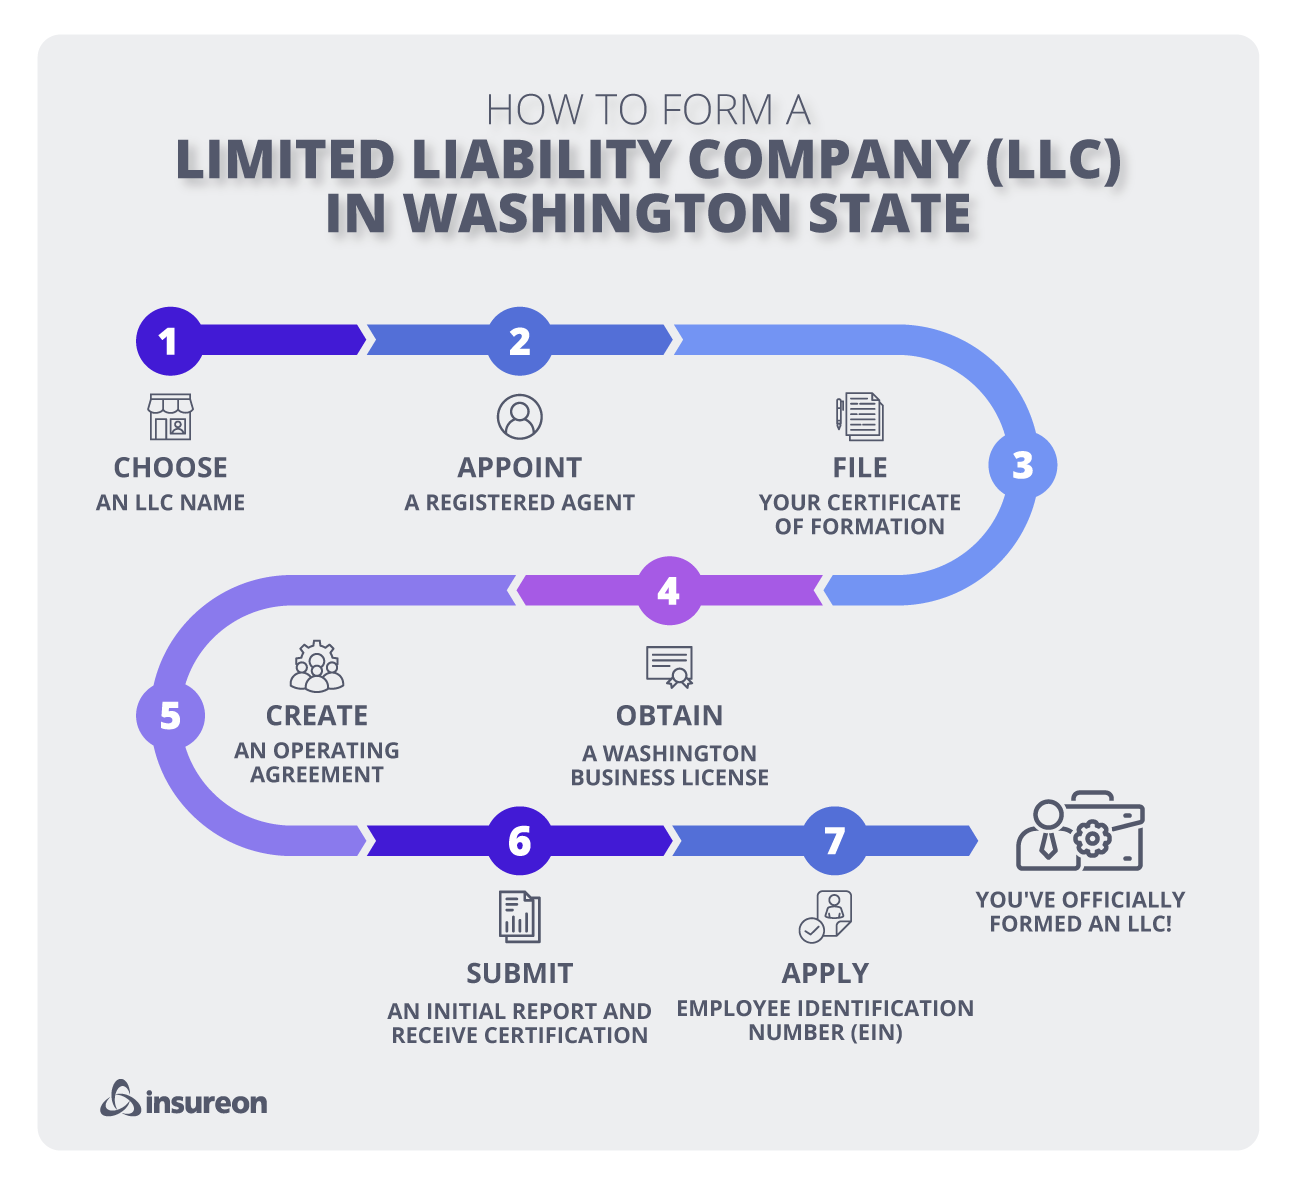
All businesses operating in Seattle must obtain a business license and renew it each year. Certain types of businesses need a regulatory endorsement added to their business license.
Here are a few examples of businesses with additional obligations:
- General contractors need contractor general liability insurance and a surety bond to get licensed in Washington, and they must register with Labor & Industries (L&I). Contractors who do plumbing, electrical work, or other specialty work have additional responsibilities.
- Cannabis businesses in Washington must carry general liability insurance with the state included as an additional insured. They must obtain a cannabis business license and a Washington State Liquor and Cannabis Board (WSLCB) license, in addition to the regular business license.
- Towing companies that operate in Washington must have a regulatory towing license in addition to their business license. The towing license costs $525 annually.
When running a business in Seattle, you need to be aware of laws and regulations for Washington state, King County, and the city of Seattle.
How can I get help starting a small business in Seattle?
Seattle is one of the best places to start a small business, thanks to its growing diversity and city programs that foster small business growth.
Here's a list of local organizations that provide support and resources:
- The Seattle Public Library has a Library to Business program offering free resources for small business owners, including classes and workshops.
- The Seattle Metropolitan Chamber of Commerce enables local networking opportunities and support for small businesses.
- The Office of Economic Development (OED) has a Small Business Development team that works with individual businesses to help them grow and thrive.
- SCORE Greater Seattle provides free business advice and training, with support from entrepreneurs from a wide range of industries.
- The Small Business Liaison Team (SBLT) supplies a free Small Business Guide, workshops, and resources with the goal of making it easier to do business in the state of Washington.
- The Washington Small Business Development Center (SBDC) offers free training and advice for Washington business owners.
- Business Impact NW aims to support businesses that create jobs in underserved communities through business coaching and access to funding.
- The Small Business Administration (SBA) is a reliable source of small business loans and resources nationwide.
Keep in mind that many lenders will require you to first obtain business insurance, which is yet another reason to insure your investment.
How can I save money on Seattle business insurance?
Small business owners can save money on the right coverage by comparing quotes from different insurance agencies. With Insureon, you can get free quotes from top-rated providers by filling out one easy application.
There are a few other ways to save, such as:
- Bundle policies for a discount. The most popular option is a business owner's policy.
- Choose cheaper business insurance options, such as lower limits or a higher deductible.
- Focus on workplace safety. Fewer accidents mean fewer claims, which helps keep your premium low.
Learn more about how to find cheap business insurance.