

Get the right commercial insurance for your NYC business
Which insurance policies are recommended for NYC businesses?
New York City is a global hub for entrepreneurs and investors, which makes it an attractive place to do business despite high costs. Protect your small NYC business with these common insurance policies.

General liability insurance
A general liability policy protects NYC businesses from lawsuits related to customer accidents, defamation, and copyright infringement. Commercial leases often require this coverage.
- Customer injuries at your business
- Damage to a customer's property
- Libel and other advertising injuries

Professional liability insurance
This policy covers legal fees related to mistakes and oversights, such as a missed deadline that harms a client's bottom line. It's also called errors and omissions insurance (E&O).
- Mistakes that cause financial loss
- Accusations of professional negligence
- Missed deadlines

Cyber insurance
Cyber insurance covers costs related to data breaches and cyberattacks. Every New York City business that handles credit cards or other personal information should carry this coverage.
- Customer notification costs
- Fraud monitoring services
- Data breach investigations

Business owner’s policy
A BOP bundles general liability coverage and commercial property insurance together at a discount. It's the policy most often recommended for small businesses in New York City.
- Customer injuries
- Damaged business property
- Business interruption coverage

Workers’ compensation insurance
Workers’ comp is required for all New York businesses that have employees. It also covers work-related medical bills for sole proprietors, which personal health insurance may not cover.
- Medical bills from employee injuries
- Disability benefits
- Workplace injury lawsuits

Commercial auto insurance
All vehicles owned by New York businesses must be covered by commercial auto insurance. This policy covers auto accident injuries, property damage, and legal costs.
- Medical bills from an accident
- Property damage caused by your vehicle
- Auto accident lawsuits

Errors and omissions insurance
This business liability insurance for professional services and consultants protects against legal costs from clients harmed by your work. It's also called professional liability insurance.
- Errors and oversights
- Late or incomplete work
- Breach of contract

Commercial property insurance
This policy covers your building's physical structure and its contents, such as inventory, computers, and furniture. Bundle it with general liability coverage in a BOP for a discount.
- Storm damage
- Fires
- Theft and vandalism

Commercial umbrella insurance
An umbrella policy provides coverage once the limit is reached on your underlying general liability insurance, commercial auto insurance, or employer's liability insurance.
- Customer lawsuits
- Auto accident lawsuits
- Employee injury lawsuits
Verified business insurance reviews
Hear from customers like you who purchased small business insurance.
Which business insurance policies are required in New York City?
State and local laws can determine the type of coverage you need. These policies help you comply with New York business insurance requirements.

Workers' compensation insurance
The state of New York workers' compensation law requires this coverage for all businesses with employees. That includes both full-time and part-time employees.
NY businesses must either purchase a policy through an insurance company or get permission to self-insure their company.
Workers' compensation covers medical expenses from job-related injuries and illnesses, such as a cleaning business employee becoming sick from cleaner fumes. It also provides disability benefits for injured New York City workers.
Commercial auto insurance
New York state law requires commercial auto insurance for all vehicles that are owned by a business. This insurance policy pays for medical bills, legal costs, and property damage after an auto accident.
New York City businesses must meet the state's requirements for auto liability coverage, which are:
- $10,000 for property damage liability for a single accident
- $25,000 for bodily injury and $50,000 for death for a person involved in an accident
- $50,000 for bodily injury and $100,000 for death for two or more people in an accident
New York also requires no-fault personal injury protection (PIP) and uninsured motorists coverage for all vehicles.
Keep in mind that this is the minimum you're required to carry. It's worth considering higher limits, given the potential cost of a lawsuit. Trucking companies also may need more coverage to comply with regulations.
If you need business insurance coverage for a personal, rented, or leased vehicle, you may want to consider hired and non-owned auto insurance (HNOA) instead.
How much does insurance cost in New York City?
Small businesses in New York City don't have to pay a lot for commercial insurance. Here are a few average costs for New York businesses, based on policy data from Insureon customers:
General liability: $44 per month
Workers' comp: $43 per month
Professional liability/E&O: $97 per month
The cost of business liability insurance depends on factors such as:
- Type of business
- Business operations
- Number of employees
- Policy limits and deductibles
- Claims history
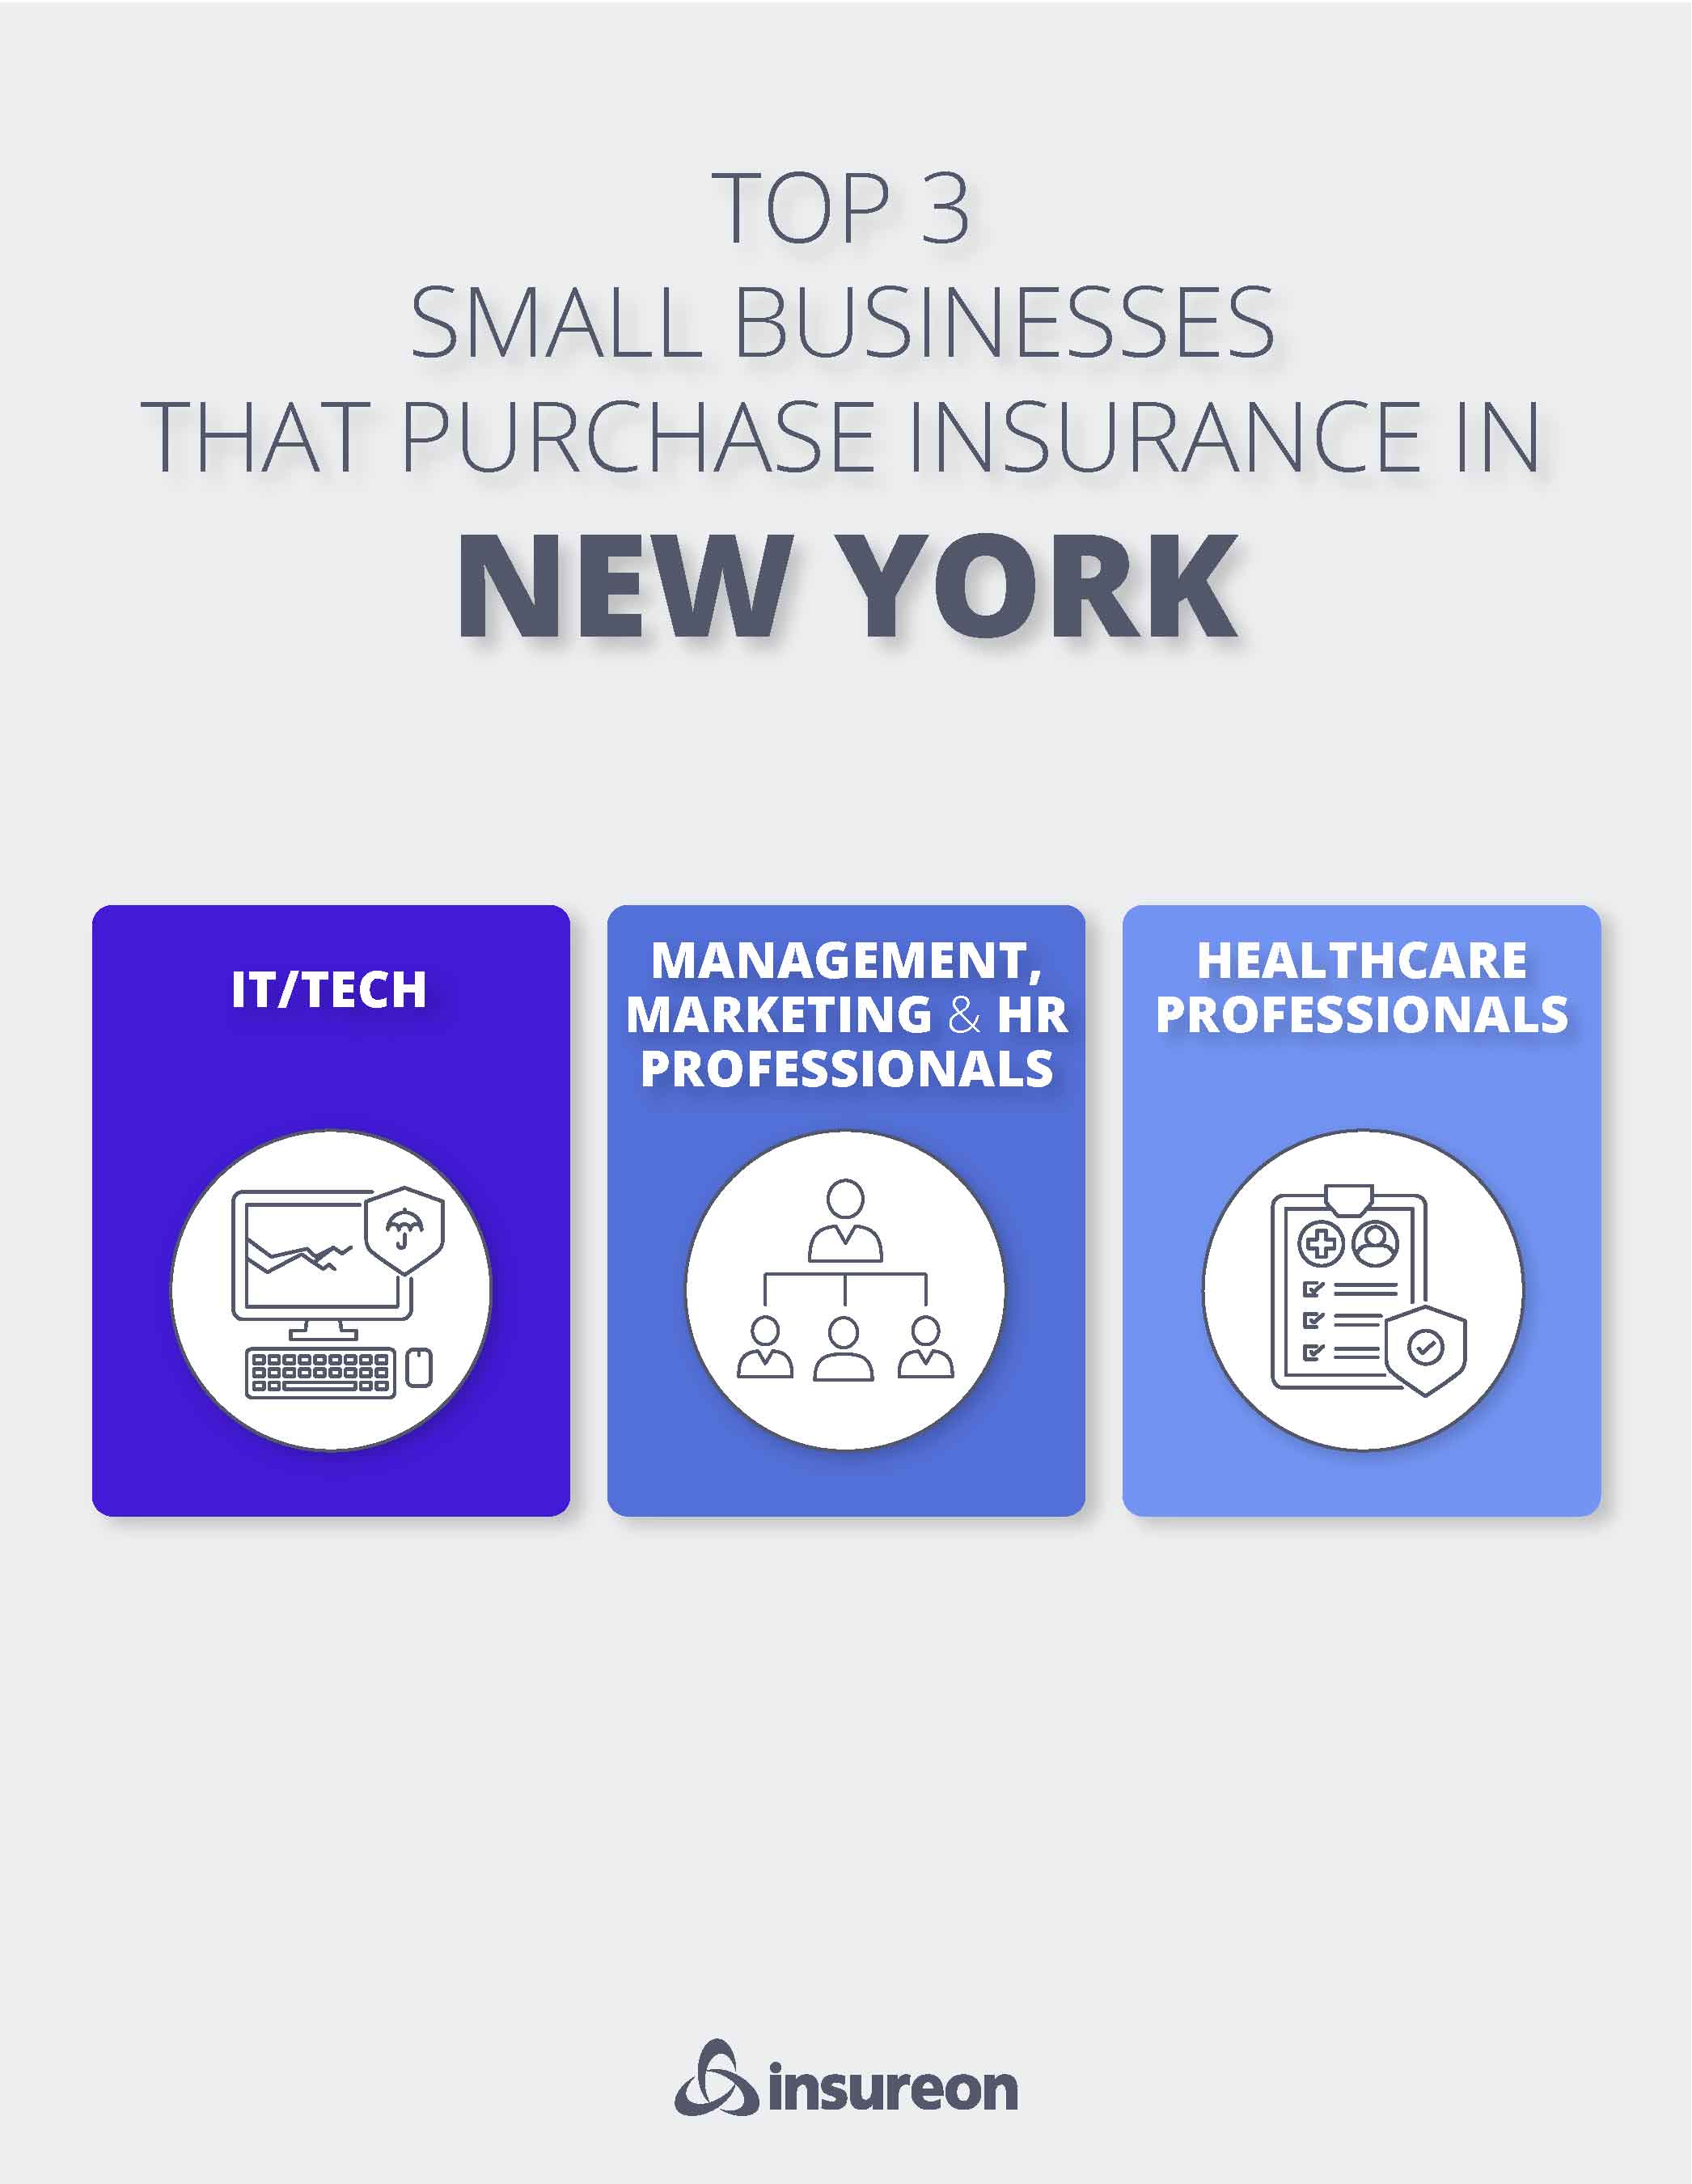
Top professions we insure
FAQs about New York City business insurance
How do I get a certificate of insurance for my business?
Sometimes you need to get insured quickly to sign a contract, lease, or other agreement. With Insureon, you can get same-day insurance in three easy steps:
- Fill out our easy online application to get quotes from top-rated providers.
- Choose a policy and pay for it online.
- Download a certificate of insurance (COI) by logging into your account.
Our licensed insurance agents will help you get coverage that matches your business needs and your budget. New York small business owners can usually get their certificate of insurance within a few hours of applying for quotes.
Can my business be held liable for a data security breach?
Yes – that's why cyber insurance is so crucial. Small businesses are a common target of cyberattacks since they often have fewer security measures in place.
New York's data breach laws require NYC businesses to notify any residents whose personal information is exposed in a data breach, in addition to three state offices. Your business could also end up paying for a data breach investigation, a PR campaign, and other costs related to a breach or cyberattack.
Cyber liability insurance covers these costs and provides resources so you can get back to business fast.
Does my industry affect NYC business requirements?
Yes, New York City may require you to buy certain types of business insurance or bonds, depending on your profession. You may also need a business license or permit to operate in the city or do certain types of work.
Here are a few examples of local requirements:
- All businesses in New York that sell products or offer services subject to sales tax must obtain a Certificate of Authority.
- Home improvement contractors and some handymen need to provide workers' compensation insurance information to comply with NYC licensing requirements.
- General contractors who build one-, two-, and three-family homes must be registered in NYC and carry contractor general liability insurance with a per-occurrence limit of at least $1 million and a surety bond.
- Real estate brokers must get a New York license to work legally.
- Personal care professionals need a cosmetology license from the New York State Department of State (NYSDOS) to practice nail or hair styling, waxing, and beauty treatments.
- New York City window cleaners must use techniques and equipment approved by the New York State Department of Labor.
When running a business in New York City, you need to be aware of laws and regulations for New York, your county, and the city of New York.
How can I get help starting a small business in New York City?
Nearly half of New York City's small businesses are owned by immigrants, which adds to the city's vibrancy and uniqueness. Though small businesses can struggle with high rent in the city and strong competition, there's ample support to help you get started:
- NYC Small Business Services offers a step-by-step guide to opening a small business in the city, along with resources to grow and thrive.
- The Greater New York Chamber of Commerce provides networking opportunities, webinars, and resources for business owners. You can find a local chamber specifically for women, different nationalities, and different geographical regions within NYC.
- SCORE NYC is a group of volunteer business mentors and advisors offering free support for small business owners and entrepreneurs.
- The U.S. Small Business Administration (SBA) supplies information on starting a business, including sources of funding and free business counseling.
- Empire State Development’s Small Business Division offers programs and support for small businesses that have less than 100 employees.
How can I save money on New York City business insurance?
New York business owners can save money by comparing quotes from different insurance carriers. With Insureon, you can get free quotes from top-rated carriers by filling out one easy application.
There are a few other ways to save, such as:
- Bundle insurance products for a discount. The most popular option is a business owner's policy.
- Choose less expensive coverage options, such as lower limits or a higher deductible.
- Focus on workplace safety. Fewer accidents mean fewer claims, which helps keep your premium low.
Learn more about how to find cheap business insurance.