Business Insurance for Insurance Professionals


Top insurance professionals we insure
Recommended business insurance for insurance specialists
Insureon helps property and casualty insurance agents and other insurance professionals protect their businesses. With the right property and liability coverage, your business can recover quickly from lawsuits and other risks.

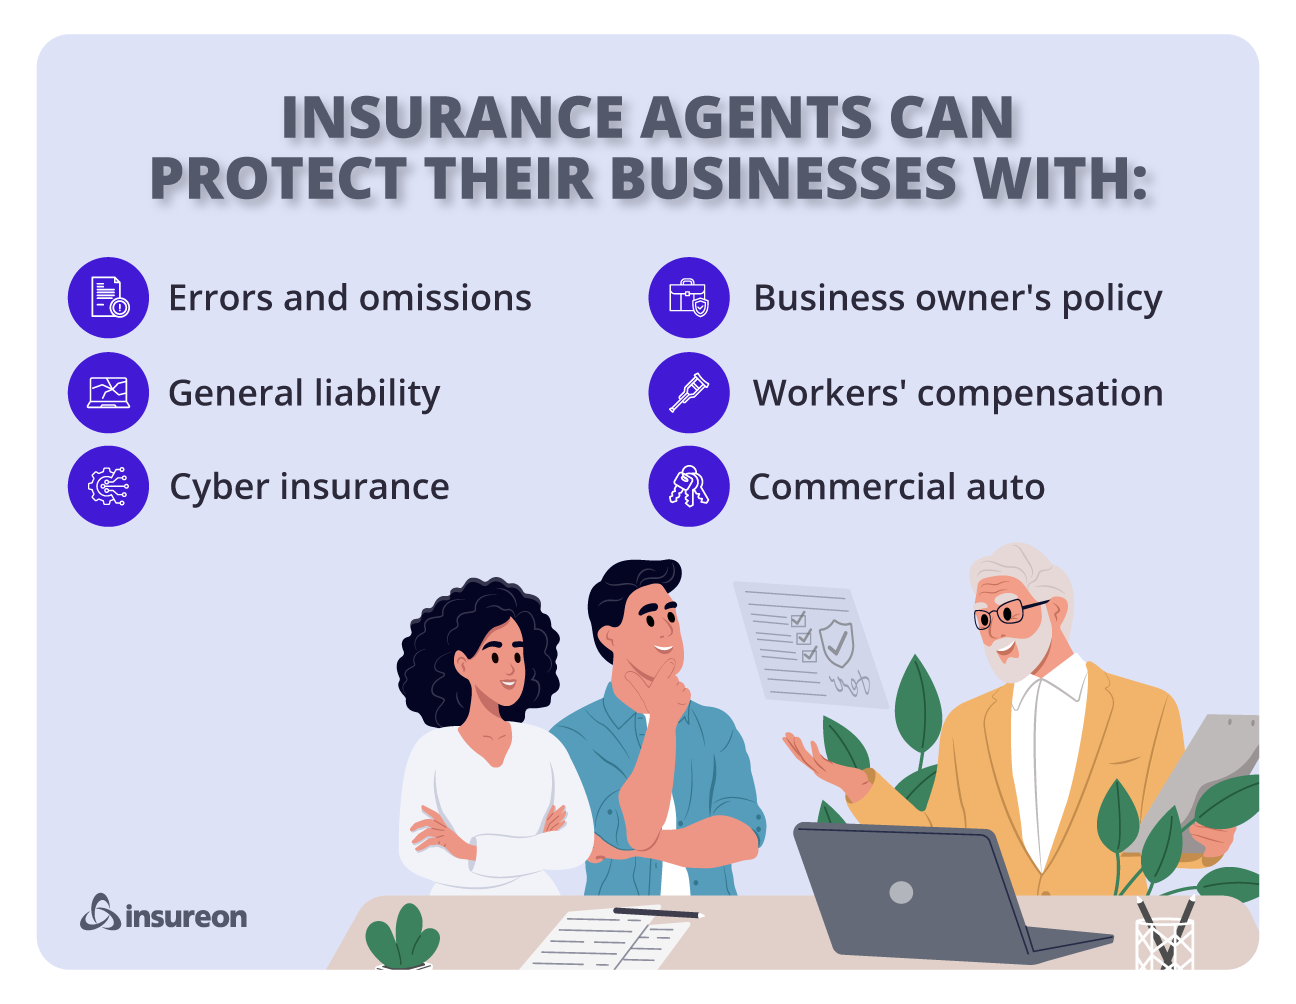
Errors and omissions insurance
E&O insurance covers legal defense costs related to work performance, such as a P&C agent sued for negligence in a claims dispute. It's also called professional liability insurance.
- Accusations of negligence
- Work errors and oversights
- Failure to provide professional services

General liability insurance
This policy covers basic third-party risks, such as a customer who suffers an injury at your insurance agency. Bundle it with property insurance for savings in a business owner’s policy (BOP).
- Slip-and-fall accidents
- Damaged customer property
- Libel and slander lawsuits

Business owner’s policy
A BOP bundles property insurance and general liability insurance under one plan. It's often the most cost-effective type of commercial insurance for insurance professionals.
- Customer injuries
- Damaged customer property
- Damaged business property

Workers’ compensation insurance
Most states require workers' comp for insurance businesses that have employees. It also protects sole proprietors from work injury costs that health insurance might deny.
- Employee medical expenses
- Lawsuits from employee injuries
- Disability benefits

Commercial auto insurance
This policy is required for cars and other vehicles owned by an insurance business. It helps cover medical bills and property damage if the vehicle is involved in an accident.
- Property damage caused by your vehicle
- Medical bills from auto accidents
- Vehicle theft and vandalism

Cyber insurance
Cyber insurance helps insurance businesses recover from data breaches and cyberattacks. It's strongly recommended for any business that handles private information.
- Data breach notification costs
- Fraud monitoring services
- Security breach investigations
How much does commercial insurance cost for insurance professionals?
Several factors will have an impact on your business insurance costs, including:
- The insurance products and services you offer
- Your business equipment and property
- Your business's size and revenue
- Policy limits, deductibles, and other coverage options
- Annual premium payments vs. monthly payments
How do I get business insurance for insurance professionals?
It’s easy to find business insurance for insurance agents and other insurance professionals. Whatever your specialty, you’ll need to have some basic information about your business available.
Our application will ask you for your annual revenue and payroll, among other details. You can buy a policy online and get a certificate of insurance with Insureon in three easy steps:
- Complete a free online application.
- Compare free quotes and choose a policy.
- Pay for your policy and download a certificate for proof of insurance.
Insureon's licensed insurance agents work with top-rated U.S. providers to find the right coverage for your insurance business, whether you work as an independent agent or hire employees.
Verified business insurance reviews
Hear from customers like you who purchased small business insurance.
Common questions about business insurance for insurance professionals
Why is errors and omissions insurance coverage important for insurance professionals?
E&O insurance, also called professional liability insurance, provides crucial protection in the event of a lawsuit. Because your work can directly impact a client's finances, you face a high risk of lawsuits. For example:
- A client could sue an independent insurance agent for telling them they were covered for something that turned out to be an exclusion.
- A delay or error in paperwork from an agency could lead to a client not having coverage when they need it.
- You might do nothing wrong, but a client could still sue you to try and recoup their financial losses.
If you're sued, errors and omissions insurance can help pay for attorney's fees, court costs, court-ordered judgments, or even a settlement.
Do insurance professionals need a license to sell insurance?
Each state has its own licensing requirements for insurance agents and brokers. If you try to sell insurance without a license, you could face severe penalties, including jail time.
To become an insurance agent, you'll need to fulfill your state's requirements. For instance, you may need to:
- Take courses on insurance
- Pass an exam
- Submit to a background check and fingerprinting
- Pay a fee
You can still perform some tasks in an insurance agency without a license, such as returning calls, setting up meetings, and assisting with paperwork.
What other insurance policies should insurance professionals carry?
Whether you are an independent insurance agent or work for an insurance company, you may need additional types of coverage to fully protect your business. For example, you may want to consider:
- Electronic data processing (EDP) insurance: This policy covers financial losses if a fire, natural disaster, or other incident damages or destroys your computers, backup drives, and other business data and devices.
- Hired and non-owned auto insurance (HNOA): Insurance professionals who drive their personal vehicle for work should invest in this coverage to protect against legal costs in the event of an accident. It also covers leased and rented vehicles.
- Fidelity bonds: Being bonded is a sign of dependability, and clients may require you to carry a bond. They provide protection for your clients by reimbursing them in the event of employee theft.
Find quotes for insurance professionals
Read our blog posts



Want free expert advice right in your inbox?
By entering your email address and subscribing, you agree to our Terms of Use and Privacy Policy