

General liability vs. product liability insurance
What is the difference between product liability insurance and general liability insurance?
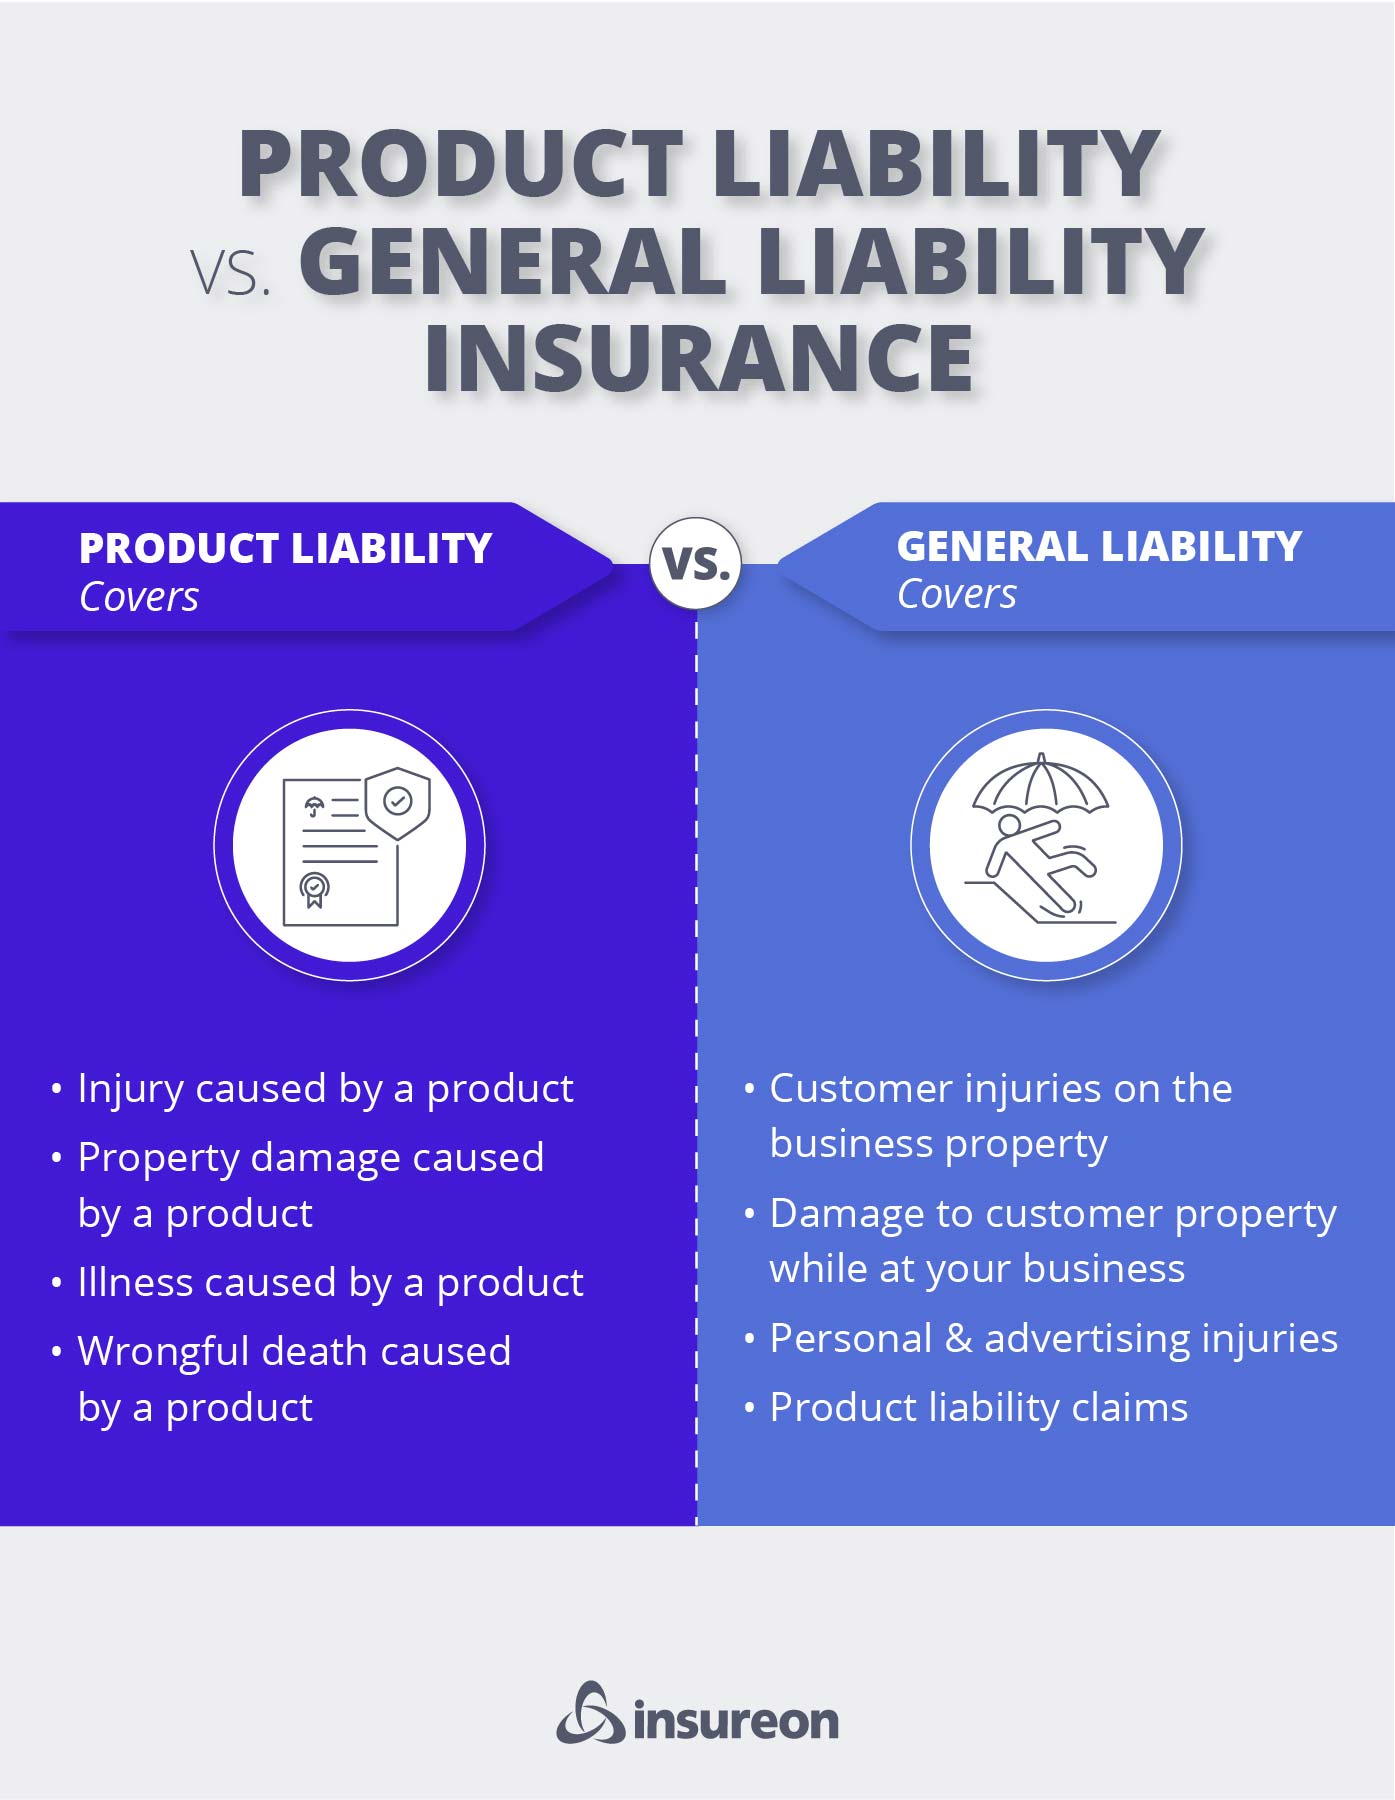
Product liability insurance and general liability insurance both cover third-party incidents, but for different risks:
- General liability covers incidents related to injury, property damage, and advertising injuries
- Product liability insurance covers product-specific legal expenses
Most commercial general liability policies contain product liability insurance, so having general liability coverage will often provide the coverage of both policies. However, it must sometimes be purchased as an endorsement.
Here's a closer look at each type of coverage:
What is general liability insurance?
General liability insurance covers common third-party liability claims for many small businesses, including:
- If a third party falls or otherwise sustains a bodily injury while on your business property or doing business with your company.
- When a third party's property, such as a cellphone, is broken or suffers property damage by your business during normal business operations.
- If your business is accused of engaging in advertising injuries or personal injuries such as slander, libel, or copyright infringement.
Some businesses have more interaction with the general public, such as retailers and restaurants, and have a greater need for general liability coverage than businesses with fewer third-party exposures, such as home-based businesses with little foot traffic.
What is product liability insurance?
Product liability insurance protects your business if a customer claims that a product your business makes, sells, or distributes caused them harm or financial loss, such as medical expenses. This policy would help pay legal fees related to lawsuits filed against your company for product-related incidents.
Sometimes referred to as products-completed operations, product liability coverage is often purchased by retailers, wholesalers, and manufacturers to protect against product liability claims related to:
- Manufacturing defects
- Labeling issues
- Product defects
- Allergic reactions
- Design defects
- Wrongful deaths that result from product issues
- Strict liability for when a product causes damage but it's not your fault
This policy does not protect against product recalls of defective products. For this, you'd need a separate product recall insurance policy. It also does not generally cover employee injuries, which would need to be covered under a workers' compensation insurance policy.
Do you need both product liability and general liability insurance?
Many commercial general liability insurance policies already include a product liability insurance policy.
You can check with your insurance company to ensure you're properly protected from all of your industry risks.
Protect your business with the right insurance policies with Insureon
Obtaining insurance coverage is quick and easy with Insureon. Fill out our online application, and we'll provide you with free liability insurance quotes from the U.S.'s top providers.
If you have questions, you can contact a licensed insurance agent who can walk you through your options.
Our agents can also help you explore other types of insurance, such as a business owner's policy or professional liability, in order to operate your business with peace of mind, knowing you're protected from common risks and legal liabilities.
Verified general liability coverage reviews
Find small business insurance quotes



Want free expert advice right in your inbox?
By entering your email address and subscribing, you agree to our Terms of Use and Privacy Policy