

Employer's liability vs. employment practices liability insurance (EPLI)
What is the difference between employer's liability insurance vs. employment practices liability insurance?
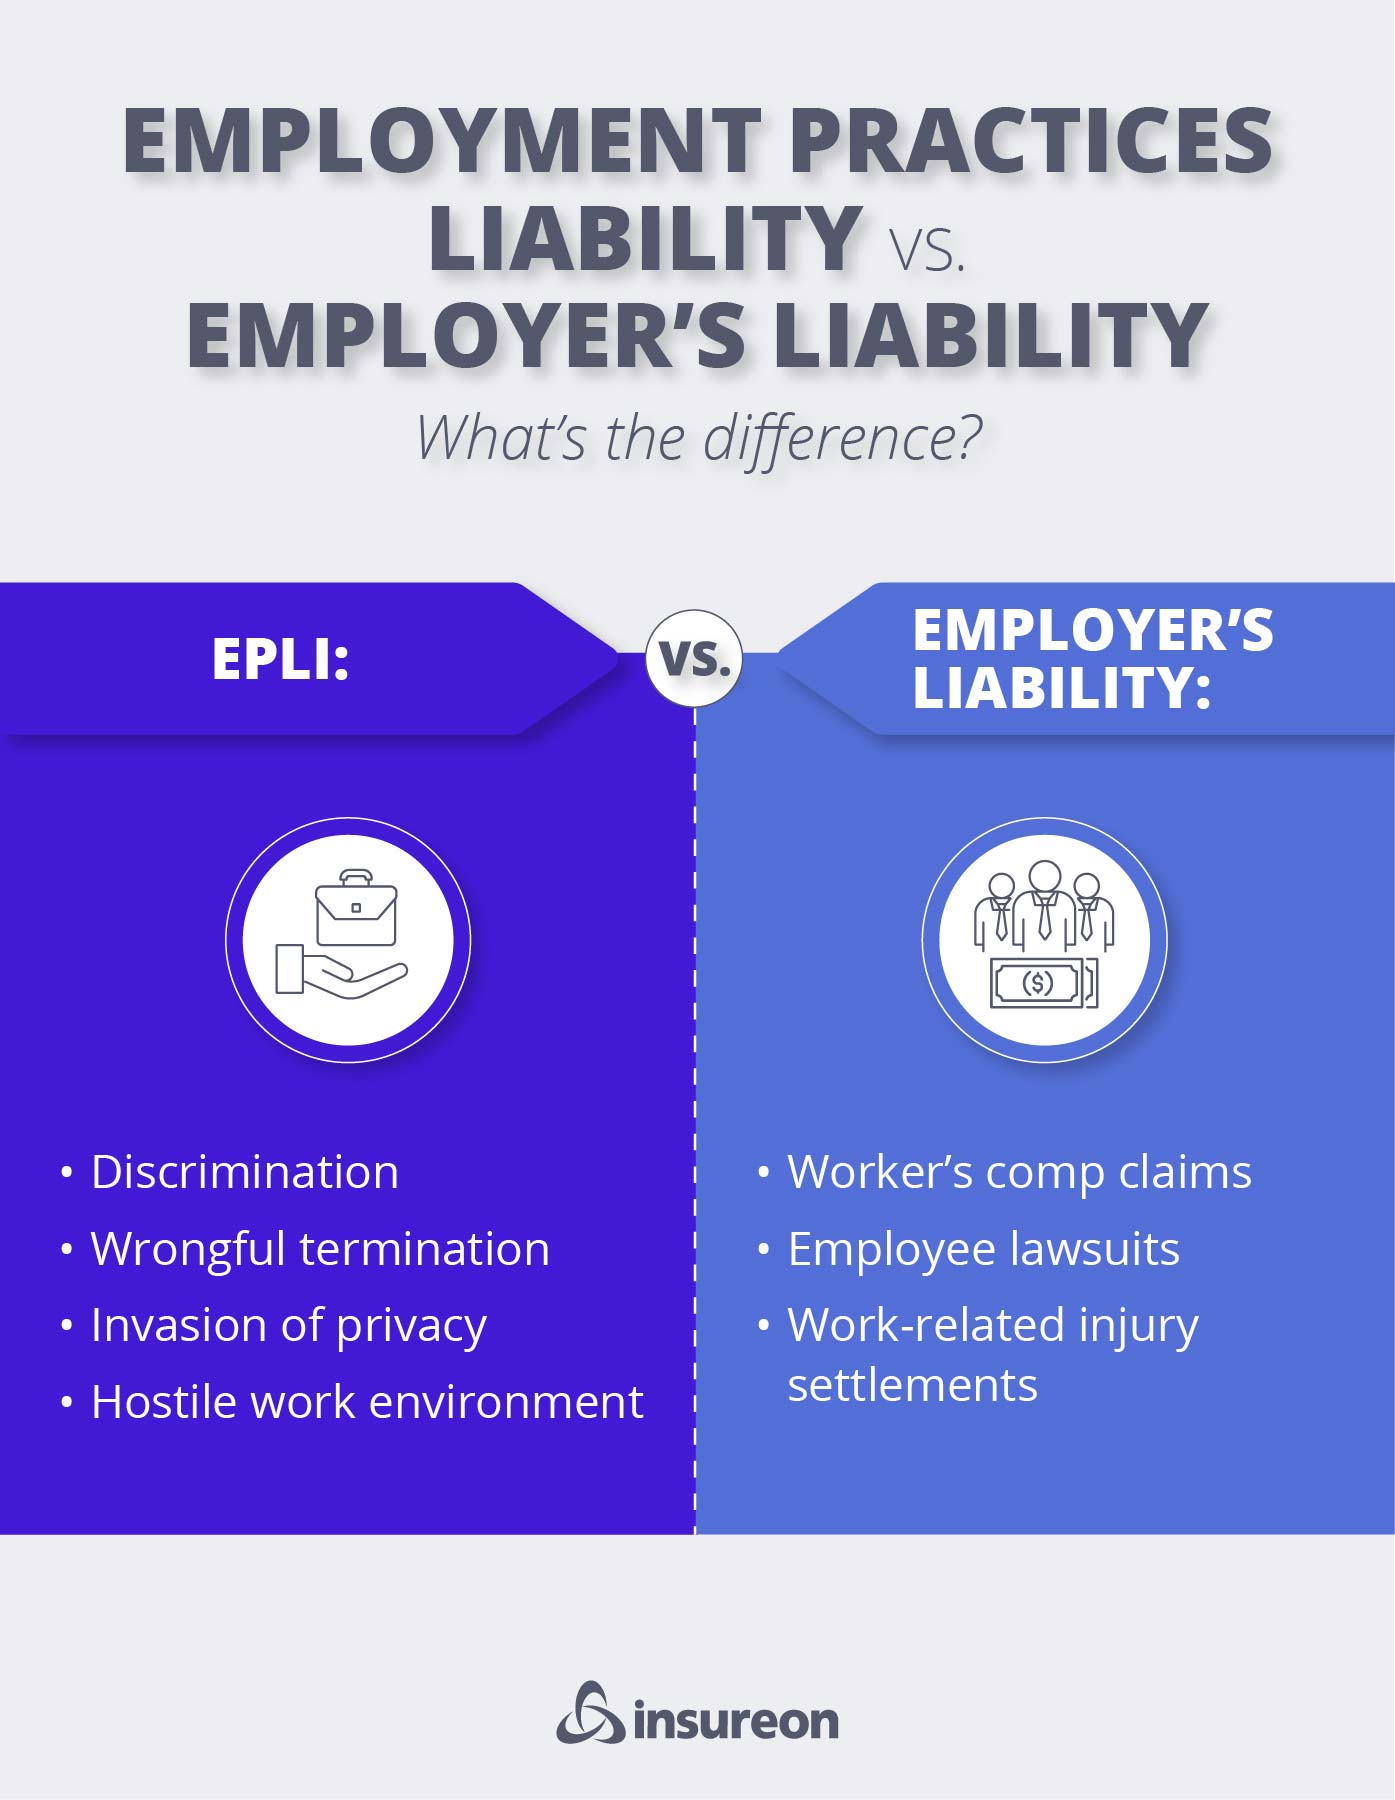
Employer's liability insurance and employment practices liability insurance (EPLI) both help small business owners navigate expensive lawsuits related to employees, but they cover different things and are not interchangeable.
- Employer's liability insurance covers workplace injury lawsuits.
- Employment practices liability insurance covers lawsuits related to employment-related issues.
A major difference between these two policies is that employer's liability is often required for businesses with employees, whereas EPLI is generally not required by law, regardless of staff size.
Let's take a closer look at each type of insurance:
What is employer's liability insurance?
Employer's liability insurance is typically included in a workers’ compensation policy, which is required by most states for businesses with at least one employee. Workers’ comp provides financial assistance for medical bills, disability benefits, and lost wages if an employee suffers work-related injuries or illness.
On top of that, employer’s liability will cover employers against employee-related legal claims, including:
- Third-party-over action claims, like if an employee sues a third party over a workplace injury, and the third party turns around and sues the employer.
- Loss of consortium claims, such as if an employee’s family members seek punitive damages from the employer if their relative has a debilitating illness, suffered a serious bodily injury, or died in a work-related accident.
- Dual-capacity lawsuits, such as when an employee is injured from using one of the employer’s products, then sues the company in its capacity as both an employer and a manufacturer.
- Consequential bodily injury claims, which can be filed by a non-employee who is impacted by an employee’s work-related injury or illness, such as a family member who faces health problems from caring for an injured worker.
If you live in a state where you can (or are required to) purchase workers' comp from a state fund, your policy will not include employer's liability insurance coverage. You can purchase it separately as a standalone stop gap coverage policy, or as an endorsement to a general liability policy.
What is employment practices liability insurance (EPLI)?
Employment practices liability coverage is a type of management liability insurance that provides legal defense for small business owners in lawsuits related to employment issues. These can include:
- Defamation, such as slander and libel
- Wrongful termination claims
- Sexual harassment and emotional distress
- Employee benefits mismanagement
- Breach of contract
- Discrimination claims
If an employee claims they were mistreated and brings a lawsuit against your business, an employment practices liability insurance policy would help you pay legal expenses, court fees, judgments, punitive damages, settlements, and other financial losses.
Do you need both EPLI and employer's liability insurance?
Because these two policies cover different aspects of employment, both types of insurance are encouraged for small businesses with employees.
You can do your best to create a safe and inclusive work environment, but your employees may still feel bullied or mistreated and take you to court. EPLI would protect your business from these claims.
For example, a caregiver feels targeted by her colleagues and supervisor. She brings an employment-related claim against the company. However, because the agency is covered by EPLI, the legal defense costs are covered (besides the deductible).
On the other hand, you could do your best to practice risk management and maintain a safe work culture, but injuries can happen anywhere, making workers' compensation (and employer's liability) a must.
For example, a software engineer develops carpal tunnel and loses partial functionality in their hands. The injured employee sues their employer for not providing proper equipment. The employer has a state-funded workers' comp policy that covers the medical expenses, but does not have employer's liability. The company is required to cover its own legal costs.
Purchase the right workers' compensation and EPLI coverage to ensure your business is protected against the most common employment-related and workers' compensation claims.
Protect your business with the right insurance policies with Insureon
Get small business insurance by completing Insureon's easy online application. We'll provide free quotes from leading U.S. insurance companies.
Our licensed insurance agents can help you find the right liability coverage for your insurance needs and answer any questions you may have about premium pricing and insurance costs.
We can also help you find other small business options, such as general liability insurance.
Once you pick the perfect policies, we'll help you get a certificate of insurance (COI), often within 24 hours.
Verified workers' compensation insurance reviews
Get insurance quotes for your small business


Want free expert advice right in your inbox?
By entering your email address and subscribing, you agree to our Terms of Use and Privacy Policy