

Excess liability vs. umbrella liability insurance
Although excess liability and umbrella liability coverage both extend liability insurance coverage limits, they’re different commercial lines insurance policies. Here’s what you need to know about these two types of extended coverage and when your small business might need them.
- What is the difference between excess liability and commercial umbrella insurance?
- How do excess liability and commercial umbrella coverage work?
- How much does excess liability or commercial umbrella insurance cost?
- Who needs excess liability or umbrella liability insurance?
- Does my business need both excess and umbrella liability insurance?
- Get small business insurance quotes with Insureon
What is the difference between excess liability and commercial umbrella insurance?
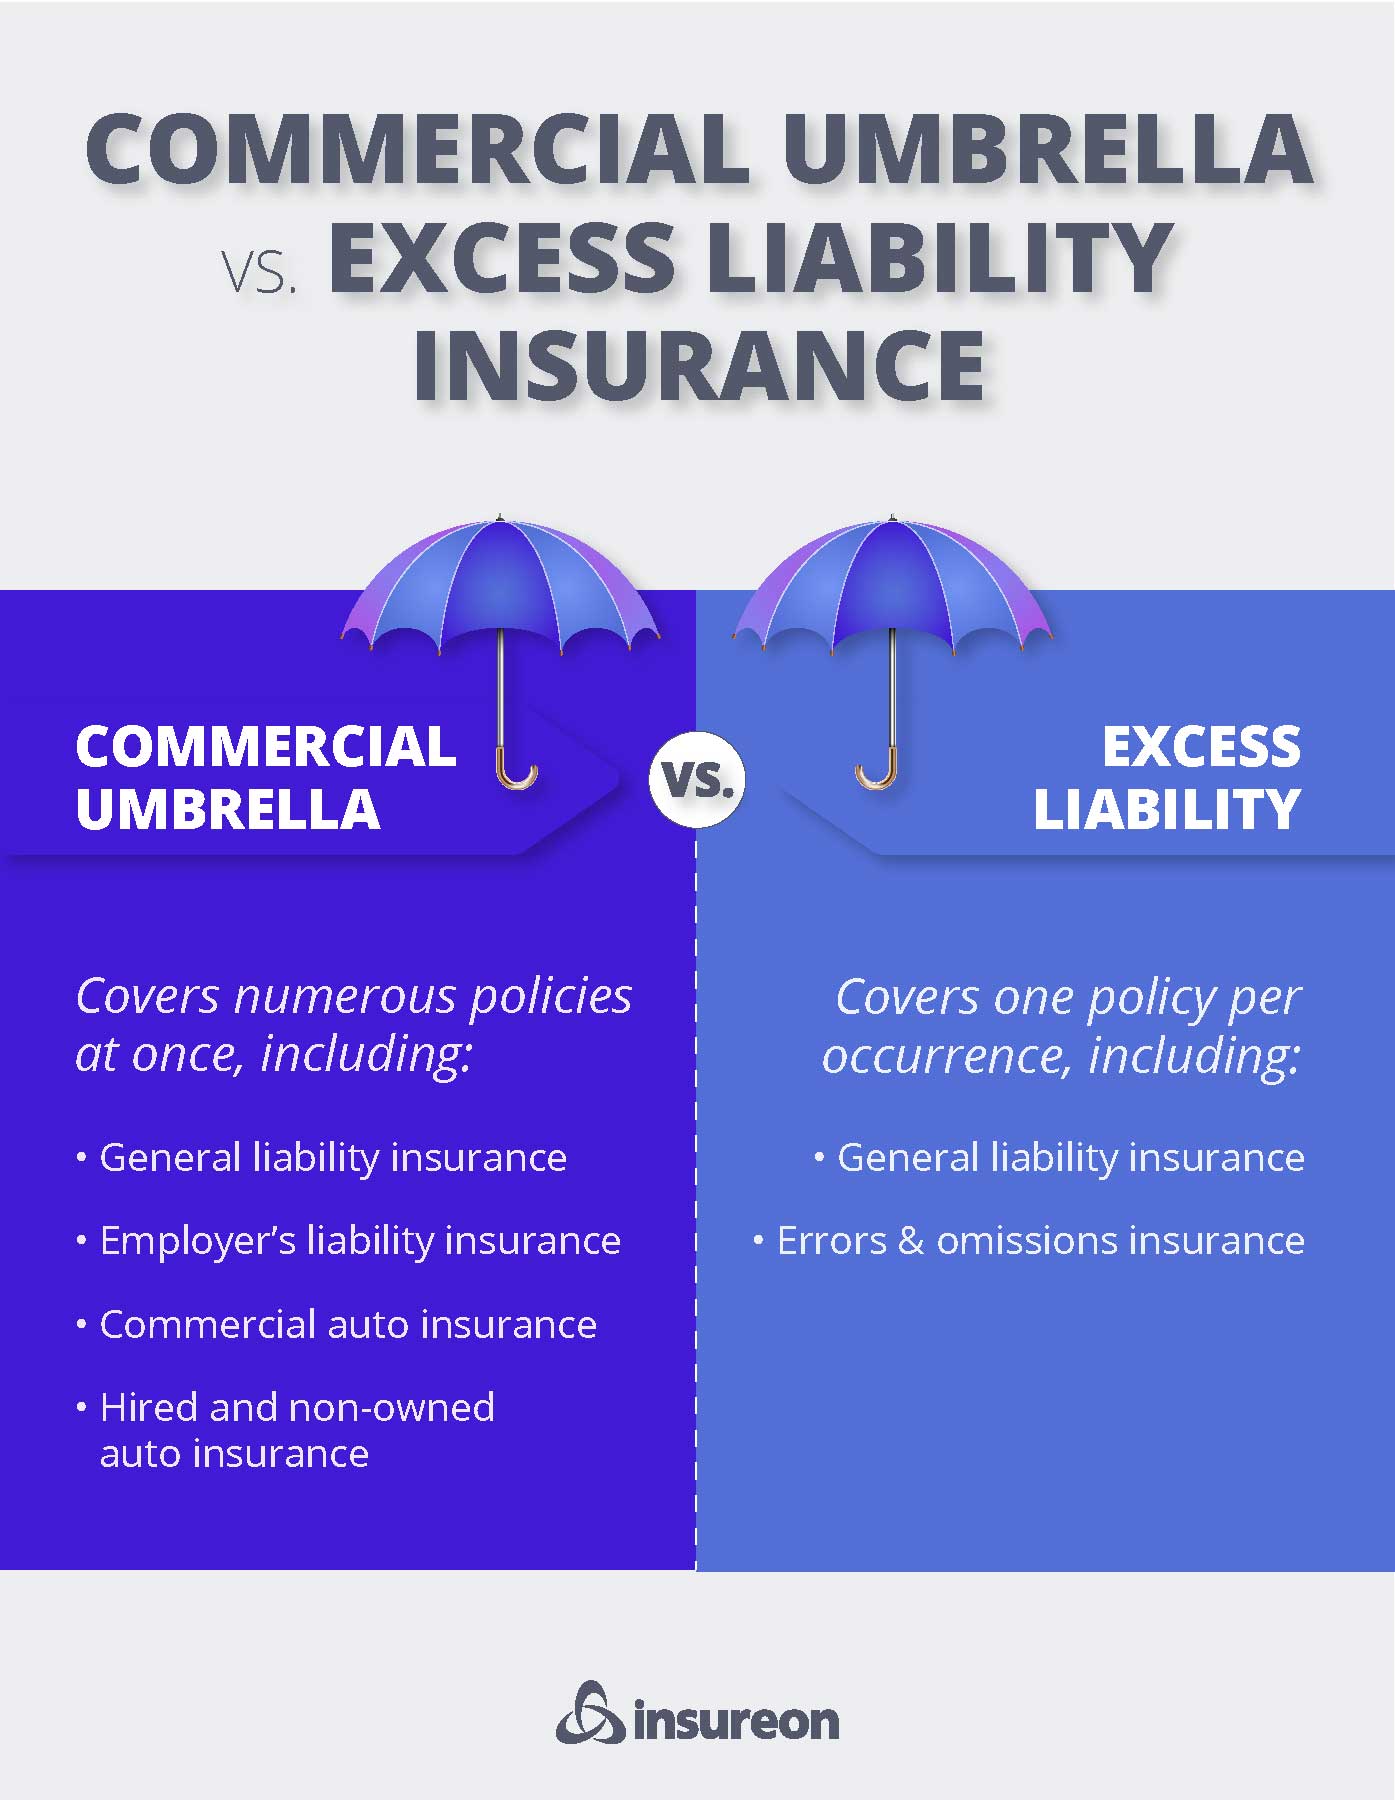
Excess liability insurance and commercial umbrella liability insurance both provide extra layers of financial protection when a claim exceeds your primary policy limits. The main difference is that excess liability only increases the coverage limits of one specific policy, while umbrella insurance extends the limits to multiple underlying policies.
Here's a closer look at how these two extended coverage policies work:
What is excess liability insurance?
Excess liability insurance provides additional coverage limits to one primary liability policy. This coverage comes in once the policy limits of the underlying policy have been exhausted. Excess liability is often added to policies like:
- General liability insurance: If a third-party bodily injury or property damage claim exceeds your general liability policy limits, excess liability will help cover additional expenses, including costs for lawsuits, settlements, judgments, and some product liability claims involving bodily injury.
- Professional liability insurance: Should a client claim that your error, missed deadline, or professional negligence caused them to lose money, excess liability will extend professional liability policy limits to cover attorney fees, settlements, and other legal costs. This coverage is also called errors and omissions (E&O) insurance.
What is umbrella liability insurance?
Umbrella liability insurance sits atop several liability policies at the same time. It will raise the policy limits for whichever underlying liability policy is exhausted by a claim, including:
- General liability insurance: Umbrella insurance will provide additional coverage for common business risks, including slip-and-fall injuries and customer property damage, that can exhaust your underlying general liability coverage.
- Commercial auto insurance: If your business vehicle is involved in an accident, an umbrella policy can increase your auto coverage to help pay for legal bills, medical expenses, and property damage.
- Hired and non-owned auto (HNOA) insurance: If a personal, leased, or rented vehicle used by your business is involved in an accident, umbrella liability coverage can extend your HNOA coverage to help pay for substantial claims.
- Employer's liability insurance: If an employee sues over a work injury or illness, umbrella insurance can increase your policy limits to cover legal costs that exceed your underlying employer's liability coverage. This policy is often included in workers' compensation insurance.
How do excess liability and commercial umbrella coverage work?
Excess liability and commercial umbrella coverage work similarly, extending coverage for liability policies when an underlying policy reaches its limit. However, they differ in the number of policies they cover.
Let's say you have a general liability policy with $1 million per-occurrence / $2 million aggregate (also called general aggregate) and a $1 million excess liability policy. If you're found liable for $1.5 million in damages:
- Your general liability policy will pay $1 million
- The excess liability policy will cover the remaining $500,000
Excess liability only applies to one specific underlying policy, so you wouldn't be able to apply the coverage to a claim on a different policy.
A commercial umbrella policy, on the other hand, can be used across multiple underlying liability policies. So, if you have standard policies for general liability, commercial auto, and employer's liability insurance, your umbrella insurance would help pay for a claim that exceeds the coverage limits on any of those policies.
Some excess and umbrella policies have a self-insured retention (SIR), which is an amount you agree to pay out of pocket before the extra coverage comes in (although this can mean lower premiums). Unlike a deductible, which the insurer usually subtracts from the amount paid on a claim, an SIR must be paid before the insurer even gets involved.


How much does excess liability or commercial umbrella insurance cost?
Excess liability insurance costs about $50 per month per $1 million of coverage, while commercial umbrella insurance costs roughly $40 per month for every $1 million of additional coverage purchased.
Most small businesses buy an underlying liability insurance policy with $2 million per-occurrence / $4 million aggregate limits and then add umbrella or excess insurance for higher limits.
Insurers will consider several different factors about your business during underwriting to calculate your costs, including liability risks, coverage limits, and your industry.
Who needs excess liability or umbrella liability insurance?
Extended liability coverage offers many benefits, especially for businesses that:
- Face higher liability risks, such as retail stores with substantial foot traffic.
- Need greater liability protection to get a contract with a particular client or sign a commercial lease.
- Operate in industries where a single claim, like a serious workplace injury or multi-vehicle accident, would likely exceed their standard policy limits.
The right type of extended coverage depends on which underlying policies a business needs to extend. Here are some examples of when a business might need umbrella coverage versus excess liability insurance:
| Excess liability | Umbrella liability | |
|---|---|---|
To extend tech E&O policy limits in case of software errors or data breaches | When they have a team of field technicians who travel to clients’ offices | |
To increase errors and omissions coverage against negligence or misrepresentation claims | When managing multiple properties with a team of agents who use their personal vehicles for work | |
To fulfill terms of a client’s contract that requires higher general liability limits | When there’s a greater risk for jobsite injuries, property damage, and personal injury claims | |
To sign a commercial lease that mandates higher general liability coverage | When they employ a large staff or operate delivery vehicles | |
To meet a commercial client’s service agreement terms for higher general liability limits | When crews drive company vans to jobsites and employees are at more risk of workplace injuries |
Top professions we insure
Does my business need both excess and umbrella liability insurance?
Most businesses do not need both excess liability and umbrella liability policies. However, businesses with significant risk exposure in one area and risk across various others may find that one policy isn't enough. This may include:
- Commercial trucking companies: While umbrella liability would cover the substantial auto liability exposure across a fleet of vehicles and multiple drivers, they might also carry excess liability if a single loss event could exceed their underlying general liability coverage.
- Commercial builders: An umbrella policy would extend across their general liability, employer's liability, and auto insurance policies, but they may also carry excess liability over their general liability when a project owner requires coverage limits that umbrella can't meet on its own.
- Landscaping companies: Umbrella insurance would cover crew vehicles, customer property damage, and employee injuries, but a business operating in high-end residential or commercial properties may also carry excess over their general liability coverage in case a single damage or injury claim runs exceptionally high.
Get small business insurance quotes with Insureon
Insureon's licensed insurance agents can help you secure affordable insurance coverage for all of your small business needs. With just one easy online application, you can compare quotes for extended coverage from our top-rated insurance partners.
Once you find the right policies, you can typically begin coverage and get a certificate of insurance (COI) for your small business in less than 24 hours.
Verified business insurance reviews
Hear from customers like you who purchased small business insurance.
The average costs on this page were derived from our data on 100,000 small business owners who purchased policies through Insureon. Most of our customers have fewer than five employees, annual revenue ranging from less than $50,000 to more than $200,000, and have been in business for five years or less.
Find small business insurance quotes


Want free expert advice right in your inbox?
By entering your email address and subscribing, you agree to our Terms of Use and Privacy Policy